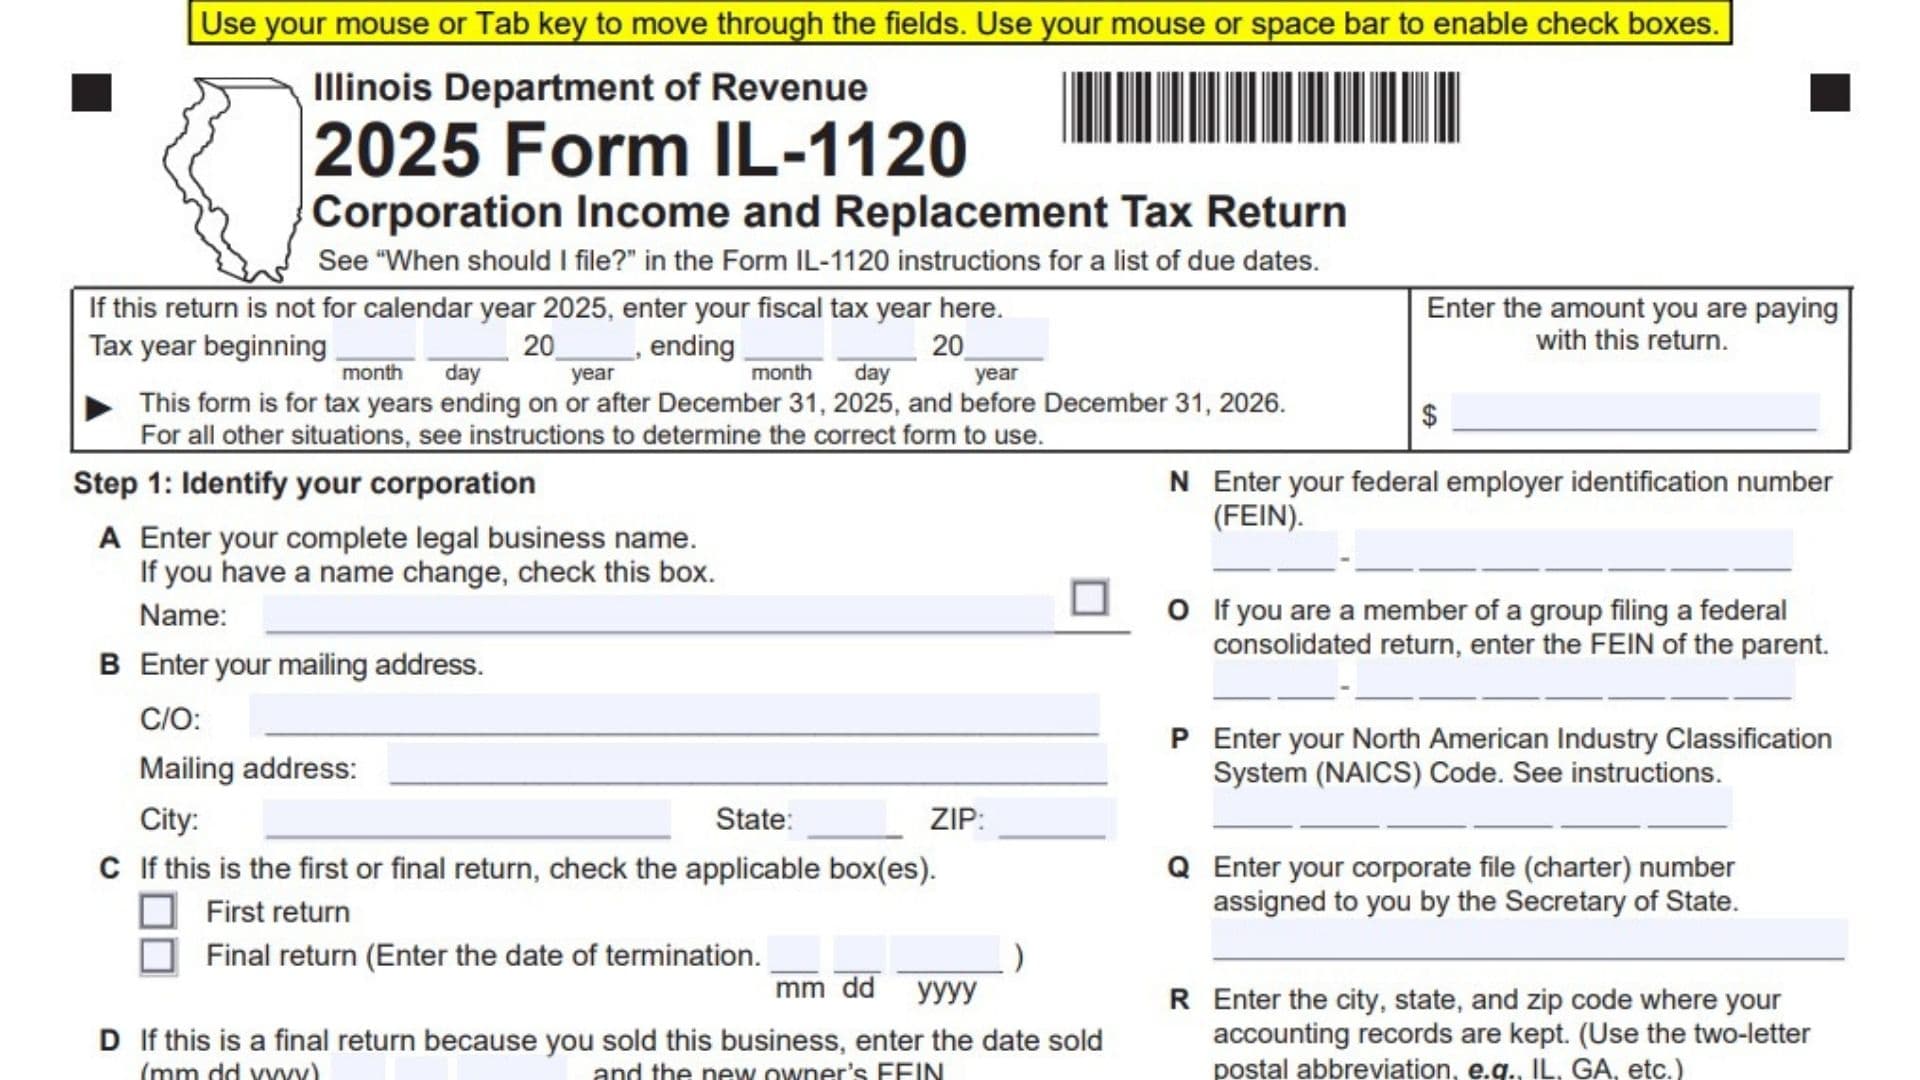
Illinois Form IL-1120, titled Corporation Income and Replacement Tax Return, is used by corporations to report their income, calculate Illinois income and replacement taxes, claim applicable credits, report payments, and determine whether they owe additional tax or qualify for a refund. The form collects information about the corporation, its federal taxable income, Illinois-specific additions and subtractions, business income allocation, net income, tax credits, estimated tax payments, and other adjustments that affect the corporation’s Illinois tax liability. It also identifies certain business classifications, accounting methods, apportionment formulas, and supporting schedules that may be required with the return. The 2025 version is intended for tax years ending on or after December 31, 2025, and before December 31, 2026. Corporations with other tax periods should consult the applicable instructions to determine which form to use. Completing Form IL-1120 accurately is important because errors in income calculations, allocation factors, deductions, tax credits, or payments can affect the amount of tax due or the refund available. The return also requires supporting federal and Illinois tax documents for various entries. Depending on the corporation’s activities and circumstances, these may include federal Form 1120, Illinois Schedule M, Schedule 80/20, Schedule NB, Schedule 1299-D, and other applicable forms. The corporation must calculate its tax liability using the amounts and adjustments required by the form, report payments and credits correctly, and complete the signature section before submitting the return. The instructions below explain each section and line, including when a field applies and which supporting documents the form identifies.
How To File Form IL-1120
Form IL-1120 is filed with the Illinois Department of Revenue. The applicable filing deadline depends on the corporation’s circumstances and tax period, so review the official Form IL-1120 instructions for the correct due date.
Documents to Prepare Before Completing the Return
Gather the following records and supporting forms, as applicable:
- Federal Form 1120, including pages 1 through 6 or an equivalent return.
- The corporation’s federal taxable income and net operating loss information.
- Illinois depreciation adjustments and Form IL-4562.
- Schedule 80/20 for related-party expense adjustments.
- Schedules K-1-P or K-1-T for distributive shares, pass-through withholding, and pass-through entity tax credits.
- Schedule M for other Illinois additions and subtractions.
- Schedule 1299-B for applicable subtractions.
- Illinois Schedule J for foreign dividend subtraction.
- Schedule UB or the Subgroup Schedule, when applicable.
- Schedule INS or Schedule UB/INS, when applicable.
- Schedule NB for nonbusiness income or loss.
- Schedule NLD or UB/NLD for the Illinois net loss deduction.
- Schedule 4255 for investment credit recaptures.
- Form IL-477 for investment credits.
- Schedule 1299-D and any required supporting documents for income tax credits.
- Federal Form 982 for applicable discharge of indebtedness adjustments.
- Form IL-2220 for estimated tax underpayment penalties, when applicable.
- Forms W-2G for applicable Illinois income tax withholding.
Not every corporation needs every document. Use the supporting-document requirements associated with the applicable lines of the return.
Mailing and Payment Instructions
If the corporation owes tax on line 67, the form directs the corporation to make an electronic payment through Tax.Illinois.gov. If payment is mailed, complete Form IL-1120-V and include it with the payment.
Write the corporation’s federal employer identification number (FEIN), tax year ending date, and “IL-1120-V” on the check or money order. Make the payment payable to the Illinois Department of Revenue. Enter the payment amount in the space provided at the top of page 1.
The form provides these mailing addresses:
- If no payment is enclosed:Illinois Department of Revenue
PO Box 19048
Springfield, IL 62794-9048 - If payment is enclosed:Illinois Department of Revenue
PO Box 19038
Springfield, IL 62794-9038
Follow the applicable filing instructions to confirm the correct submission method and any additional requirements.
How To Complete Form IL-1120
The 2025 form contains four pages and nine main steps. Page 1 identifies the corporation and its filing circumstances. Page 2 calculates income, subtractions, and Illinois income allocation. Page 3 calculates net income, taxes, credits, payments, refunds, and balances due, and includes the signature section. Page 4 lists the supporting documents that must accompany applicable entries.
Page 1: Identify Your Corporation
Tax Year and Payment Information
Tax Year Beginning and Ending
If the return is for a fiscal year rather than calendar year 2025, enter the beginning and ending dates of the corporation’s tax year, including the month, day, and year. The 2025 form applies to tax years ending on or after December 31, 2025, and before December 31, 2026. If the tax period falls outside this range, consult the instructions to determine the correct form.
Amount You Are Paying With This Return
Enter the amount of payment being submitted with the return. If the corporation is making a payment, ensure that the amount agrees with the accompanying payment or payment arrangement.
Step 1: Corporation Identification
Field A: Complete Legal Business Name
Enter the corporation’s full legal name. If the corporation’s name has changed, mark the name-change checkbox.
Field B: Mailing Address
Enter the corporation’s mailing address, including the applicable details:
- C/O, if correspondence should be directed to another person or department.
- Mailing address.
- City.
- State.
- ZIP code.
Use the address where the corporation should receive tax correspondence.
Field C: First or Final Return
Mark the First Return box if this is the corporation’s first return, as applicable.
Mark the Final Return box if this is the corporation’s final return. If filing a final return, enter the date of termination in month/day/year format.
Field D: Final Return Due to Sale of the Business
If the corporation is filing a final return because the business was sold, enter the date of sale in month/day/year format and the new owner’s FEIN.
Complete this field when the final return results from a business sale.
Field E: Business Classification
Mark the applicable box if the corporation is either of the following:
- Unitary filer (combined return): Select this option if the corporation files as a unitary business and is required to use the applicable combined-return procedures.
- Foreign insurer: Select this option if the corporation qualifies as a foreign insurer.
If either classification applies, review the instructions and the supporting-document requirements for the applicable schedules.
Field F: Federal Disclosure Forms
If the corporation completed either of the following federal documents, mark the applicable box and attach the required form:
- Federal Form 8886.
- Federal Schedule M-3, Part II, line 12.
Use the federal filing records to determine which document applies.
Field G: Apportionment Formulas
Mark the appropriate box or boxes for the corporation’s applicable apportionment formula. The form lists the following categories:
- Sales companies.
- Insurance companies.
- Transportation companies.
- Financial organizations.
- Federally regulated exchanges.
Consult the apportionment formula instructions to determine which classification applies to the corporation’s business activities.
Field H: Illinois Schedule UB
Mark this box if Illinois Schedule UB is attached to the return.
Field I: Subgroup Schedule
Mark this box if the Subgroup Schedule is attached.
Field J: Illinois Schedule 1299-D
Mark this box if Illinois Schedule 1299-D is attached. This schedule is associated with applicable income tax credit information.
Field K: Form IL-4562
Mark this box if Form IL-4562 is attached for Illinois special depreciation adjustments.
Field L: Illinois Schedule M
Mark this box if Illinois Schedule M, used for businesses, is attached to report applicable other additions or subtractions.
Field M: Schedule 80/20
Mark this box if Schedule 80/20 is attached for applicable related-party expense adjustments.
Field N: Federal Employer Identification Number
Enter the corporation’s FEIN. Verify the number against the corporation’s federal tax records.
Field O: Parent Corporation’s FEIN
If the corporation is a member of a group filing a federal consolidated return, enter the parent corporation’s FEIN.
Field P: NAICS Code
Enter the corporation’s North American Industry Classification System (NAICS) code. Use the applicable code for the corporation’s business activity and consult the instructions if needed.
Field Q: Corporate File or Charter Number
Enter the corporate file or charter number assigned by the Illinois Secretary of State.
Field R: Location of Accounting Records
Enter the city, state, and ZIP code where the corporation’s accounting records are maintained. Use the two-letter state abbreviation.
Field S: Business Income Election
If the corporation elects to treat all nonbusiness income as business income, mark this box. The form directs the corporation to enter zero on lines 24 and 32 when making this election.
Review the applicable instructions before selecting this option.
Field T: Accounting Method
Mark the box corresponding to the corporation’s accounting method:
- Cash.
- Accrual.
- Other.
If Other applies, provide the required explanation as directed by the instructions.
Field U: Discharge of Indebtedness Adjustment
If the corporation is making a discharge of indebtedness adjustment on Schedule NLD, Schedule UB/NLD, or line 36 of Form IL-1120, mark this box and attach federal Form 982.
Field V: Schedule INL
Mark this box if Schedule INL is attached.
Field W: Annualized Income on Form IL-2220
If the corporation annualized its income on Form IL-2220, mark this box and attach Form IL-2220.
Field X: Public Law 86-272 Protection
Mark this box if the corporation’s business activity is protected under Public Law 86-272. Consult the instructions to determine whether the protection applies.
Field Y: 52/53-Week Filer
Mark this box if the corporation uses a 52/53-week tax year.
Page 2: Step 2 — Figure Your Income or Loss
Enter whole-dollar amounts for the calculations in this section. Use the federal return and supporting Illinois tax documents to determine the applicable amounts.
Line 1: Federal Taxable Income
Enter federal taxable income from federal Form 1120, line 30. Attach a copy of the federal return, including the pages required by the supporting-document instructions.
Line 2: Net Operating Loss Deduction
Enter the net operating loss deduction from federal Form 1120, line 29a. The amount entered on this line cannot be negative.
Line 3: State, Municipal, and Other Interest Income
Enter the amount of state, municipal, and other interest income that was excluded from line 1.
Line 4: Illinois Income and Replacement Tax and Surcharge Deducted
Enter the amount of Illinois income tax, replacement tax, and surcharge deducted when calculating the federal taxable income reported on line 1.
Line 5: Illinois Special Depreciation Addition
Enter the applicable Illinois special depreciation addition. Attach Form IL-4562 and mark field K in Step 1.
Line 6: Related-Party Expenses Addition
Enter the related-party expense addition required for Illinois tax purposes. Attach Schedule 80/20 and mark field M in Step 1.
Line 7: Distributive Share of Additions
Enter the corporation’s distributive share of applicable additions reported through partnerships or other pass-through entities. Attach the relevant Schedules K-1-P or K-1-T.
Line 8: Other Additions
Enter other applicable additions not included on the preceding lines. Attach Schedule M and the required supporting information, and mark field L in Step 1.
Line 9: Total Income or Loss
Add the amounts reported on lines 1 through 8 as directed by the form.
Calculation:
Line 9 = Line 1 + Line 2 + Line 3 + Line 4 + Line 5 + Line 6 + Line 7 + Line 8
Enter the resulting income or loss amount. Ensure that the entries follow the applicable treatment of deductions and adjustments.
Step 3: Figure Your Base Income or Loss
This step identifies the subtractions used to determine Illinois base income or loss.
Line 10: Interest Income From U.S. Treasury and Other Exempt Federal Obligations
Enter the applicable interest income from U.S. Treasury obligations and other federally exempt obligations included in this section.
Line 11: River Edge Redevelopment Zone Dividend Subtraction
Enter the eligible dividend subtraction associated with a River Edge Redevelopment Zone. Attach Schedule 1299-B and the required supporting information.
Line 12: River Edge Redevelopment Zone Interest Subtraction
Enter the eligible interest subtraction associated with a River Edge Redevelopment Zone. Attach Schedule 1299-B.
Line 13: High Impact Business Dividend Subtraction
Enter the applicable dividend subtraction for a qualifying High Impact Business. Attach Schedule 1299-B.
Line 14: High Impact Business Interest Subtraction
Enter the applicable interest subtraction for a qualifying High Impact Business. Attach Schedule 1299-B.
Line 15: Contribution Subtraction
Enter the applicable contribution subtraction. Attach Schedule 1299-B and the required supporting information.
Line 16: Contributions to Certain Job Training Projects
Enter the applicable amount for contributions to qualifying job training projects. Consult the instructions to determine whether the contribution qualifies and how the amount should be calculated.
Line 17: Foreign Dividend Subtraction
Enter the applicable foreign dividend subtraction. Attach Illinois Schedule J and the relevant federal Form 1120 Schedule C or equivalent document.
Line 18: Illinois Special Depreciation Subtraction
Enter the applicable Illinois special depreciation subtraction. Attach Form IL-4562 and mark field K in Step 1.
Line 19: Related-Party Expenses Subtraction
Enter the applicable related-party expense subtraction. Attach Schedule 80/20 and mark field M in Step 1.
Line 20: Distributive Share of Subtractions
Enter the corporation’s distributive share of applicable subtractions from partnerships or other pass-through entities. Attach the relevant Schedules K-1-P or K-1-T.
Line 21: Other Subtractions
Enter other applicable Illinois subtractions not reported on the preceding lines. Attach Schedule M and the required supporting information, and mark field L in Step 1.
Line 22: Total Subtractions
Add the amounts reported on lines 10 through 21.
Calculation:
Line 22 = Line 10 + Line 11 + Line 12 + Line 13 + Line 14 + Line 15 + Line 16 + Line 17 + Line 18 + Line 19 + Line 20 + Line 21
Enter the total in the designated field.
Line 23: Base Income or Loss
Subtract line 22 from line 9.
Calculation:
Line 23 = Line 9 − Line 22
The result is the corporation’s base income or loss before the allocation procedures in Step 4.
Determine Whether Step 4 Is Required
Line A: Income Derived Entirely Within Illinois
If the amount on line 23 is derived entirely within Illinois, mark box A and enter the amount from line 23 on line 35 in Step 5.
When this option applies, leave Step 4, lines 24 through 34, blank.
A unitary filer must not select this option. The form directs unitary filers to select box B and complete Step 4.
Line B: Income Derived Partly Outside Illinois or Unitary Filer
If any portion of the amount on line 23 is derived outside Illinois, mark box B and complete all applicable lines in Step 4. A unitary filer must also select this box.
Do not leave lines 28 through 30 blank when completing Step 4. Follow the instructions for determining the corporation’s Illinois allocation.
Step 4: Figure Your Income Allocable to Illinois
Complete this step only if box B above line 24 is selected. The step separates nonbusiness income from business income and calculates the portion of business income allocated to Illinois.
Line 24: Nonbusiness Income or Loss
Enter the corporation’s nonbusiness income or loss. Attach Schedule NB.
Line 25: Business Income or Loss From Pass-Through Entities
Enter the applicable business income or loss included in line 23 from non-unitary partnerships, partnerships included on Schedule UB, S corporations, trusts, or estates. Consult the instructions and attach the relevant Schedules K-1-P or K-1-T.
Line 26: Total of Lines 24 and 25
Add lines 24 and 25.
Calculation:
Line 26 = Line 24 + Line 25
Line 27: Business Income or Loss
Subtract line 26 from line 23.
Calculation:
Line 27 = Line 23 − Line 26
This amount is used to determine the business income or loss subject to the apportionment calculation.
Line 28: Total Sales Everywhere
Enter the corporation’s total sales everywhere. The amount cannot be negative.
Line 29: Total Sales Inside Illinois
Enter the corporation’s total sales inside Illinois. The amount cannot be negative.
Line 30: Apportionment Factor
Divide line 29 by line 28 and round the result to six decimal places.
Calculation:
Line 30 = Line 29 ÷ Line 28
Use the resulting factor for the calculation on line 31.
Line 31: Business Income or Loss Apportionable to Illinois
Multiply line 27 by the apportionment factor on line 30.
Calculation:
Line 31 = Line 27 × Line 30
Enter the result in the designated field.
Line 32: Nonbusiness Income or Loss Allocable to Illinois
Enter the nonbusiness income or loss allocated to Illinois. Attach Schedule NB.
If the corporation made the business income election described in field S, follow the form’s instruction to enter zero on this line.
Line 33: Business Income or Loss Apportionable to Illinois From Pass-Through Entities
Enter the applicable business income or loss apportionable to Illinois from non-unitary partnerships, partnerships included on Schedule UB, S corporations, trusts, or estates.
Attach the applicable Schedules K-1-P or K-1-T and follow the instructions for the relevant entity type.
Line 34: Base Income or Loss Allocable to Illinois
Add lines 31, 32, and 33.
Calculation:
Line 34 = Line 31 + Line 32 + Line 33
Enter the resulting base income or loss allocated to Illinois. This amount is used on line 35 in Step 5.
Page 3: Step 5 — Figure Your Net Income
This step adjusts the corporation’s base income or loss and calculates the amount used for the tax calculations.
Line 35: Base Income or Net Loss
Enter the amount from line 23 in Step 3 if the corporation qualifies to skip Step 4. Otherwise, enter the amount from line 34 in Step 4.
Line 36: Discharge of Indebtedness Adjustment
Enter the applicable discharge of indebtedness adjustment. Attach federal Form 982 and mark field U in Step 1 when required.
Line 37: Adjusted Base Income or Net Loss
Add lines 35 and 36.
Calculation:
Line 37 = Line 35 + Line 36
Follow the instructions for determining the treatment of the adjustment.
Line 38: Illinois Net Loss Deduction
Enter the applicable Illinois net loss deduction. If line 37 is zero or negative, enter zero on this line.
Attach Schedule NLD or Schedule UB/NLD for unitary filers, as applicable.
If the corporation has merged losses, mark the designated checkbox and attach a detailed statement.
Line 39: Net Income
Subtract line 38 from line 37.
Calculation:
Line 39 = Line 37 − Line 38
Enter the result. This amount is used to calculate the replacement tax and income tax in the next two steps.
Step 6: Figure Your Replacement Tax After Credits
This step calculates the replacement tax before and after applicable investment credits.
Line 40: Replacement Tax
Multiply line 39 by 2.5%, or 0.025.
Calculation:
Line 40 = Line 39 × 0.025
Enter the calculated replacement tax amount.
Line 41: Recapture of Investment Credits
Enter the applicable investment credit recapture amount. Attach Schedule 4255.
Line 42: Replacement Tax Before Credits
Add lines 40 and 41.
Calculation:
Line 42 = Line 40 + Line 41
Line 43: Investment Credits
Enter the applicable investment credits. Attach Form IL-477 and any supporting documents required by its instructions.
Line 44: Replacement Tax After Credits
Subtract line 43 from line 42. If the result is negative, enter zero.
Calculation:
Line 44 = Line 42 − Line 43
Enter the resulting replacement tax after credits.
Step 7: Figure Your Income Tax After Credits
This step calculates the corporation’s income tax after applicable credits.
Line 45: Income Tax
Multiply line 39 by 7.0%, or 0.07.
Calculation:
Line 45 = Line 39 × 0.07
Enter the calculated income tax amount.
Line 46: Recapture of Investment Credits
Enter the applicable investment credit recapture amount. Attach Schedule 4255.
Line 47: Income Tax Before Credits
Add lines 45 and 46.
Calculation:
Line 47 = Line 45 + Line 46
Line 48: Income Tax Credits
Enter the applicable income tax credits. Attach Schedule 1299-D and the supporting information required by its instructions, or Schedule 1299-I, as applicable.
If Schedule 1299-D is attached, mark field J in Step 1.
Line 49: Income Tax After Credits
Subtract line 48 from line 47. If the result is negative, enter zero.
Calculation:
Line 49 = Line 47 − Line 48
Enter the resulting income tax after credits.
Step 8: Figure Your Refund or Balance Due
This step combines the corporation’s net taxes, surcharges, penalties, and payments to determine whether it owes additional tax or has an overpayment.
Calculate Net Replacement Tax and Net Income Tax
Line 50: Replacement Tax Before Reductions
Enter the amount from line 44.
Line 51: Foreign Insurer Replacement Tax Reduction
Enter the applicable foreign insurer replacement tax reduction. Attach Schedule INS or Schedule UB/INS for unitary filers, as applicable.
Line 52: Net Replacement Tax
Subtract line 51 from line 50.
Calculation:
Line 52 = Line 50 − Line 51
Line 53: Income Tax Before Reductions
Enter the amount from line 49.
Line 54: Foreign Insurer Income Tax Reduction
Enter the applicable foreign insurer income tax reduction. Attach Schedule INS or Schedule UB/INS for unitary filers, as applicable.
Line 55: Net Income Tax
Subtract line 54 from line 53.
Calculation:
Line 55 = Line 53 − Line 54
Surcharges and Total Tax Liability
Line 56: Compassionate Use of Medical Cannabis Program Act Surcharge
Enter the applicable surcharge under the Compassionate Use of Medical Cannabis Program Act. Consult the instructions to determine whether the surcharge applies and how to calculate it.
Line 57: Sale of Assets by Gaming Licensee Surcharge
Enter the applicable surcharge associated with the sale of assets by a gaming licensee, if required.
Line 58: Total Net Income and Replacement Taxes and Surcharges
Add lines 52, 55, 56, and 57.
Calculation:
Line 58 = Line 52 + Line 55 + Line 56 + Line 57
Line 59: Underpayment of Estimated Tax Penalty
Enter the applicable penalty for underpayment of estimated tax. Attach Form IL-2220.
If the corporation annualized its income on Form IL-2220, mark field W in Step 1.
Line 60: Total Taxes, Surcharges, and Penalty
Add lines 58 and 59.
Calculation:
Line 60 = Line 58 + Line 59
This amount represents the total taxes, surcharges, and penalty before payments are applied.
Report Payments and Withholding
Line 61a: Credits From Previous Overpayments
Enter any applicable credits carried forward from previous overpayments.
Line 61b: Total Payments Made Before Filing
Enter the total payments made before the date the return is filed. Use the applicable payment records.
Line 61c: Pass-Through Withholding Reported to the Corporation
Enter the pass-through withholding reported to the corporation on Schedules K-1-P or K-1-T.
Attach all Schedules K-1-P and K-1-T received that show pass-through withholding.
Line 61d: Pass-Through Entity Tax Credit Reported to the Corporation
Enter the applicable pass-through entity tax credit reported on Schedules K-1-P or K-1-T.
Attach all Schedules K-1-P and K-1-T received that show this credit.
Line 61e: Illinois Income Tax Withholding
Enter applicable Illinois income tax withholding. Attach copies of all Forms W-2G required for this entry.
Line 62: Total Payments
Add lines 61a through 61e.
Calculation:
Line 62 = Line 61a + Line 61b + Line 61c + Line 61d + Line 61e
Enter the total payments in the designated field.
Determine the Overpayment, Refund, or Tax Due
Line 63: Overpayment
If line 62 is greater than line 60, subtract line 60 from line 62.
Calculation:
Line 63 = Line 62 − Line 60
Enter the result when payments exceed the total taxes, surcharges, and penalty.
Line 64: Amount to Be Credited Forward
Enter the portion of the overpayment to be credited forward, following the applicable instructions.
If the credit carryforward is going to a different FEIN, mark the designated checkbox and attach a detailed statement.
Line 65: Refund
Subtract line 64 from line 63.
Calculation:
Line 65 = Line 63 − Line 64
Enter the amount to be refunded after accounting for the amount credited forward.
Line 66: Direct Deposit Information
Complete this section if the corporation is requesting a refund by direct deposit.
Enter:
- Routing number: The bank routing number for the account receiving the refund.
- Account number: The account number for the receiving account.
- Account type: Mark Checking or Savings, as applicable.
Verify the account information carefully before submitting the return.
Line 67: Tax Due
If line 60 is greater than line 62, subtract line 62 from line 60.
Calculation:
Line 67 = Line 60 − Line 62
Enter the amount owed. If tax is due, follow the payment instructions at the top of page 1.
Step 9: Sign the Return
The corporation must complete the signature section before filing the return.
Authorized Officer’s Signature
The authorized officer must sign the return to confirm, under penalties of perjury, that the return has been examined and is true, correct, and complete to the best of the officer’s knowledge.
Date
Enter the signature date in month/day/year format.
Title
Enter the title or position of the authorized officer signing the return.
Phone Number
Enter the telephone number where the corporation or authorized officer can be contacted.
Permission to Discuss the Return With the Paid Preparer
Mark the checkbox if the Illinois Department of Revenue may discuss the return with the paid preparer identified in this section.
Paid Preparer Information
Complete this section when a paid preparer is involved.
Paid Preparer’s Name
Enter the printed or typed name of the person who prepared the return.
Paid Preparer’s Signature
Enter the preparer’s signature in the designated space.
Paid Preparer’s Date
Enter the date the preparer signed the return in month/day/year format.
Self-Employed Preparer Checkbox
Mark this box if the paid preparer is self-employed.
Paid Preparer’s PTIN
Enter the paid preparer’s Preparer Tax Identification Number (PTIN).
Firm’s Name
Enter the name of the preparer’s firm, if applicable.
Firm’s FEIN
Enter the firm’s federal employer identification number.
Firm’s Address
Enter the preparer firm’s address.
Firm’s Phone Number
Enter the firm’s telephone number.
Review the completed signature and preparer information before filing.
Page 4: Supporting Documents and Attachments
Form IL-1120 includes a supporting-document checklist that identifies the additional forms required for various entries. Attach the applicable documents to the return. The form warns that failing to provide required documents may result in the corresponding line item being disallowed.
Federal Return and Corporation Classification Documents
Federal Form 1120
Attach federal Form 1120, pages 1 through 6, or an equivalent return.
Step 1, Field E: Unitary Filer
Attach Schedule UB and the Subgroup Schedule, as applicable. Mark field H or field I in Step 1, as directed.
Step 1, Field E: Foreign Insurer
Attach Schedule INS.
Step 1, Field E: Unitary Filer and Foreign Insurer
Attach the Schedule UB/Subgroup Schedule and Schedule UB/INS, as applicable. Mark field H or field I as directed.
Step 1, Field F: Federal Disclosure Forms
Attach federal Form 8886 or federal Schedule M-3, as applicable.
Step 1, Field U: Discharge of Indebtedness Adjustment
Attach federal Form 982.
Step 1, Field V: Schedule INL
Attach Schedule INL.
Step 1, Field W: Annualized Income
Attach Form IL-2220.
Depreciation, Related-Party Expenses, and Other Adjustments
Lines 5 and 18: Illinois Special Depreciation
Attach Form IL-4562 for the special depreciation addition or subtraction. Mark field K in Step 1.
Lines 6 and 19: Related-Party Expenses
Attach Schedule 80/20 for the applicable addition or subtraction. Mark field M in Step 1.
Lines 7 and 20: Distributive Share of Additions and Subtractions
Attach the applicable Schedules K-1-P or K-1-T.
Lines 8 and 21: Other Additions and Subtractions
Attach Schedule M and any supporting documents required by its instructions. Mark field L in Step 1.
Lines 11 Through 15: Applicable Subtractions
Attach Schedule 1299-B and the supporting documents required by its instructions for the following items:
- River Edge Redevelopment Zone dividend subtraction.
- River Edge Redevelopment Zone interest subtraction.
- High Impact Business dividend subtraction.
- High Impact Business interest subtraction.
- Contribution subtraction.
Line 17: Foreign Dividend Subtraction
Attach Illinois Schedule J and federal Form 1120, Schedule C, or an equivalent document.
Income Allocation Documents
Lines 24 and 32: Nonbusiness Income or Loss
Attach Schedule NB for nonbusiness income or loss and nonbusiness income or loss allocated to Illinois.
Lines 25 and 33: Business Income or Loss From Pass-Through Entities
Attach the applicable Schedules K-1-P or K-1-T for income or loss from non-unitary partnerships, partnerships included on Schedule UB, S corporations, trusts, or estates.
Net Loss and Tax Credit Documents
Line 36: Discharge of Indebtedness Adjustment
Attach federal Form 982 and mark field U in Step 1, as applicable.
Line 38: Illinois Net Loss Deduction
Attach Schedule NLD or Schedule UB/NLD for unitary filers, as applicable.
Lines 41 and 46: Recapture of Investment Credits
Attach Schedule 4255.
Line 43: Investment Credits
Attach Form IL-477 and any supporting documents required by its instructions.
Line 48: Income Tax Credits
Attach Schedule 1299-D and the required supporting information identified in its instructions, or Schedule 1299-I, as applicable. Mark field J in Step 1 when Schedule 1299-D is attached.
Lines 51 and 54: Foreign Insurer Tax Reduction
Attach Schedule INS or Schedule UB/INS for unitary filers, as applicable. Mark field E in Step 1.
Line 59: Underpayment of Estimated Tax Penalty
Attach Form IL-2220. If income was annualized using Form IL-2220, follow the instructions for marking field W in Step 1.
Payment and Withholding Documents
Line 61c: Pass-Through Withholding
Attach all Schedules K-1-P and K-1-T received that report pass-through withholding.
Line 61d: Pass-Through Entity Tax Credit
Attach all Schedules K-1-P and K-1-T received that report the pass-through entity tax credit.
Line 61e: Illinois Income Tax Withholding
Attach copies of all Forms W-2G supporting the withholding reported on this line.
Before submitting the return, check that every required attachment is included and that the relevant checkboxes on page 1 have been marked.
Common Mistakes to Avoid When Filing Form IL-1120
- Using the wrong tax-year form: Confirm that the corporation’s tax year falls within the period covered by the 2025 form.
- Entering an incorrect FEIN: Verify the corporation’s identification number and, when applicable, the parent corporation’s FEIN.
- Forgetting required attachments: Include the federal return and all supporting schedules required for the lines completed.
- Selecting the wrong income allocation option: Review whether income is derived entirely within Illinois or whether Step 4 must be completed.
- Leaving required apportionment fields blank: If Step 4 applies, complete lines 28 through 30 as directed.
- Using the wrong apportionment factor: Divide Illinois sales by total sales everywhere and round the result to six decimal places.
- Confusing additions and subtractions: Report each adjustment on the appropriate line and attach its supporting schedule.
- Claiming unsupported tax credits: Use the applicable credit forms and required supporting records.
- Entering incorrect tax calculations: Verify the replacement tax calculation at 2.5%, the income tax calculation at 7.0%, and the credit reductions.
- Omitting estimated tax penalties when applicable: Review whether Form IL-2220 is required.
- Reporting payments incorrectly: Check prior overpayment credits, payments, withholding, and pass-through entity tax credits before calculating the final balance.
- Failing to complete the signature section: Ensure the authorized officer signs and dates the return.
- Sending payment to the wrong address: Use the mailing address appropriate to whether payment is enclosed and include Form IL-1120-V when mailing payment.
Final Review Before Filing
Use this checklist to review the completed return before submitting it to the Illinois Department of Revenue.
- The tax year beginning and ending dates are correct.
- The payment amount at the top of page 1 is accurate, if applicable.
- The corporation’s legal name and mailing address are correct.
- The first-return, final-return, or business-sale fields are completed when applicable.
- The corporation’s classification, NAICS code, charter number, and accounting method are correct.
- The corporation’s FEIN and parent FEIN, if applicable, have been checked.
- The correct apportionment formula has been selected.
- All applicable checkboxes in fields H through Y have been reviewed.
- Federal taxable income and the other entries on lines 1 through 9 agree with the supporting records.
- The subtractions on lines 10 through 21 have been entered correctly.
- Lines 22 and 23 have been calculated correctly.
- The correct choice has been made between completing Step 4 and transferring line 23 directly to line 35.
- If Step 4 applies, lines 24 through 34 are complete and the apportionment factor on line 30 is calculated correctly.
- Lines 35 through 39 reflect the correct net income calculation and applicable net loss deduction.
- Replacement tax on lines 40 through 44 has been calculated correctly.
- Income tax on lines 45 through 49 has been calculated correctly.
- Foreign insurer tax reductions and applicable surcharges have been reported correctly.
- Line 59 includes the applicable estimated tax underpayment penalty, if required.
- Lines 61a through 61e include all applicable payments, credits, and withholding.
- Line 62 reflects the correct total payments.
- Lines 63 through 65 correctly determine any overpayment, carryforward, and refund.
- Direct deposit information on line 66 is accurate, if applicable.
- Line 67 correctly shows the balance due, if any.
- The authorized officer has signed and dated the return.
- The paid preparer section is complete when applicable.
- Federal Form 1120 and all other required supporting documents are attached.
- The correct mailing address and payment method have been selected.
- The filing deadline has been confirmed using the applicable instructions.
Completing Form IL-1120 carefully helps ensure that the corporation reports its income, Illinois adjustments, taxes, credits, and payments accurately. Review the calculations and supporting documents before filing, and use the applicable Illinois instructions whenever a line depends on specific eligibility requirements or tax treatment.