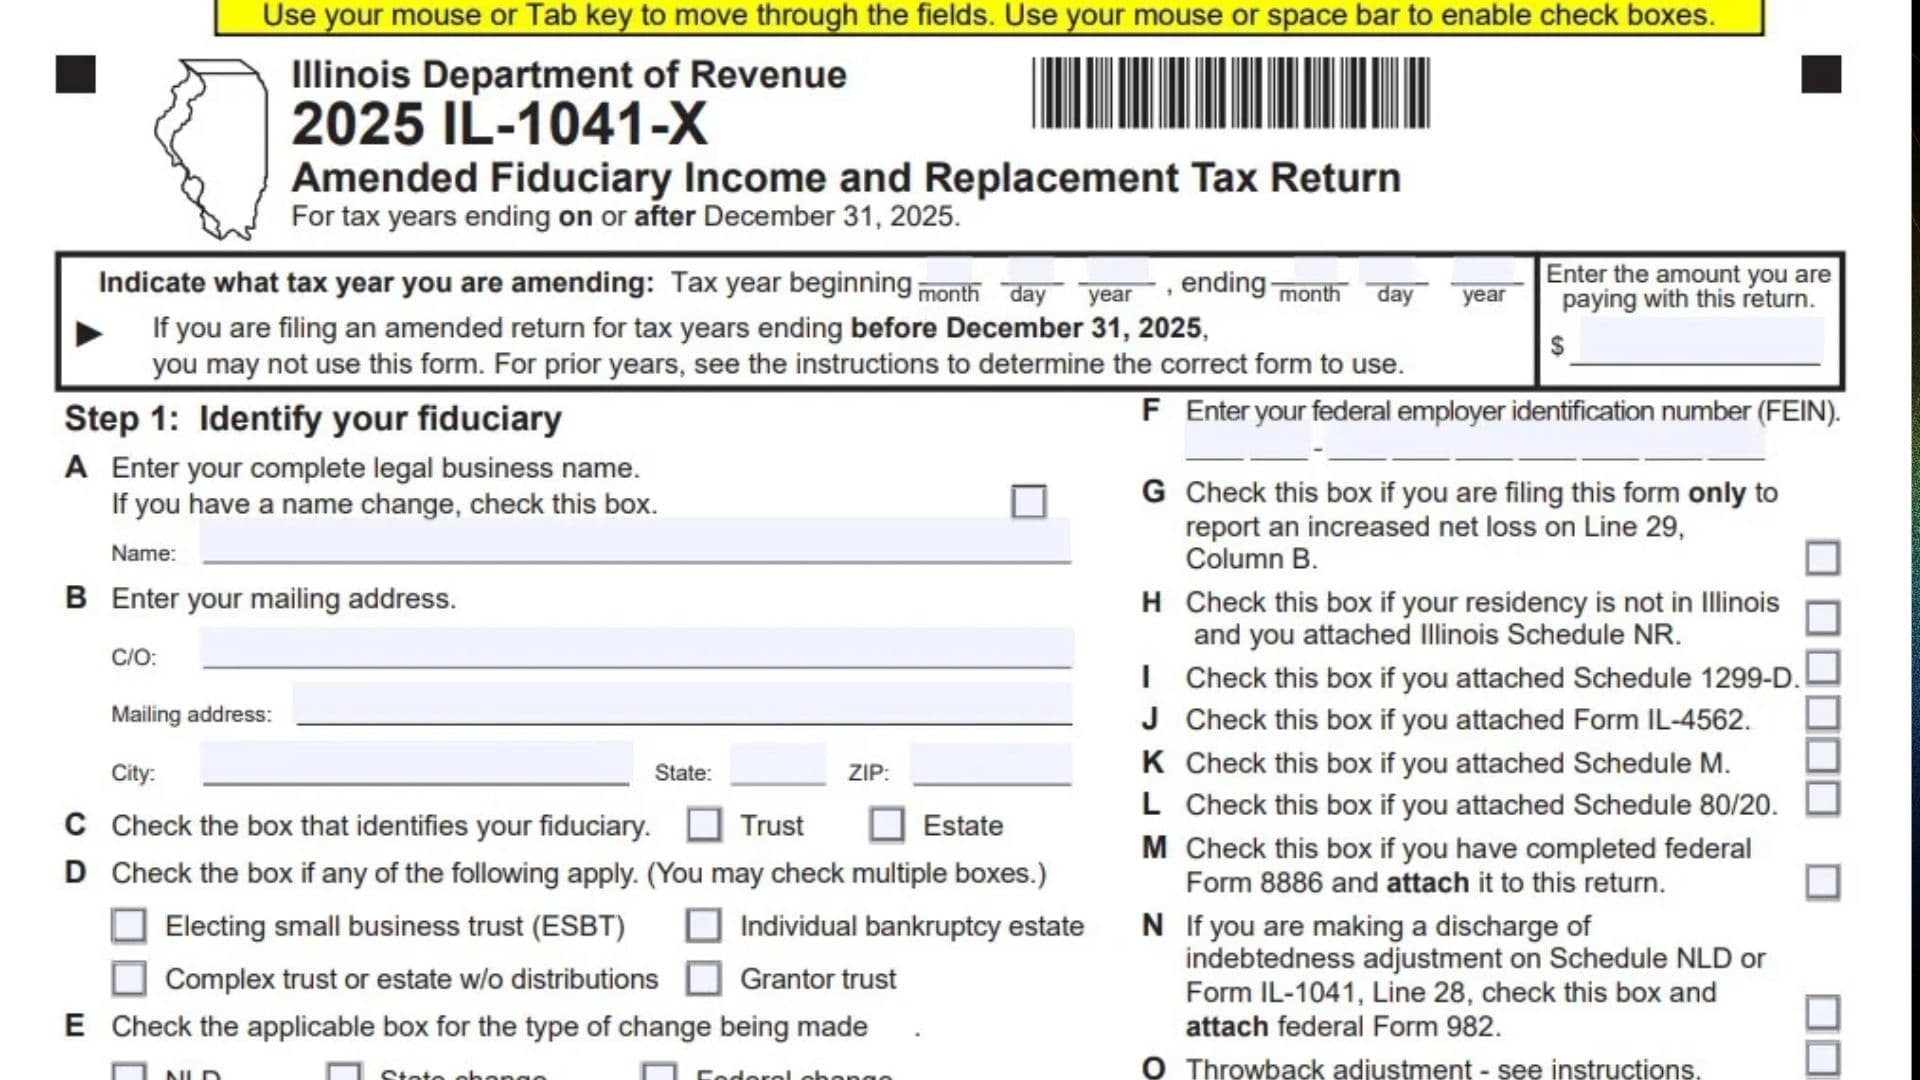
Illinois Form IL-1041-X, officially known as the Amended Fiduciary Income and Replacement Tax Return, is a tax form issued by the Illinois Department of Revenue for trusts and estates that need to correct a previously filed Illinois fiduciary income and replacement tax return. The form allows fiduciaries to report corrected income, losses, deductions, exemptions, tax credits, withholding, payments, and other information affecting the original return. It is designed for tax years ending on or after December 31, 2025. Taxpayers amending returns for earlier tax years cannot use this version and must consult the applicable instructions to determine which form is required. The return collects information about the trust or estate, its federal employer identification number (FEIN), beneficiaries, federal taxable income, Illinois additions and subtractions, base income or loss, net income, replacement tax, income tax, credits, and payments. It also includes sections for identifying the reason for the amendment, explaining changes, calculating an overpayment or balance due, and providing the required fiduciary and paid preparer signatures. An important feature of Form IL-1041-X is its comparison of previously reported or adjusted amounts with corrected amounts. This allows the Illinois Department of Revenue to identify the changes being made to the original return. The form also distinguishes between amounts allocated to beneficiaries and amounts attributable to the fiduciary. Depending on the circumstances, supporting documents such as federal Form 1041, Schedule NR, Schedule M, Schedule 80/20, Schedule 1299-D, Schedule D, Schedule NLD, Form IL-4562, Schedule CR, Schedule 4255, and other applicable documents may be required. Completing the form accurately is important because the corrected information determines the trust’s or estate’s Illinois tax liability, replacement tax, beneficiary withholding obligations, available credits, refunds, and outstanding balances. Incorrect calculations, missing schedules, incomplete beneficiary information, or missing signatures can delay processing or result in additional correspondence from the Illinois Department of Revenue.
How To File Form IL-1041-X
Form IL-1041-X must be completed by the fiduciary responsible for the trust or estate’s Illinois income and replacement tax return. The completed form is submitted to the Illinois Department of Revenue with the required supporting schedules and documents.
Who Should File Form IL-1041-X?
This form is intended for trusts and estates that need to amend a previously filed Illinois fiduciary income and replacement tax return.
The form provides separate identification options for:
- Trusts.
- Estates.
- Electing small business trusts (ESBTs).
- Individual bankruptcy estates.
- Complex trusts or estates without distributions.
- Grantor trusts.
Select the classifications that accurately describe the fiduciary filing the amended return.
Applicable Tax Years
The 2025 version of Form IL-1041-X applies to tax years ending on or after December 31, 2025.
If you need to amend a return for a tax year ending before December 31, 2025, you cannot use this version. Consult the instructions for the relevant prior year to determine the correct form.
Where To Mail Form IL-1041-X
The form provides the following mailing address:
Illinois Department of Revenue
P.O. Box 19016
Springfield, IL 62794-9016
Mail the completed amended return with the applicable supporting documents.
Payment Instructions
If the amended return shows an amount due on Line 64, complete Form IL-1041-X-V, the payment voucher.
The form provides the following payment instructions:
- Write the trust’s or estate’s FEIN on the check or money order.
- Include the tax year ending date.
- Write “IL-1041-X-V” on the payment.
- Make the check or money order payable to “Illinois Department of Revenue.”
- Attach the completed payment voucher and payment to the first page of Form IL-1041-X.
- Enter the payment amount in the designated payment field at the top of Page 1.
The form also states that the department will send a bill for any additional penalty and interest.
Documents And Information To Prepare
Before completing Form IL-1041-X, gather the following:
- The previously filed Illinois Form IL-1041.
- Federal Form 1041.
- The trust’s or estate’s legal name.
- Federal employer identification number (FEIN).
- Mailing address.
- Original and corrected income information.
- Beneficiary income allocation information.
- Federal net operating loss information.
- Illinois additions and subtractions.
- Information about exemptions and deductions.
- Applicable tax credit information.
- Payment and withholding records.
- Federal amendment or finalization documents, if applicable.
- Supporting schedules required for the changes.
- Beneficiary information, including names, addresses, and SSNs or FEINs.
- The reason for filing the amended return.
- A detailed explanation of the changes.
- Fiduciary signature and contact information.
- Paid preparer information, if applicable.
If the return involves pass-through withholding or beneficiary distributions, also prepare the applicable Schedule K-1-T, Schedule K-1-T(3), and Schedule D information.
How To Complete Form IL-1041-X
The 2025 Illinois Form IL-1041-X contains eight main steps across its first three pages. The attached form also includes Schedule D, which provides additional beneficiary information and pass-through withholding calculations.
The following sections explain how to complete each part.
Step 1: Identify Your Fiduciary
Step 1 identifies the trust or estate filing the amended return and collects information about the type of fiduciary, the reason for the amendment, and applicable supporting documents.
The section contains fields A through Q.
Tax Year Being Amended
Enter the beginning and ending dates of the tax year being amended.
Provide the month, day, and year for both dates.
Make sure the tax year corresponds to the previously filed return.
Payment Amount
At the top of Page 1, enter the amount you are paying with the amended return.
If you owe additional tax, use the amount of payment being submitted with the return.
Fiduciary Identification
Box A: Complete Legal Business Name
Enter the complete legal name of the trust or estate.
Use the official legal name associated with the fiduciary tax return.
If the name has changed, check the name-change box provided in this section.
Box B: Mailing Address
Enter the mailing address of the trust or estate.
The form provides the following fields:
- C/O: Enter the care-of name or attention line, if applicable.
- Mailing Address: Enter the complete street or mailing address.
- City: Enter the city.
- State: Enter the state abbreviation.
- ZIP: Enter the applicable ZIP code.
Make sure the address is complete so that correspondence from the Illinois Department of Revenue can reach the fiduciary.
Box C: Type Of Fiduciary
Select the checkbox that identifies the type of fiduciary filing the return.
The available options are:
- Trust: Select this option when the amended return is being filed for a trust.
- Estate: Select this option when the amended return is being filed for an estate.
Choose the classification that applies to the entity.
Box D: Additional Fiduciary Classification
Check all applicable boxes that describe the trust or estate.
The form provides four options:
- Electing Small Business Trust (ESBT): Select this option if the trust is classified as an electing small business trust.
- Individual Bankruptcy Estate: Select this option if the return relates to an individual bankruptcy estate.
- Complex Trust Or Estate Without Distributions: Select this option if the trust or estate falls within this classification.
- Grantor Trust: Select this option if the fiduciary is filing for a grantor trust.
You may select more than one box when applicable.
Box E: Type Of Change Being Made
Select the option that identifies the reason for filing the amended return.
The form provides three choices:
- NLD: Select this option when the amendment involves a net loss deduction adjustment.
- State Change: Select this option when the amendment is based on a change to the Illinois state return.
- Federal Change: Select this option when the amendment results from a change to the federal return.
If you select Federal Change, indicate the applicable status:
- Partial Agreed: Select this option when the federal change has been partially agreed upon.
- Finalized: Select this option when the federal change has been finalized.
Federal Change Finalization Date
If you are reporting a federal change, enter the date the change was finalized.
Attach the applicable federal finalization documentation as instructed on the form.
Box F: Federal Employer Identification Number (FEIN)
Enter the complete federal employer identification number assigned to the trust or estate.
Check the number against the entity’s federal tax records.
Do not enter an individual’s Social Security number in this field.
Additional Filing Information
Box G: Increased Net Loss On Line 29, Column B
Check this box if you are filing the amended return only to report an increased net loss on Line 29, Column B.
This checkbox specifically identifies amendments limited to that type of net loss adjustment.
Box H: Nonresident Status
Check this box if the fiduciary’s residency is outside Illinois and you have attached Illinois Schedule NR.
Make sure Schedule NR is included when this option applies.
Box I: Schedule 1299-D Attached
Check this box if you are attaching Schedule 1299-D to the amended return.
Box J: Form IL-4562 Attached
Check this box if Form IL-4562 is included with the return.
Box K: Schedule M Attached
Check this box if you have attached Schedule M.
Box L: Schedule 80/20 Attached
Check this box if Schedule 80/20 is included with the amended return.
Box M: Federal Form 8886
Check this box if you have completed federal Form 8886 and are attaching it to the Illinois amended return.
Box N: Discharge Of Indebtedness Adjustment
Check this box if you are making a discharge of indebtedness adjustment on Schedule NLD or Form IL-1041, Line 28.
Attach federal Form 982 as required.
Box O: Throwback Adjustment
Check this box if a throwback adjustment applies to the amended return.
Consult the applicable instructions to determine how this adjustment should be calculated.
Box P: Double Throwback Adjustment
Check this box if a double throwback adjustment applies.
Follow the applicable instructions for the required calculation and reporting.
Box Q: 52/53-Week Filer
Check this box if the trust or estate uses a 52/53-week tax year rather than a standard calendar-year or fiscal-year reporting period.
Explanation Of Changes
Explain The Changes On This Return
Use the large explanation area in Step 1 to describe why you are filing the amended return.
Clearly explain the changes being made to the previously reported information.
Include enough detail to identify the affected income, deductions, credits, losses, or other tax items.
If the explanation does not fit in the available space, attach a separate sheet.
Make sure the additional statement clearly identifies the trust or estate and the tax year being amended.
Payment And Form IL-1041-X-V Attachment Area
The first page also provides a designated area for attaching the payment and Form IL-1041-X-V.
If you owe tax and are submitting payment, attach the payment voucher and check or money order in the indicated area.
Step 2: Figure Your Income Or Loss
Step 2 calculates the trust’s or estate’s total income or loss using federal taxable income and applicable Illinois additions.
An important feature of this section is the comparison between previously reported amounts and corrected amounts.
Understanding Columns A And B
The form provides two main comparison columns:
- Column A: As Most Recently Reported Or Adjusted — Enter the amounts from the most recently filed or adjusted return.
- Column B: Corrected Amount — Enter the corrected figures being reported on the amended return.
Each column distinguishes between:
- Beneficiaries: Amounts allocated to beneficiaries.
- Fiduciary: Amounts attributable to the fiduciary.
Use whole dollars only.
The corrected figures should reflect the changes being made to the original return.
Line 1: Federal Taxable Income
Enter federal taxable income from Line 23 of federal Form 1041.
Report the applicable beneficiary and fiduciary amounts in the designated columns.
Enter the previously reported or adjusted figures in Column A and the corrected amounts in Column B.
Line 2: Federal Net Operating Loss Deduction
Enter the federal net operating loss deduction from Line 15b of federal Form 1041.
The amount cannot be negative.
Separate beneficiary and fiduciary amounts where applicable.
Line 3: Taxable Income Of ESBT
Enter the taxable income of an electing small business trust (ESBT), if required.
Use the applicable information for the trust and report the amounts in the appropriate columns.
Line 4: Exemption Claimed On Federal Form 1041
Enter the exemption amount claimed on federal Form 1041.
Report the applicable amount in the beneficiary or fiduciary column.
Line 5: Illinois Income And Replacement Tax And Surcharge Deducted In Arriving At Line 1
Enter the Illinois income tax, replacement tax, and surcharge amounts deducted when calculating the federal taxable income reported on Line 1.
The form divides this information into:
- Line 5a: Beneficiary amount.
- Line 5b: Fiduciary amount.
Enter the corresponding previously reported and corrected figures.
Line 6: State, Municipal, And Other Interest Income Excluded From Line 1
Enter state, municipal, and other interest income that was excluded from the federal taxable income reported on Line 1.
The form provides:
- Line 6a: Beneficiary amount.
- Line 6b: Fiduciary amount.
Report the applicable amounts in both comparison columns.
Line 7: Illinois Special Depreciation Addition
Enter the applicable Illinois special depreciation addition.
Calculate the amount using Form IL-4562.
The form divides the amount into:
- Line 7a: Beneficiary amount.
- Line 7b: Fiduciary amount.
Attach Form IL-4562 to support the calculation.
Line 8: Related-Party Expenses Addition
Enter the applicable addition for related-party expenses.
Calculate the amount using Schedule 80/20.
The form provides:
- Line 8a: Beneficiary amount.
- Line 8b: Fiduciary amount.
Attach Schedule 80/20.
Line 9: Distributive Share Of Additions
Enter the distributive share of Illinois additions allocated to beneficiaries and the fiduciary.
Use the applicable Schedule K-1-P or Schedule K-1-T information.
The form provides:
- Line 9a: Beneficiary amount.
- Line 9b: Fiduciary amount.
Attach the applicable K-1 schedules.
Line 10: Other Additions
Enter other applicable Illinois income additions.
Calculate the amount using Schedule M for businesses.
The form provides:
- Line 10a: Beneficiary amount.
- Line 10b: Fiduciary amount.
Attach Schedule M.
Line 11: Total Income Or Loss
Calculate total income or loss by adding Lines 1 through 4 and Lines 5b through 10b.
The calculation is:
Lines 1 + 2 + 3 + 4 + 5b + 6b + 7b + 8b + 9b + 10b = Line 11.
Complete the calculation using the appropriate previously reported or corrected figures.
Enter the resulting total income or loss.
Step 3: Figure Your Base Income Or Loss
Step 3 identifies the applicable Illinois subtractions and adjustments used to calculate the trust’s or estate’s base income or loss.
As in Step 2, the form compares previously reported or adjusted figures with corrected amounts and separates beneficiary and fiduciary information where applicable.
Line 12: Amounts From Line 11
Transfer the total income or loss from Line 11 to Line 12.
Use the corresponding amounts for the beneficiary and fiduciary columns.
Complete both the previously reported and corrected sections.
Line 13: August 1, 1969, Valuation Limitation Amount
Enter the applicable August 1, 1969, valuation limitation amount.
Calculate the amount using Schedule F.
The form provides:
- Line 13a: Beneficiary amount.
- Line 13b: Fiduciary amount.
Attach Schedule F.
Line 14: Payments From Certain Retirement Plans
Enter applicable payments from certain retirement plans.
The form separates the amounts into:
- Line 14a: Beneficiary amount.
- Line 14b: Fiduciary amount.
Report the applicable amounts in the previously reported and corrected columns.
Line 15: Interest Income From U.S. Treasury And Other Exempt Federal Obligations
Enter interest income from U.S. Treasury obligations and other qualifying federal obligations that is eligible for the subtraction.
The form provides:
- Line 15a: Beneficiary amount.
- Line 15b: Fiduciary amount.
Line 16: Retirement Payments To Retired Partners
Enter applicable retirement payments made to retired partners.
Separate the amounts between:
- Line 16a: Beneficiary amount.
- Line 16b: Fiduciary amount.
Line 17: River Edge Redevelopment Zone Dividend Subtraction
Enter the applicable dividend subtraction associated with the River Edge Redevelopment Zone.
Calculate the amount using Schedule 1299-B.
The form provides:
- Line 17a: Beneficiary amount.
- Line 17b: Fiduciary amount.
Attach Schedule 1299-B.
Line 18: High Impact Business Dividend Subtraction
Enter the applicable High Impact Business dividend subtraction.
Calculate the amount using Schedule 1299-B.
The form provides:
- Line 18a: Beneficiary amount.
- Line 18b: Fiduciary amount.
Attach Schedule 1299-B.
Line 19: Contributions To Certain Job Training Projects
Enter the applicable contributions to qualifying job training projects.
Follow the applicable instructions to determine the amount.
The form provides:
- Line 19a: Beneficiary amount.
- Line 19b: Fiduciary amount.
Line 20: Illinois Special Depreciation Subtraction
Enter the applicable Illinois special depreciation subtraction.
Calculate the amount using Form IL-4562.
The form provides:
- Line 20a: Beneficiary amount.
- Line 20b: Fiduciary amount.
Attach Form IL-4562.
Line 21: Related-Party Expenses Subtraction
Enter the applicable subtraction for related-party expenses.
Calculate the amount using Schedule 80/20.
The form provides:
- Line 21a: Beneficiary amount.
- Line 21b: Fiduciary amount.
Attach Schedule 80/20.
Line 22: Distributive Share Of Subtractions
Enter the distributive share of applicable Illinois subtractions.
Use Schedule K-1-P or Schedule K-1-T to determine the amounts.
The form provides:
- Line 22a: Beneficiary amount.
- Line 22b: Fiduciary amount.
Attach the applicable K-1 schedules.
Line 23: ESBT Loss Amount
Enter the applicable electing small business trust (ESBT) loss amount.
The form provides separate fields for the beneficiary and fiduciary portions.
The beneficiary field is shaded on the form, while the fiduciary amount is entered on Line 23b.
Complete the applicable amount based on the ESBT information.
Line 24: Other Subtractions
Enter other applicable Illinois income subtractions.
Calculate the amount using Schedule M.
The form provides:
- Line 24a: Beneficiary amount.
- Line 24b: Fiduciary amount.
Attach Schedule M.
Line 25: Total Subtractions
Add the applicable subtraction amounts from Lines 13b through 24b.
The calculation is:
Lines 13b + 14b + 15b + 16b + 17b + 18b + 19b + 20b + 21b + 22b + 23b + 24b = Line 25.
Use the corresponding figures for the previously reported and corrected amounts.
Follow the applicable instructions when determining the amounts included in this calculation.
Line 26: Base Income Or Loss
Subtract Line 25 from Line 12.
The calculation is:
Line 12 − Line 25 = Line 26.
Enter the resulting base income or loss.
Nonresident Notice
If the fiduciary is a nonresident of Illinois, complete Schedule NR.
Otherwise, continue to Step 4.
Step 4: Figure Your Net Income
Step 4 calculates the trust’s or estate’s adjusted base income and Illinois net income after applicable adjustments and deductions.
Line 27: Base Income Or Net Loss
The amount entered depends on residency status.
- Residents: Enter the amount from Line 26.
- Nonresidents: Enter the amount from Schedule NR, Line 51.
Nonresidents must use the applicable Schedule NR amount.
Line 28: Discharge Of Indebtedness Adjustment
Enter the applicable discharge of indebtedness adjustment.
Attach federal Form 982.
If the adjustment applies, also check Box N in Step 1.
Line 29: Adjusted Base Income Or Net Loss
Add Lines 27 and 28.
The calculation is:
Line 27 + Line 28 = Line 29.
Enter the resulting adjusted base income or net loss.
This line is also important when reporting an increased net loss through Box G in Step 1.
Line 30: Illinois Net Loss Deduction
Enter the applicable Illinois net loss deduction calculated using Schedule NLD.
Attach Schedule NLD.
If Line 29 is zero or a negative amount, enter zero on Line 30.
Line 31: Standard Exemption
The method for completing this line depends on residency status.
- Residents: Determine the applicable standard exemption using the official instructions before completing this line.
- Nonresidents: Enter the amount from Schedule NR, Line 54.
Use the appropriate amount for the fiduciary’s residency classification.
Line 32: Total Deductions
Add Lines 30 and 31.
The calculation is:
Line 30 + Line 31 = Line 32.
Enter the combined amount.
Line 33: Net Income
Subtract Line 32 from Line 29.
The calculation is:
Line 29 − Line 32 = Line 33.
If the resulting amount is negative, enter zero.
The amount on Line 33 is used in the following tax calculations.
Step 5: Figure Your Net Replacement Tax
Step 5 calculates replacement tax for trusts only.
Important: Estates do not complete Step 5. Estates proceed directly to Step 6.
Line 34: Replacement Tax
Multiply Line 33 by 1.5% (0.015).
The calculation is:
Line 33 × 0.015 = Line 34.
Enter the resulting replacement tax.
Line 35: Recapture Of Investment Credits
Enter the applicable recapture of investment credits.
Calculate the amount using Schedule 4255.
Attach Schedule 4255.
Line 36: Replacement Tax Before Credits
Add Lines 34 and 35.
The calculation is:
Line 34 + Line 35 = Line 36.
Enter the replacement tax before applying credits.
Line 37: Replacement Tax Credit For Income Tax Paid To Another State
Enter the applicable replacement tax credit for income tax paid to another state while the trust was an Illinois resident.
Calculate the credit using Schedule CR.
Follow the applicable instructions and attach Schedule CR.
Line 38: Investment Credits
Enter the applicable investment credits.
Calculate the amount using Form IL-477.
Attach Form IL-477.
Line 39: Total Credits
Add Lines 37 and 38.
The calculation is:
Line 37 + Line 38 = Line 39.
Enter the total replacement tax credits.
Line 40: Net Replacement Tax
Subtract Line 39 from Line 36.
The calculation is:
Line 36 − Line 39 = Line 40.
If the result is negative, enter zero.
This is the trust’s net replacement tax after credits.
Step 6: Figure Your Net Income Tax
Step 6 applies to both trusts and estates.
It calculates the net income tax after applicable tax credits.
The section provides a comparison between previously reported or adjusted amounts and corrected amounts for the fiduciary.
Line 41: Net Income From Line 33
Transfer the net income amount from Line 33 to Line 41.
Enter the corresponding previously reported and corrected figures.
Line 42: Income Tax
Calculate the applicable Illinois income tax using the instructions for the 2025 tax year.
Enter the resulting amount.
The form directs taxpayers to consult the applicable instructions for this calculation.
Line 43: Recapture Of Investment Credits
Enter the applicable investment credit recapture amount.
Calculate it using Schedule 4255.
Attach Schedule 4255.
Line 44: Income Tax Before Credits
Add Lines 42 and 43.
The calculation is:
Line 42 + Line 43 = Line 44.
Enter the resulting income tax before credits.
Line 45: Income Tax Credit For Tax Paid To Another State
Enter the applicable credit for income tax paid to another state while the trust or estate was an Illinois resident.
Calculate the credit using Schedule CR.
Follow the applicable instructions and attach Schedule CR.
Line 46: Income Tax Credits
Enter the applicable Illinois income tax credits.
Calculate the amount using Schedule 1299-D.
Attach Schedule 1299-D.
Line 47: Total Credits
Add Lines 45 and 46.
The calculation is:
Line 45 + Line 46 = Line 47.
Enter the total credits.
Line 48: Net Income Tax
Subtract Line 47 from Line 44.
The calculation is:
Line 44 − Line 47 = Line 48.
If the result is negative, enter zero.
The resulting amount represents the net income tax after credits.
Step 7: Figure Your Refund Or Balance Due
Step 7 combines replacement tax, income tax, applicable surcharges, pass-through withholding, payments, and previous overpayments to determine whether the trust or estate is entitled to a refund or owes additional tax.
Line 49: Net Replacement Tax
For trusts only, enter the net replacement tax from Line 40.
Estates do not enter a replacement tax amount from Step 5.
Line 50: Net Income Tax
Enter the net income tax from Line 48.
Use the corrected amount from Step 6.
Line 51: Compassionate Use Of Medical Cannabis Program Act Surcharge
Enter the applicable surcharge associated with the Compassionate Use of Medical Cannabis Program Act.
Follow the applicable instructions to determine the amount.
Line 52: Sale Of Assets By Gaming Licensee Surcharge
Enter the applicable surcharge related to the sale of assets by a gaming licensee.
Consult the applicable instructions for the calculation.
Line 53: Pass-Through Withholding Owed On Behalf Of Members
Enter the amount of pass-through withholding owed on behalf of the trust’s or estate’s members.
Use Schedule D, Section A, Line 3.
Attach Schedule D to support the reported amount.
Line 54: Total Net Income And Replacement Taxes, Surcharges, And Pass-Through Withholding
Add Lines 49 through 53.
The calculation is:
Line 49 + Line 50 + Line 51 + Line 52 + Line 53 = Line 54.
This amount represents the total tax and withholding liability before payments are applied.
Line 55: Payments
Line 55 contains five separate categories of payments and credits.
Line 55a: Credits From Previous Overpayments
Enter the amount of credits carried forward from previous overpayments.
Use the applicable payment and overpayment records.
Line 55b: Total Payments Made Before Filing The Amended Return
Enter the total payments made before the date you file the amended return.
Include the applicable payments already made for the tax year being amended.
Line 55c: Pass-Through Withholding Reported To You
Enter the pass-through withholding reported to the trust or estate.
Use Schedule K-1-P or Schedule K-1-T.
Attach the applicable K-1 schedules.
Line 55d: Pass-Through Entity Tax Credit Reported To You
Enter the pass-through entity tax credit reported to the trust or estate.
Use Schedule K-1-P or Schedule K-1-T.
Attach the applicable schedules.
Line 55e: Illinois Income Tax Withheld
Enter the Illinois income tax withheld from the trust’s or estate’s income.
Attach the applicable Forms W-2, W-2G, and 1099 supporting the withholding information.
Line 56: Total Payments
Add Lines 55a through 55e.
The calculation is:
Line 55a + Line 55b + Line 55c + Line 55d + Line 55e = Line 56.
Enter the total payments.
Line 57: Previously Paid Penalty And Interest
Enter any penalty and interest previously paid for the tax year being amended.
Follow the applicable instructions to determine the amount.
Line 58: Total Amount Of Previous Overpayment
Enter the total amount of overpayment, including any amount previously carried forward or refunded, before filing the amended return for the year being corrected.
Follow the applicable instructions when calculating this amount.
Line 59: Total Previous Penalty, Interest, And Overpayment
Add Lines 57 and 58.
The calculation is:
Line 57 + Line 58 = Line 59.
Line 60: Net Tax Paid
Subtract Line 59 from Line 56.
The calculation is:
Line 56 − Line 59 = Line 60.
Enter the resulting net tax paid.
Line 61: Overpayment
Complete this line if Line 60 is greater than Line 54.
Subtract Line 54 from Line 60.
The calculation is:
Line 60 − Line 54 = Line 61.
The result represents the overpayment available for refund or credit.
Line 62: Amount Of Overpayment To Be Credited Forward
Enter the amount from Line 61 that you want credited toward a future tax period.
Follow the applicable instructions when determining the amount.
The form also provides a special checkbox for a credit transferred to a different FEIN.
Different FEIN Checkbox
Check this box and attach a detailed statement if the overpayment being carried forward will be applied to a different federal employer identification number.
The statement should explain the applicable transfer.
Line 63: Refund
Subtract Line 62 from Line 61.
The calculation is:
Line 61 − Line 62 = Line 63.
This is the amount to be refunded.
Line 64: Tax Due With This Amended Return
Complete this line if Line 54 is greater than Line 60.
Subtract Line 60 from Line 54.
The calculation is:
Line 54 − Line 60 = Line 64.
The resulting amount represents the additional tax due with the amended return.
The department will send a bill for any additional penalty and interest.
Payment Instructions For Line 64
If Line 64 shows an amount due, complete Form IL-1041-X-V.
Follow these instructions:
- Write the FEIN on the check or money order.
- Include the tax year ending date.
- Write “IL-1041-X-V” on the payment.
- Make the payment payable to “Illinois Department of Revenue.”
- Attach the voucher and payment to the first page of Form IL-1041-X.
- Enter the payment amount at the top of Page 1.
Step 8: Signature
Step 8 contains the fiduciary’s declaration, signature, contact details, and paid preparer information.
The person signing the return certifies that the information has been examined and is true, correct, and complete to the best of their knowledge.
Fiduciary Signature Information
Signature Of Fiduciary
The authorized fiduciary must sign the amended return.
The signature confirms that the fiduciary has reviewed the information and accepts responsibility for the declaration.
Date
Enter the date the fiduciary signs the return.
Use the month/day/year format.
Title
Enter the title or official capacity of the person signing on behalf of the trust or estate.
Phone
Enter a daytime telephone number where the fiduciary can be contacted.
Include the area code.
Paid Preparer Discussion Authorization
Check the box if you authorize the Illinois Department of Revenue to discuss the amended return with the paid preparer identified in this section.
Leave the box unchecked if you do not provide this authorization.
Paid Preparer Information
Complete this section when a paid tax preparer has prepared the return.
Print/Type Paid Preparer’s Name
Enter the full name of the paid tax preparer.
Paid Preparer’s Signature
The paid preparer must sign the designated field.
Date
Enter the date the paid preparer signs the return.
Check If Self-Employed
Select this box if the paid preparer is self-employed.
Paid Preparer’s PTIN
Enter the paid preparer’s Preparer Tax Identification Number (PTIN).
Firm’s Name
Enter the name of the tax preparation firm, if applicable.
Firm’s FEIN
Enter the firm’s federal employer identification number.
Firm’s Address
Provide the complete business mailing address of the tax preparation firm.
Firm’s Phone
Enter the firm’s telephone number, including the area code.
Mailing Address
The form provides the following mailing address at the bottom of Page 3:
Illinois Department of Revenue
P.O. Box 19016
Springfield, IL 62794-9016
Mail the completed return and required supporting documents to this address.
Schedule D: Beneficiary Information
Schedule D is an additional schedule included with the 2025 fiduciary amended return materials.
It collects beneficiary information and calculates the pass-through withholding and pass-through entity tax credit amounts that are reported on the fiduciary return.
Schedule D contains two sections:
- Section A: Total Beneficiaries’ Information.
- Section B: Beneficiaries’ Information.
The schedule must be attached to Form IL-1041 or Form IL-1041-X when applicable.
Schedule D: Basic Identification Information
Year Ending
Enter the tax year-ending date associated with the fiduciary return.
The form provides fields for the month and year.
Name As Shown On Form IL-1041
Enter the trust’s or estate’s name exactly as it appears on Form IL-1041.
Use the same legal name when completing the schedule.
Federal Employer Identification Number (FEIN)
Enter the FEIN associated with the trust or estate.
Make sure the number matches the FEIN on the main fiduciary return.
Important Instructions Before Completing Schedule D
Schedule D includes two preliminary requirements.
First, read the Schedule D instructions and complete the applicable Schedule K-1-T and Schedule K-1-T(3) forms before completing Schedule D.
Second, complete Section B of Schedule D and provide all required beneficiary information before completing Section A.
The form warns that failure to follow these instructions may delay return processing or result in additional correspondence from the Illinois Department of Revenue.
The department may also request further information to support the filing.
Schedule D, Section A: Total Beneficiaries’ Information
Section A collects totals from Schedule K-1-T and Schedule D, Section B.
Before completing this section, finish the applicable K-1 schedules and all beneficiary information in Section B.
Line 1: Total Nonbusiness Income Or Loss Reported To Beneficiaries
Enter the total of all nonbusiness income or loss reported for beneficiaries on the applicable Schedule K-1-T forms.
Combine the relevant amounts from all applicable beneficiary schedules.
Line 2a: Pass-Through Withholding For Nonresident Individual Beneficiaries
Enter the total pass-through withholding reported on Schedule D, Section B, Line G, for all nonresident individual beneficiaries.
Include the amounts from all applicable pages of Section B.
Line 2b: Pass-Through Withholding For Nonresident Estate Beneficiaries
Enter the total pass-through withholding reported on Schedule D, Section B, Line G, for all nonresident estate beneficiaries.
Combine the applicable amounts.
Line 2c: Pass-Through Withholding For Partnership And S Corporation Beneficiaries
Enter the total pass-through withholding reported for partnership and S corporation beneficiaries.
Use the applicable amounts from Schedule D, Section B, Line G.
Line 2d: Pass-Through Withholding For Nonresident Trust Beneficiaries
Enter the total pass-through withholding reported for nonresident trust beneficiaries.
Use the applicable amounts from all completed Section B pages.
Line 2e: Pass-Through Withholding For C Corporation Beneficiaries
Enter the total pass-through withholding reported for C corporation beneficiaries.
Use the applicable amounts from Schedule D, Section B, Line G.
Line 3: Total Pass-Through Withholding Owed On Behalf Of Nonresident Beneficiaries
Add Lines 2a through 2e.
The calculation is:
Line 2a + Line 2b + Line 2c + Line 2d + Line 2e = Line 3.
This amount represents the total pass-through withholding owed on behalf of all nonresident beneficiaries.
The amount must match the total of Schedule D, Section B, Line G, for all nonresident beneficiaries across all pages.
Transfer the total to Form IL-1041 or Form IL-1041-X, Line 53.
Line 4: Total Pass-Through Entity Tax Credit Received And Distributed
Enter the total pass-through entity tax credit received and distributed to beneficiaries.
Calculate the amount by adding the applicable figures from Schedule D, Section B, Line H, across all pages.
Make sure the total reflects the credits received and distributed to beneficiaries.
Schedule D Section B Attachment Requirement
Attach all pages of Schedule D, Section B, behind the Section A page.
Make sure every beneficiary listed in Section B is included in the totals reported in Section A.
Schedule D, Section B: Beneficiaries’ Information
Section B collects detailed information about each beneficiary.
The schedule provides space for three beneficiaries per page:
- Member 1.
- Member 2.
- Member 3.
If the trust or estate has more beneficiaries than the available space, attach additional copies of the Section B page.
Enter the trust’s or estate’s name and FEIN at the top of each additional page.
Beneficiary Identification
Column A: Name
Enter the full name of the beneficiary.
Use the name associated with the beneficiary’s tax identification records.
C/O
Enter the care-of name or attention line if the beneficiary’s mailing address uses one.
Address 1
Enter the beneficiary’s primary mailing address.
Address 2
Enter any additional address information, such as an apartment, suite, or unit number.
City
Enter the city associated with the beneficiary’s mailing address.
State, ZIP
Enter the beneficiary’s state and ZIP code.
Make sure the complete mailing address is provided.
Column B: Beneficiary Type
Enter the applicable beneficiary classification.
The beneficiary type should correspond to the classifications used for pass-through withholding on Schedule D.
The categories referenced in Section A include:
- Nonresident individual beneficiaries.
- Nonresident estate beneficiaries.
- Partnership and S corporation beneficiaries.
- Nonresident trust beneficiaries.
- C corporation beneficiaries.
Use the appropriate beneficiary type for each member.
Column C: SSN/FEIN
Enter the beneficiary’s applicable tax identification number.
Use:
- Social Security Number (SSN) for an individual beneficiary.
- Federal Employer Identification Number (FEIN) for an entity beneficiary.
Check the number carefully before completing the schedule.
Column D: Beneficiary’s Amount Of Base Income Or Loss
Enter the beneficiary’s allocated amount of base income or loss.
Use the applicable information from the fiduciary’s beneficiary allocation records and supporting schedules.
Column E: Excluded From Pass-Through Withholding
Indicate whether the beneficiary is excluded from pass-through withholding.
Use the applicable instructions to determine whether the beneficiary qualifies for exclusion.
Column F: Share Of Illinois Income Subject To Pass-Through Withholding
Enter the beneficiary’s share of Illinois income that is subject to pass-through withholding.
Use the applicable income allocation information.
This figure identifies the Illinois income portion associated with the withholding calculation.
Column G: Pass-Through Withholding Amount Before Credits
Enter the pass-through withholding amount calculated before applying credits.
This amount is used in Schedule D, Section A, to determine the total withholding liability for the applicable beneficiary categories.
Include the amount in the relevant Section A total.
Column H: PTE Tax Credit Received And Distributed To Beneficiaries
Enter the pass-through entity (PTE) tax credit received and distributed to the beneficiary.
Use the applicable credit allocation information.
The amount entered here contributes to the total reported on Schedule D, Section A, Line 4.
Additional Beneficiary Pages
If there are more than three beneficiaries, attach additional copies of Schedule D, Section B.
Each additional page should contain the applicable beneficiary information.
Include all beneficiaries so that the totals reported in Section A reflect the complete beneficiary information.
Important Supporting Schedules And Documents
Form IL-1041-X references several supporting schedules and federal forms.
The following table identifies the documents mentioned throughout the amended return.
| Document or Schedule | Related Line or Section | Purpose |
|---|---|---|
| Federal Form 1041 | Lines 1, 2, and 4 | Supports federal taxable income, net operating loss deduction, and exemption |
| Schedule F | Line 13 | Supports the August 1, 1969, valuation limitation amount |
| Schedule 1299-B | Lines 17 and 18 | Supports specified dividend subtractions |
| Schedule M | Lines 10 and 24 | Supports other additions and subtractions |
| Form IL-4562 | Lines 7 and 20 | Supports Illinois special depreciation additions and subtractions |
| Schedule 80/20 | Lines 8 and 21 | Supports related-party expense additions and subtractions |
| Schedule K-1-P or K-1-T | Lines 9, 22, 55c, and 55d | Supports distributive shares and pass-through information |
| Schedule NR | Lines 27 and 31; Step 1 | Supports nonresident income and standard exemption information |
| Federal Form 982 | Line 28 and Box N | Supports discharge of indebtedness adjustments |
| Schedule NLD | Line 30 and Box E | Supports Illinois net loss deduction adjustments |
| Schedule 4255 | Lines 35 and 43 | Supports investment credit recapture |
| Schedule CR | Lines 37 and 45 | Supports credits for income tax paid to another state |
| Form IL-477 | Line 38 | Supports investment credits |
| Schedule 1299-D | Line 46 and Box I | Supports Illinois income tax credits |
| Schedule D | Line 53 and Step 1 | Supports beneficiary information and pass-through withholding |
| Schedule K-1-T(3) | Schedule D preparation | Provides required beneficiary-related information |
| Federal Form 8886 | Box M | Supports the applicable federal disclosure filing |
| Federal Form 1040? | Not specified | Not identified as a required document on this fiduciary return |
The required attachments depend on the specific adjustments and credits being reported.
Always review the applicable instructions to determine which supporting documents must accompany the amended return.
Common Mistakes To Avoid When Completing Form IL-1041-X
Amended fiduciary tax returns involve several calculations and beneficiary allocations. Review the following common mistakes before submitting the form.
- Using the wrong tax-year form: The 2025 version applies to tax years ending on or after December 31, 2025.
- Entering an incorrect legal name: Use the complete legal name of the trust or estate.
- Using an incorrect FEIN: Verify the number against federal tax records.
- Selecting the wrong fiduciary type: Identify whether the return belongs to a trust or estate.
- Failing to identify the reason for the amendment: Complete Box E accurately.
- Omitting federal finalization information: Provide the finalization date and supporting documentation when applicable.
- Confusing Column A and Column B: Column A contains previously reported or adjusted amounts, while Column B contains corrected figures.
- Mixing beneficiary and fiduciary amounts: Use the appropriate columns throughout Steps 2 and 3.
- Entering negative amounts where prohibited: Line 2 specifically states that the federal net operating loss deduction cannot be negative.
- Forgetting supporting depreciation forms: Attach Form IL-4562 when reporting the applicable additions or subtractions.
- Leaving out Schedule 80/20: Attach it when reporting related-party expense adjustments.
- Incorrectly calculating total subtractions: Verify the amounts included in Line 25.
- Using the wrong residency calculation: Nonresidents must complete Schedule NR where required.
- Incorrectly entering the Illinois net loss deduction: Line 30 must be zero when Line 29 is zero or negative.
- Completing Step 5 for an estate: Estates skip Step 5 and proceed to Step 6.
- Forgetting investment credit recapture: Include applicable amounts on Lines 35 or 43.
- Omitting beneficiary withholding: Complete Schedule D when required.
- Failing to complete Schedule D Section B first: Section B must be completed before Section A.
- Leaving out beneficiaries: Include additional Section B pages when more than three beneficiaries are involved.
- Incorrectly calculating pass-through withholding: Make sure Schedule D, Section A, Line 3 matches the applicable Section B, Line G totals.
- Reporting an incorrect PTE tax credit: Verify the distributed credit amounts on Section B, Line H.
- Entering an incorrect previous overpayment: Review Lines 57 through 59 carefully.
- Failing to attach a transfer statement: If a carryforward goes to a different FEIN, check the designated box and attach a detailed statement.
- Missing the payment voucher: If Line 64 shows an amount due, complete and attach Form IL-1041-X-V with payment.
- Forgetting the fiduciary signature: Make sure the authorized fiduciary signs and dates the return.
- Using an incomplete mailing address: Send the return to the address provided on Page 3.
Final Review Before Filing
Before mailing Form IL-1041-X, review the following checklist to make sure all applicable sections and supporting schedules are complete.
Step 1: Fiduciary Identification
- The correct tax year beginning and ending dates are entered.
- The payment amount is entered, if applicable.
- The complete legal name of the trust or estate is provided.
- The name-change box is checked when applicable.
- The mailing address is complete.
- The correct fiduciary type is selected.
- All applicable fiduciary classifications are checked.
- The correct amendment reason is selected.
- Federal change status and finalization date are entered when applicable.
- The complete FEIN is provided.
- All applicable boxes G through Q are reviewed.
- A detailed explanation of the amendment is included.
- Required supporting documents are identified.
Step 2: Income Or Loss
- Column A contains the most recently reported or adjusted figures.
- Column B contains the corrected figures.
- Beneficiary and fiduciary amounts are entered in the appropriate columns.
- Lines 1 through 4 are accurate.
- Lines 5 through 10 include applicable additions.
- Required supporting schedules are attached.
- Line 11 is correctly calculated.
Step 3: Base Income Or Loss
- Line 12 matches Line 11.
- Line 13 includes applicable valuation limitation amounts.
- Lines 14 through 24 contain applicable subtractions.
- Schedule F is attached when required.
- Schedule 1299-B is attached when required.
- Form IL-4562 is attached when required.
- Schedule 80/20 is attached when required.
- Schedule M is attached when required.
- Line 25 correctly calculates total subtractions.
- Line 26 correctly calculates base income or loss.
- Schedule NR is completed when applicable.
Step 4: Net Income
- Line 27 reflects the correct residency calculation.
- Line 28 includes the applicable discharge of indebtedness adjustment.
- Federal Form 982 is attached when required.
- Line 29 is correctly calculated.
- Line 30 includes the applicable Illinois net loss deduction.
- Line 31 includes the correct standard exemption.
- Line 32 correctly totals deductions.
- Line 33 correctly calculates net income.
Steps 5–6: Replacement Tax And Income Tax
- Step 5 is completed for trusts only.
- Estates proceed directly to Step 6.
- Line 34 uses the 1.5% replacement tax rate.
- Line 35 includes applicable investment credit recapture.
- Line 36 is correctly calculated.
- Line 37 includes applicable credits from Schedule CR.
- Line 38 includes applicable investment credits.
- Line 39 correctly totals credits.
- Line 40 correctly calculates net replacement tax.
- Line 41 matches Line 33.
- Line 42 contains the applicable income tax.
- Line 43 includes applicable investment credit recapture.
- Line 44 correctly calculates income tax before credits.
- Lines 45 and 46 include applicable credits.
- Line 47 correctly totals credits.
- Line 48 correctly calculates net income tax.
Step 7: Refund Or Balance Due
- Line 49 includes net replacement tax for trusts.
- Line 50 includes net income tax.
- Lines 51 and 52 include applicable surcharges.
- Line 53 includes applicable pass-through withholding.
- Schedule D is attached when required.
- Line 54 correctly calculates total tax and withholding.
- Lines 55a through 55e contain the applicable payment information.
- Line 56 correctly totals payments.
- Line 57 includes previously paid penalty and interest, if applicable.
- Line 58 includes the applicable previous overpayment.
- Line 59 is correctly calculated.
- Line 60 correctly calculates net tax paid.
- Line 61 correctly calculates overpayment, if applicable.
- Line 62 reflects the amount carried forward.
- The different-FEIN checkbox and statement are included when applicable.
- Line 63 correctly calculates the refund.
- Line 64 correctly calculates additional tax due.
- Form IL-1041-X-V is completed when payment is required.
Schedule D: Beneficiary Information
- The correct tax year is entered.
- The trust’s or estate’s name matches Form IL-1041.
- The FEIN is correct.
- Schedule K-1-T and Schedule K-1-T(3) are completed as required.
- Section B is completed before Section A.
- All beneficiary names and addresses are accurate.
- Each beneficiary’s type is identified.
- SSNs or FEINs are entered correctly.
- Beneficiary base income or loss is reported.
- Pass-through withholding exclusions are identified.
- Illinois income subject to withholding is reported.
- Line G contains the applicable withholding amount before credits.
- Line H contains the applicable PTE tax credit received and distributed.
- Additional Section B pages are attached when necessary.
- Section A totals match the applicable Section B amounts.
- Line 3 matches the withholding reported on Form IL-1041-X, Line 53.
- Line 4 includes the total PTE tax credit received and distributed.
- All Section B pages are attached behind Section A.
Step 8: Signatures And Submission
- The fiduciary has signed the return.
- The signature date is entered.
- The fiduciary’s title is provided.
- A daytime phone number is included.
- Paid preparer information is completed when applicable.
- The preparer’s PTIN is provided.
- The firm’s name, FEIN, address, and phone number are entered when applicable.
- The paid preparer discussion authorization is checked only when permission is granted.
- All required supporting documents are attached.
- The correct mailing address is used.
- Form IL-1041-X-V and payment are attached when Line 64 shows an amount due.
Final Reminder: Illinois Form IL-1041-X is used to correct a previously filed fiduciary income and replacement tax return for a trust or estate. Review all eight steps carefully, compare previously reported amounts with corrected figures, and make sure beneficiary and fiduciary amounts are properly allocated. Pay particular attention to Schedule D, because its beneficiary information and pass-through withholding calculations affect the amounts reported on the main return. Attach all applicable supporting schedules, complete the required signatures, and mail the amended return to the Illinois Department of Revenue, P.O. Box 19016, Springfield, IL 62794-9016.