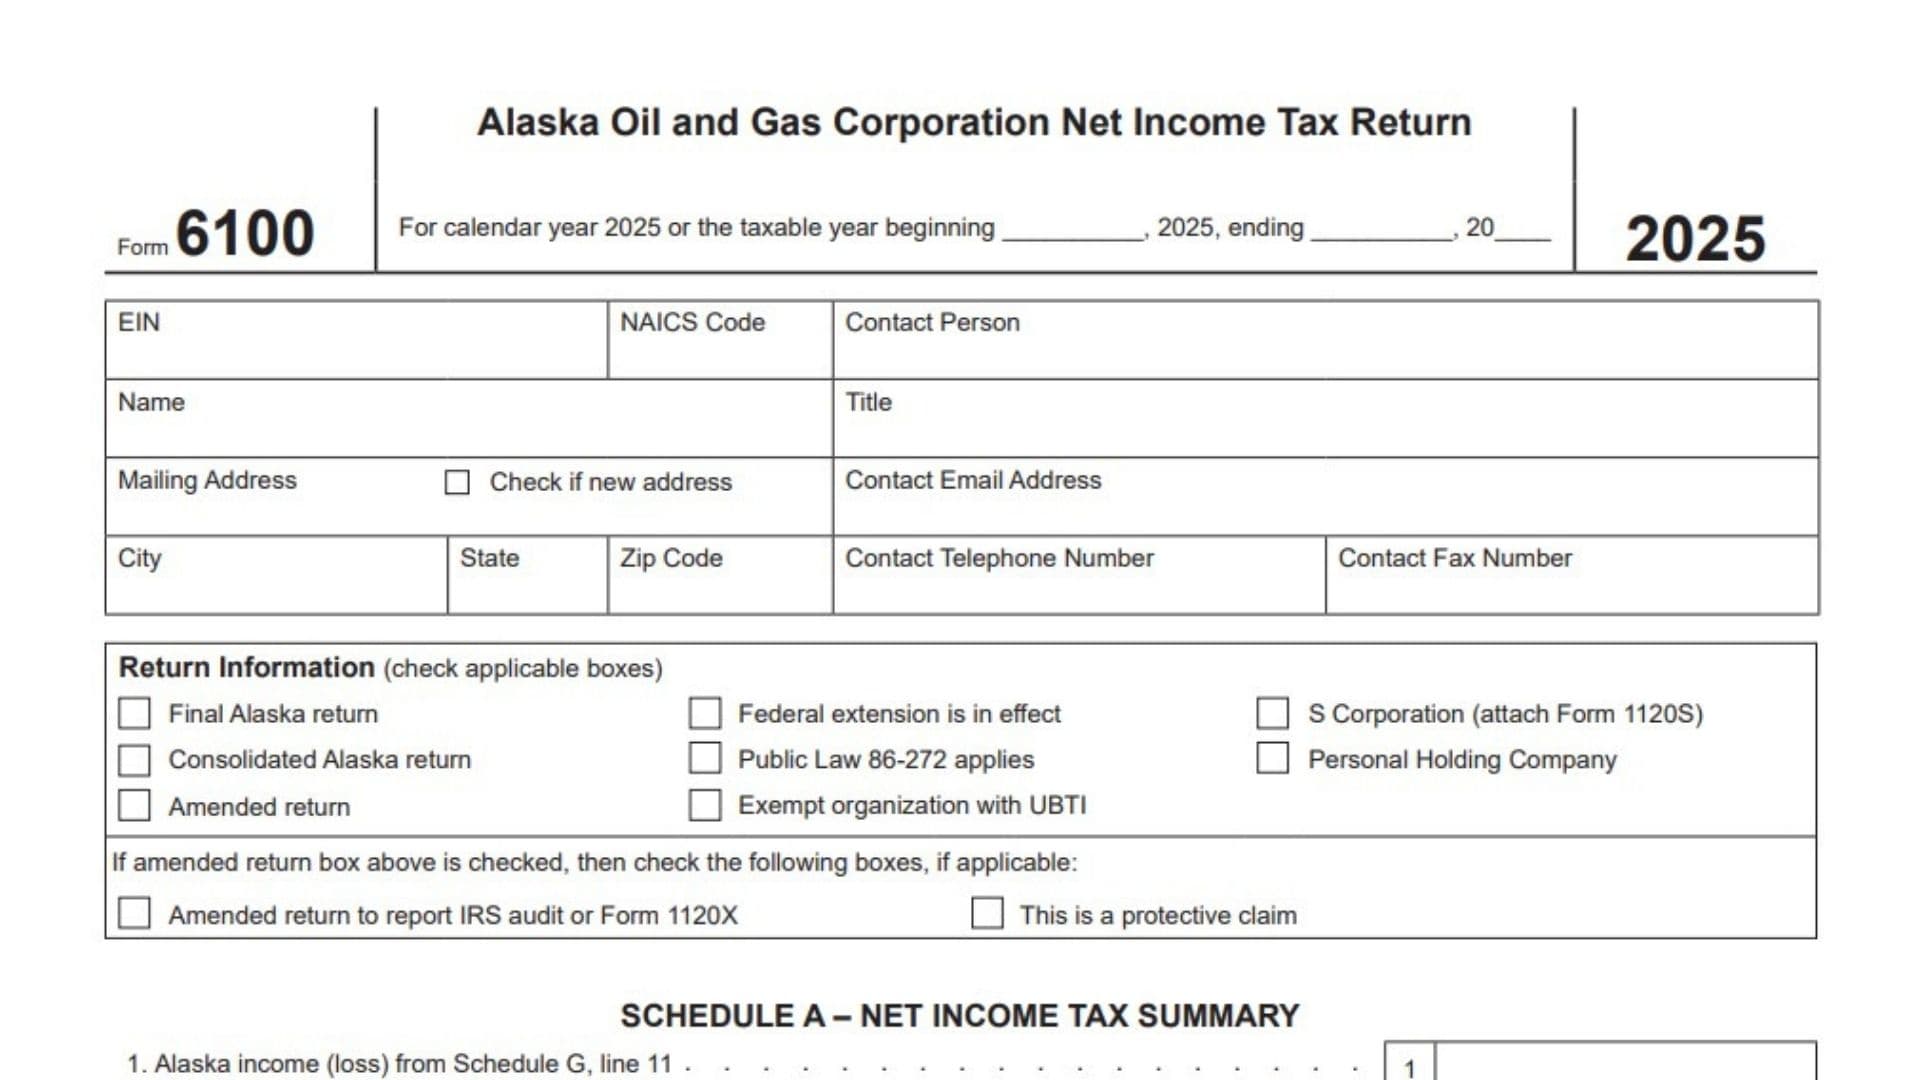
Alaska Form 6100, officially called the Alaska Oil and Gas Corporation Net Income Tax Return, is a state tax return used by corporations to report and calculate their applicable Alaska net income tax obligations. The form is designed to determine the portion of a corporation’s income subject to Alaska taxation, calculate the applicable tax, report additional taxes and credits, and reconcile estimated payments with the final tax liability. It collects business identification information, including the employer identification number (EIN), North American Industry Classification System (NAICS) code, company name, mailing address, and contact details. It also identifies the corporation’s filing status, including whether the return is final, consolidated, amended, or subject to particular federal tax provisions. The return contains several schedules that work together to calculate the corporation’s Alaska taxable income and tax liability. Schedule A summarizes the tax calculation, credits, payments, refunds, and amounts owed. Schedule B collects information about corporations included in a consolidated Alaska return and other business identification details. Schedule C records estimated tax payments, extension payments, and prior-year overpayments. Schedule D calculates Alaska income tax, while Schedule E reports additional taxes, including applicable alternative minimum tax and base erosion and anti-abuse tax amounts. Schedule G determines Alaska taxable income by starting with federal taxable income and making the required combined reporting adjustments, additions, subtractions, and apportionment calculations. Schedule I calculates the apportionment factor using property, extraction, and sales information. Schedule J calculates Alaska capital gains and losses, including Section 1231 gains and losses. Schedule K calculates the allowable Alaska charitable contribution deduction, and Schedule L determines the Alaska dividends-received deduction. Completing Form 6100 correctly is important because the corporation’s federal income, Alaska-specific adjustments, business activities, apportionment factors, deductions, credits, and payments all affect its final Alaska tax liability. The 2025 form applies to the calendar year 2025 or a fiscal tax year beginning in 2025 and ending in the year entered on the return.
How To File Alaska Form 6100
Form 6100 is filed with the Alaska Department of Revenue (DOR) as the corporation’s Alaska Oil and Gas Corporation Net Income Tax Return.
The form is the main tax return, not an attachment to another Alaska income tax return. Its supporting schedules, including Schedules A, B, C, D, E, G, I, J, K, and L, are completed as applicable and submitted as part of the return.
The form itself does not provide a mailing address, filing deadline, or electronic submission procedure. Consult the applicable Alaska Department of Revenue filing instructions to confirm the current submission method and deadline.
Information And Documents To Prepare
Before completing Form 6100, gather the following business and tax information:
- Business identification: Employer Identification Number (EIN), company name, NAICS code, mailing address, and contact details.
- Federal income tax return: Federal taxable income or loss and relevant information from the corporation’s federal return.
- Combined reporting information: Federal taxable income or loss for other domestic and foreign corporations included in the combined reporting calculation.
- Corporate information: EIN, business name, address, and NAICS code for other corporations with Alaska nexus included in a consolidated return.
- Federal tax information: Applicable amounts from federal Forms 1120, 1120S, 4626, 4797, and 8991.
- Oil and gas information: Alaska property, extraction, transportation, production, and sales information, as applicable.
- Business apportionment records: Property values, extraction amounts, and sales figures for Alaska and everywhere.
- Capital gain and loss information: Current and prior-year Section 1231 gains and losses, short-term capital gains and losses, and long-term capital gains and losses.
- Net operating loss records: Available Alaska NOL carryovers and amounts utilized during the tax year.
- Charitable contribution records: Current charitable contributions, education credit contributions, and applicable carryforward amounts.
- Dividend information: Dividend income, intercompany dividends, and dividends qualifying for the applicable dividends-received deduction.
- Tax credit information: Applicable Alaska incentive credits and federal-based credits.
- Payment records: Estimated tax payments, extension payments, prior-year overpayments, and any refunds or additional payments.
- Supporting schedules: Applicable information from Forms 6220, 6230, 6300, 6310, 6327, 6385, and 6390.
Keep copies of the relevant federal returns, supporting calculations, and previous Alaska tax returns available when preparing the schedule.
Supporting Forms And Attachments
Depending on the corporation’s circumstances, the return refers to several additional forms:
- Federal Form 1120: Provides federal corporate income tax information used in the Alaska income calculation.
- Federal Form 1120S: Attach a copy when the S Corporation box is selected.
- Federal Form 4626: Provides the federal alternative minimum tax amount used in Schedule E.
- Federal Form 4797: Provides Section 1231 gain and loss information used in Schedule G and Schedule J.
- Federal Form 8991: Provides the base erosion and anti-abuse tax amount used in Schedule E.
- Form 6220: Attach this form when the net Alaska income tax on Schedule A, line 9, is more than $500, as directed on the return.
- Form 6230: Provides the Quick Refund amount deducted in Schedule C.
- Form 6300: Provides Alaska incentive credit information transferred to Schedule A.
- Form 6310: Provides education credit contribution information used in Schedule K.
- Form 6327: Provides oil and gas service industry expenditure information used in Schedule G.
- Form 6385: Provides the Alaska charitable contribution carryforward amount used in Schedule K.
- Form 6390: Provides federal-based credit information transferred to Schedule A.
The form also requires separate supporting schedules for certain other additions, subtractions, and non-business income calculations.
How To Complete Alaska Form 6100
The 2025 Alaska Form 6100 contains seven pages. Each page collects different information and performs a specific part of the overall tax calculation.
Follow the instructions below to complete the main return and every schedule.
Page 1: Taxpayer Information And Net Income Tax Summary
Page 1 collects the corporation’s identification details, filing information, and final Alaska income tax calculation.
Taxpayer And Business Identification
Tax Year
The form covers the calendar year 2025 or a taxable year beginning in 2025 and ending in another year.
If the corporation uses the calendar year, report the 2025 tax year as indicated.
If the corporation uses a fiscal year, enter the beginning date and ending date in the designated fields.
EIN
Enter the corporation’s nine-digit Employer Identification Number.
Use the EIN assigned to the business by the Internal Revenue Service.
NAICS Code
Enter the corporation’s applicable North American Industry Classification System code.
Use the code that identifies the corporation’s primary business activity.
Contact Person
Enter the full name of the individual responsible for handling questions about the return.
This person may be contacted if the Alaska Department of Revenue needs additional information.
Name
Enter the corporation’s complete legal business name.
Make sure the name matches the business identification information used on the associated tax records.
Title
Enter the professional title or position of the contact person listed on the return.
Mailing Address
Enter the corporation’s complete mailing address.
Include the street number, street name, suite number, or other applicable address information.
Check If New Address
Mark this checkbox if the mailing address entered on the return is new or has changed.
Leave it unchecked if the address has not changed.
Contact Email Address
Enter the email address of the individual responsible for the return.
Use an active email address where the department can reach the corporation.
City
Enter the city associated with the corporation’s mailing address.
State
Enter the two-letter state abbreviation.
ZIP Code
Enter the ZIP code associated with the mailing address.
Contact Telephone Number
Enter the contact person’s telephone number, including the appropriate area code.
Contact Fax Number
Enter the corporation’s fax number if applicable.
Return Information
This section contains several checkboxes used to identify the corporation’s filing circumstances.
Mark all boxes that apply.
Final Alaska Return
Select this option if the corporation is filing its final Alaska return.
Consolidated Alaska Return
Select this option if the corporation is filing a consolidated Alaska return that includes other corporations.
Complete Schedule B with the required information about the included corporations.
Amended Return
Select this option if you are submitting a corrected or amended Form 6100.
If you select this box, review the additional amended-return questions immediately below it.
Federal Extension Is In Effect
Mark this box if the corporation has an applicable federal tax filing extension in effect.
Public Law 86-272 Applies
Select this box if the corporation’s activities qualify for the application of Public Law 86-272.
Exempt Organization With UBTI
Mark this box if the filing organization is an exempt organization with unrelated business taxable income (UBTI).
S Corporation (Attach Form 1120S)
Select this option if the corporation is filing as an S Corporation.
Attach the applicable federal Form 1120S as directed on the return.
Personal Holding Company
Mark this box if the corporation is classified as a personal holding company.
This classification is relevant to the additional tax calculation in Schedule E.
Additional Amended Return Information
Complete these questions only if the Amended Return checkbox above has been selected.
Amended Return To Report IRS Audit Or Form 1120X
Mark this box if the amended Alaska return is being filed to report an IRS audit adjustment or information from an amended federal Form 1120X.
This Is A Protective Claim
Mark this box if the amended return is being submitted as a protective claim.
Select this option only when the filing meets the applicable requirements for a protective claim.
Schedule A: Net Income Tax Summary
Schedule A summarizes the corporation’s Alaska taxable income, tax liability, credits, payments, penalties, overpayments, and refunds.
Complete the supporting schedules first when applicable, then transfer the calculated amounts to the corresponding lines.
Line 1: Alaska Income (Loss) From Schedule G, Line 11
Enter the Alaska taxable income or loss calculated on Schedule G, line 11.
Transfer the amount directly from Schedule G.
This figure represents Alaska income or loss before applying the Alaska net operating loss utilization reported on line 2.
Line 2: Alaska Net Operating Loss Utilized
Enter the amount of Alaska net operating loss used during the tax year.
The form displays this amount in parentheses because it reduces Alaska taxable income.
Complete the carryover identification blank shown beside the line when applicable.
Use the corporation’s available Alaska NOL records to determine the amount utilized.
Line 3: Alaska Taxable Income
Add lines 1 and 2.
Because the NOL amount on line 2 reduces income, the resulting amount reflects Alaska taxable income after the applicable NOL utilization.
Line 4: Alaska Income Tax From Schedule D, Line 2
Enter the Alaska income tax calculated on Schedule D, line 2.
Transfer the amount directly from Schedule D.
Line 5: Other Taxes From Schedule E, Line 7
Enter the total other taxes calculated on Schedule E, line 7.
This amount includes the applicable additional taxes calculated on that schedule.
Line 6: Total Tax
Add lines 4 and 5.
Enter the combined Alaska income tax and other applicable taxes.
Line 7: Alaska Incentive Credits Applied Against Tax
Enter the Alaska incentive credits applied against tax from Form 6300, line 30.
Transfer the applicable credit amount from Form 6300.
Line 8: Federal-Based Credits
Enter the applicable federal-based credits from Form 6390, line 33.
Transfer the amount from the supporting form.
Line 9: Net Alaska Income Tax
Subtract the sum of lines 7 and 8 from line 6.
The calculation is:
Net Alaska Income Tax = Line 6 − (Line 7 + Line 8)
If the resulting amount is more than $500, attach Form 6220 as directed on the return.
Line 10: Payments From Page 3, Schedule C
Enter the total net payments calculated on Schedule C.
Transfer the amount from the final line of Schedule C.
This includes the applicable estimated payments, extension payments, and other payment adjustments.
Line 11: Alaska Credit For Prior Minimum Tax
Enter any applicable Alaska credit for prior minimum tax.
Use the relevant Alaska instructions to determine whether the corporation qualifies for this credit and how to calculate the amount.
Line 12: Reserved
This line is reserved.
Do not enter an amount unless the applicable tax instructions specifically provide otherwise.
Line 13: Tax Due (Overpaid)
Subtract the sum of lines 10 and 11 from line 9.
The calculation is:
Tax Due (Overpaid) = Line 9 − (Line 10 + Line 11)
A positive result indicates an amount due.
A negative result indicates an overpayment.
Line 14: Penalty For Underpayment Of Estimated Tax
Enter any applicable penalty for underpayment of estimated tax.
Use the applicable Alaska instructions to determine whether a penalty applies and how to calculate it.
Line 15: Total Amount Due (Overpaid)
Add lines 13 and 14.
If the result is greater than zero, the form directs you to stop.
A positive amount represents the total amount due.
If the result represents an overpayment, continue to line 16.
Line 16: Overpayment Credited To 2026 Estimated Tax
Enter the portion of the overpayment you want applied toward the corporation’s 2026 estimated tax.
Enter this amount as a positive number.
Do not enter more than the available overpayment.
Line 17: Refund
Add lines 15 and 16.
Enter the resulting amount as directed by the form.
This calculation determines the refund remaining after accounting for the amount credited toward 2026 estimated tax.
Taxpayer Declaration And Signature
The bottom of page 1 contains the taxpayer declaration, authorization, officer signature, and paid preparer information.
Declaration
The corporation’s authorized officer declares that the return, including all attached schedules and statements, has been examined and is true, correct, and complete to the best of their knowledge and belief.
The paid preparer’s declaration is based on the information available to the preparer.
Check If The DOR May Discuss This Return With The Preparer
Mark this checkbox if the corporation authorizes the Alaska Department of Revenue to discuss the return with the paid preparer.
Refer to the applicable instructions for the scope of this authorization.
Officer’s Signature
The corporation’s authorized officer must sign the return.
The signature confirms the officer’s declaration regarding the accuracy and completeness of the information reported.
Date
Enter the date the officer signs the return.
Title
Enter the officer’s official position or title within the corporation.
Paid Preparer Information
Complete the following fields when a paid tax preparer prepares the return.
Preparer’s Signature
The paid preparer must sign the return in the designated field.
Date
Enter the date the preparer signs the return.
Preparer Firm’s Name
Enter the full name of the tax preparation firm.
Preparer’s SSN Or PTIN
Enter the preparer’s Social Security number or Preparer Tax Identification Number, as applicable.
Preparer Firm’s Address
Enter the complete mailing address of the tax preparation firm.
EIN
Enter the firm’s Employer Identification Number.
Phone
Enter the telephone number of the tax preparation firm.
City
Enter the city where the preparer or firm is located.
State
Enter the two-letter state abbreviation.
ZIP Code
Enter the firm’s ZIP code.
Page 2: Schedule B – Alaska Taxpayer Information
Schedule B collects additional corporate information, particularly when the return includes multiple corporations under Alaska consolidated reporting.
Complete the sections that apply to the corporation’s filing situation.
Schedule B, Section 1: Corporations Included In An Alaska Consolidated Return
This section applies only to Alaska consolidated returns.
List all corporations other than the primary taxpayer identified on page 1 that have nexus in Alaska and are included in the return.
The form warns that failing to complete this section properly may result in penalties.
The schedule provides space for four additional corporations.
Column A: Name Of Each Corporation With Nexus In Alaska
Enter the legal name of each corporation included in the Alaska consolidated return.
For each corporation, also complete the following identification fields.
Address
Enter the corporation’s complete mailing or business address.
City
Enter the city where the corporation is located.
State
Enter the applicable two-letter state abbreviation.
ZIP Code
Enter the corporation’s ZIP code.
Factor Numerators To Be Reported: Property
Mark this checkbox when the corporation has property information that must be included in the applicable Alaska apportionment factor calculation.
Factor Numerators To Be Reported: Extraction
Mark this checkbox when the corporation has extraction information that must be included in the Alaska apportionment factor calculation.
Factor Numerators To Be Reported: Sales
Mark this checkbox when the corporation has sales information that must be included in the Alaska apportionment factor calculation.
Select the applicable factor categories for each corporation.
Column B: P.L. 86-272 Applies
Mark the checkbox if Public Law 86-272 applies to the corporation listed in that row.
Column C: EIN
Enter the corporation’s Employer Identification Number.
Column D: NAICS Code
Enter the corporation’s applicable North American Industry Classification System code.
Repeat the process for every additional corporation included in the consolidated Alaska return.
Schedule B, Section 2: Federal Consolidated Return Information
Common Parent’s EIN
If any taxpayer included in the Alaska return is also included in a federal consolidated return using Form 1120, enter the common parent’s Employer Identification Number.
Common Parent’s Name
Enter the legal name of the common parent corporation of the federal consolidated group.
Address
Enter the common parent’s complete mailing address.
City
Enter the city associated with the common parent’s address.
State
Enter the two-letter state abbreviation.
ZIP Code
Enter the common parent’s ZIP code.
This section identifies the parent corporation responsible for the federal consolidated group.
Schedule B, Section 3: Successor To A Previously Existing Business
Complete this section if this is the corporation’s first Alaska return and it is a successor to a previously existing business.
Successor To Previously Existing Business Checkbox
Mark this box if the corporation is succeeding a previously existing business.
If this box is selected, provide the former business’s identification information.
Previous Business EIN
Enter the Employer Identification Number of the previously existing business.
Previous Business Name
Enter the former business’s legal name.
Previous Business Address
Enter the former business’s complete address.
City
Enter the city where the previous business was located.
State
Enter the applicable state abbreviation.
ZIP Code
Enter the previous business’s ZIP code.
Schedule B, Section 4: Prior-Year Return Information
Complete this section if the corporation’s name or EIN differs from the information reported on page 1 of the prior year’s return.
Prior-Year EIN
Enter the Employer Identification Number reported on the previous year’s return.
Prior-Year Name
Enter the business name reported on the previous year’s return.
Reason For Change
Explain why the business name or EIN has changed.
The form gives examples such as a merger or a name change.
Provide a clear explanation of the change so that the department can identify the relationship between the prior-year filing and the current return.
Page 3: Schedule C – Tax Payment Record
Schedule C records estimated tax payments and other payments or credits applied toward the corporation’s 2025 Alaska tax liability.
It contains two sections: an estimated payment table and a payment summary.
Estimated Payments
The left side of Schedule C provides space for four estimated tax payments.
First Estimated Payment
Enter the date and amount of the first estimated tax payment made for the applicable tax year.
Second Estimated Payment
Enter the date and amount of the second estimated tax payment.
Third Estimated Payment
Enter the date and amount of the third estimated tax payment.
Fourth Estimated Payment
Enter the date and amount of the fourth estimated tax payment.
Total Estimated Tax Payments
Add the amounts from the first, second, third, and fourth estimated payments.
Enter the combined total in the final row of the estimated payment table.
Payment Summary
The right side of Schedule C summarizes the additional payments and adjustments used to determine the total net payments transferred to Schedule A.
Payment With Extension
Enter the amount paid with the corporation’s applicable tax filing extension.
Enter the payment date in the Date column.
Total Estimated Tax Payments
Transfer the total estimated tax payments from the left side of Schedule C.
Overpayment From Prior Year
Enter the portion of a prior-year overpayment applied toward the current tax year’s liability.
Less: Quick Refund From Form 6230
Enter the amount of any applicable Quick Refund received through Form 6230.
Subtract this amount from the payment total.
The form displays this amount in parentheses.
Amended Return Only
Complete the following entries when filing an amended return.
Tax Paid With Original Return And Additional Tax Paid
Enter the tax amount paid with the original return, together with any additional tax paid afterward.
Include the applicable payments associated with the original filing.
Less: Overpayment Previously Credited To 2026
Enter the amount of the original overpayment that was previously applied toward 2026 estimated tax.
This amount must be subtracted from the payment total.
The form displays the deduction in parentheses.
Less: Refund From Original Return And Additional Refunds
Enter the amount of any refund issued from the original return and any additional refunds received.
Subtract these refunds from the total payments.
The form displays this amount in parentheses.
Total Net Payments To Schedule A, Line 10
Calculate the total net payments after accounting for all applicable payment entries and deductions.
Enter the resulting amount on Schedule A, line 10.
Verify that the amount agrees with the payment records and any applicable amended return adjustments.
Schedule D: Alaska Tax Computation
Schedule D calculates the Alaska income tax using the taxable income reported on Schedule A.
The form states that the applicable tax rate table is contained in the instructions.
Line 1: Alaska Taxable Income From Schedule A, Line 3
Transfer the Alaska taxable income calculated on Schedule A, line 3.
Use the same amount without changing the calculation.
Line 2: Tax
Calculate the Alaska income tax using the applicable Alaska Tax Rate Table.
Enter the resulting tax amount on line 2.
You must also transfer this amount to Schedule A, line 4.
The tax rate table is not printed on Schedule D itself, so use the applicable 2025 tax instructions to determine the correct amount.
Schedule E: Other Taxes
Schedule E calculates additional taxes that may apply to the corporation.
It includes alternative minimum tax, base erosion and anti-abuse tax, personal holding company tax, tax on early cessation of operations for an LNG storage facility, and other applicable taxes.
Alternative Minimum Tax
Line 1a: Alternative Minimum Tax From Federal Form 4626
Enter the alternative minimum tax amount reported on federal Form 4626.
Use the corresponding federal calculation to obtain the amount.
Line 1b: Multiply Line 1a By 18%
Multiply the amount on line 1a by 18%.
Calculation:
Line 1b = Line 1a × 18%
Enter the result.
Line 1c: Apportionment Factor From Schedule I, Line 14
Transfer the Alaska apportionment factor calculated on Schedule I, line 14.
Use the same factor in this calculation.
Line 1d: Multiply Line 1b By Line 1c
Multiply the amount on line 1b by the apportionment factor on line 1c.
Calculation:
Line 1d = Line 1b × Line 1c
Enter the resulting amount.
Base Erosion And Anti-Abuse Tax
Line 2a: Base Erosion And Anti-Abuse Tax From Federal Form 8991
Enter the applicable Base Erosion and Anti-Abuse Tax (BEAT) amount from federal Form 8991.
Line 2b: Apportionment Factor From Schedule I, Line 14
Transfer the apportionment factor from Schedule I, line 14.
Line 2c: Multiply Line 2a By Line 2b
Multiply the BEAT amount on line 2a by the apportionment factor on line 2b.
Calculation:
Line 2c = Line 2a × Line 2b
Enter the result.
Line 3: Add Lines 1d And 2c
Add the apportioned alternative minimum tax on line 1d and the apportioned BEAT on line 2c.
Enter the combined amount.
Other Corporate Taxes
Line 4: Personal Holding Company Tax
Enter any applicable personal holding company tax.
The form directs taxpayers to the instructions for the calculation.
This line is relevant when the corporation is subject to the personal holding company tax.
Line 5: Tax On Early Cessation Of Operations – LNG Storage Facility
Enter any applicable tax resulting from the early cessation of operations of an LNG storage facility.
Use the applicable instructions to determine the amount.
Line 6: Other Taxes
Enter other applicable taxes not already included on the preceding lines.
Use the instructions to determine which taxes belong on this line.
Line 7: Total Other Taxes
Add lines 3 through 6.
Calculation:
Line 7 = Line 3 + Line 4 + Line 5 + Line 6
Enter the total on this line.
You must also transfer the amount to Schedule A, line 5.
Page 4: Schedule G – Computation Of Alaska Income
Schedule G calculates the corporation’s Alaska taxable income or loss before net operating loss adjustments.
It starts with federal taxable income and applies combined reporting adjustments, additions, subtractions, apportionment, and Alaska-specific items.
Complete the applicable entries carefully because the final amount on line 11 transfers directly to Schedule A, line 1.
Federal Taxable Income And Combined Reporting Adjustments
Line 1: Federal Taxable Income (Loss)
Enter the corporation’s federal taxable income or loss.
Use the applicable federal corporate income tax return and follow the Alaska instructions for determining the amount to report.
This amount is the starting point for the Alaska income calculation.
Line 2a: Federal Taxable Income (Loss) Of Domestic Corporations Not Included In Line 1
Enter the federal taxable income or loss of domestic corporations included in the applicable combined reporting calculation but not already included on line 1.
Line 2b: Foreign Corporations
Enter the applicable federal taxable income or loss of foreign corporations included in the combined reporting calculation.
Line 2c: Federal Taxable (Income) Loss Of Non-Unitary Corporations
Enter the applicable federal taxable income or loss of non-unitary corporations as required by the combined reporting calculation.
Line 2d: Intercompany Eliminations
Enter the applicable intercompany eliminations.
Use the Alaska combined reporting instructions to determine the amounts that must be eliminated.
Line 2e: Total Adjustments For Combined Reporting
Add lines 2a through 2d.
Calculation:
Line 2e = Line 2a + Line 2b + Line 2c + Line 2d
Enter the total combined reporting adjustments.
Additions
This section identifies amounts that must be added to the federal taxable income calculation when determining Alaska income.
Line 3a: Taxes Based On Or Measured By Net Income
Enter applicable taxes based on or measured by net income that must be added back under the Alaska tax calculation.
Line 3b: Federal Charitable Contributions From Federal Form 1120, Line 19
Enter the federal charitable contribution deduction reported on federal Form 1120, line 19.
This amount is added back here because the Alaska charitable contribution deduction is calculated separately on Schedule K.
Line 3c: Net Section 1231 Losses From Federal Form 4797, Line 11
Enter the net Section 1231 loss reported on federal Form 4797, line 11.
Use the corresponding federal amount.
Line 3d: Intangible Drilling And Development Costs Expensed For Federal Purposes
Enter the applicable intangible drilling and development costs that were deducted as expenses for federal tax purposes.
Line 3e: Percentage Depletion Deducted For Federal Purposes
Enter the percentage depletion amount deducted when calculating federal taxable income.
Line 3f: Federal Depreciation
Enter the applicable federal depreciation deduction.
Line 3g: Expenses Incurred To Produce Non-Business Income
Enter expenses incurred to produce non-business income.
These expenses are identified separately for the Alaska income calculation.
Line 3h: Oil And Gas Service Industry Expenditures
Enter the applicable oil and gas service industry expenditures.
The form specifically directs taxpayers to transfer the amount from Form 6327, line 2.
Line 3i: Other Additions
Enter other applicable additions that are not covered by the preceding lines.
Attach a separate supporting schedule explaining the amounts included.
Line 3j: Total Additions
Add lines 3a through 3i.
Calculation:
Line 3j = Lines 3a + 3b + 3c + 3d + 3e + 3f + 3g + 3h + 3i
Enter the total additions.
Line 4: Total
Add line 1, line 2e, and line 3j.
Calculation:
Line 4 = Line 1 + Line 2e + Line 3j
This amount represents federal taxable income or loss after the combined reporting adjustments and additions.
Subtractions
The next section identifies amounts that must be subtracted when determining Alaska apportionable business income.
Line 5a: Intangible Drilling Costs Allowable
Enter the applicable intangible drilling costs allowable under the Alaska tax calculation.
This amount is used to adjust the federal income calculation.
Line 5b: Cost Depletion
Enter the applicable cost depletion amount.
Use the relevant depletion records to determine the amount.
Line 5c: Depreciation Allowable
Enter the applicable depreciation amount allowable for Alaska purposes.
Line 5d: Interest From Obligations Of The U.S. Government
Enter qualifying interest income from obligations of the United States government.
Line 5e: Intercompany Dividends
Enter applicable intercompany dividends included in the federal income calculation that must be subtracted.
Line 5f: Section 78 Gross-Up Dividends
Enter the applicable Section 78 gross-up dividend amount.
Line 5g: Federal Form 1120, Line 8 Capital Gain Income
Enter the capital gain income reported on federal Form 1120, line 8.
Line 5h: Non-Recaptured Section 1231 Losses From Prior Years
Enter applicable non-recaptured Section 1231 losses from prior years.
Transfer the amount from federal Form 4797, line 12.
Line 5i: Non-Business Income
Enter applicable non-business income that must be subtracted from apportionable business income.
Attach a supporting schedule showing the non-business income included.
Line 5j: Other Subtractions
Enter any other applicable subtractions that are not covered by lines 5a through 5i.
Attach a separate supporting schedule explaining the amounts.
Line 5k: Total Subtractions
Add lines 5a through 5j.
Calculation:
Line 5k = Lines 5a + 5b + 5c + 5d + 5e + 5f + 5g + 5h + 5i + 5j
Enter the total subtractions.
Apportionable Business Income
Line 6: Apportionable Business Income (Loss)
Subtract line 5k from line 4.
Calculation:
Line 6 = Line 4 − Line 5k
Enter the resulting apportionable business income or loss.
Line 7: Apportionment Factor From Schedule I, Line 14
Transfer the apportionment factor calculated on Schedule I, line 14.
This factor determines the portion of business income attributable to Alaska.
Line 8: Income (Loss) Apportioned To Alaska
Multiply line 6 by line 7.
Calculation:
Line 8 = Line 6 × Line 7
Enter the amount of business income or loss apportioned to Alaska.
Line 9: Non-Business Income (Loss) Net Of Expenses Allocable To Alaska
Enter the corporation’s non-business income or loss attributable to Alaska after applicable expenses.
Attach a supporting schedule showing the income and related expenses included in this calculation.
Alaska-Specific Items
Line 10a: Alaska Capital And Section 1231 Gain (Loss) From Schedule J, Line 20
Transfer the Alaska capital and Section 1231 gain or loss calculated on Schedule J, line 20.
Line 10b: Alaska Charitable Contribution Deduction From Schedule K, Line 10
Transfer the Alaska charitable contribution deduction calculated on Schedule K, line 10.
The form displays this amount in parentheses because it reduces the income calculation.
Line 10c: Alaska Dividends-Received Deduction
Enter the applicable Alaska dividends-received deduction.
Use Schedule L to calculate the dividends-received deduction and follow the applicable instructions for the amount reported here.
The form displays this deduction in parentheses.
Line 10d: Total Alaska Items
Add lines 10a through 10c.
Include the applicable gains, losses, and deductions using the correct positive or negative amounts.
Enter the resulting total.
Line 11: Alaska Taxable Income (Loss) Before Net Operating Loss
Add lines 8, 9, and 10d.
Calculation:
Line 11 = Line 8 + Line 9 + Line 10d
Enter the result on this line.
You must also transfer this amount to Schedule A, line 1.
Page 5: Schedule I – Apportionment Factor
Schedule I calculates the corporation’s Alaska apportionment factor.
The schedule uses property, extraction, and sales information to determine the applicable percentage of business income attributable to Alaska.
The form provides three separate factor sections and special instructions for oil and gas producing and transportation companies.
Business Activity Checkboxes
Mark all applicable boxes at the top of Schedule I.
Taxpayer Produces Oil Or Gas In Alaska
Select this checkbox if the corporation produces oil or gas in Alaska.
Taxpayer Transports Oil Or Gas In Alaska
Select this checkbox if the corporation transports oil or gas in Alaska.
Attorney General’s Opinion Dated 10/20/99 Applies
Mark this checkbox if the referenced Attorney General’s opinion concerning factor relief for certain taxpayers applies to the corporation.
Use the applicable instructions to determine whether the corporation qualifies.
Property Within Alaska
This section collects information about property located within Alaska.
The table provides five rows for reporting the applicable corporations and property amounts.
Lines 1a–1e: Property Within Alaska
For each applicable corporation, complete the following columns:
- Column A: EIN – Enter the corporation’s Employer Identification Number.
- Column B: Name – Enter the corporation’s legal name.
- Column C: Property Within Alaska – Enter the applicable property amount located within Alaska.
Use additional supporting information if the available rows are insufficient.
Line 2: Total Of Line 1, Column C
Add all applicable amounts entered in column C on lines 1a through 1e.
Enter the total Alaska property amount.
Line 3: Property Everywhere
Enter the total property amount located everywhere.
This amount is used as the denominator when calculating the property factor.
Line 4: Property Factor
Divide line 2 by line 3.
Calculation:
Property Factor = Line 2 ÷ Line 3
Enter the resulting property factor.
Extraction Within Alaska
The form provides a special instruction for oil and gas transportation companies.
Oil And Gas Transportation Companies: Skip Lines 5–8 And Go To Line 9.
If the corporation is an oil and gas transportation company, follow this instruction and proceed to the sales section.
Other applicable taxpayers should complete the extraction section as required.
Lines 5a–5e: Extraction Within Alaska
For each applicable corporation, complete the following columns:
- Column A: EIN – Enter the corporation’s Employer Identification Number.
- Column B: Name – Enter the corporation’s legal name.
- Column C: Extraction Within Alaska – Enter the applicable extraction amount within Alaska.
Line 6: Total Of Line 5, Column C
Add the extraction amounts entered in column C on lines 5a through 5e.
Enter the total extraction amount within Alaska.
Line 7: Extraction Everywhere
Enter the total extraction amount everywhere.
This amount is used to calculate the extraction factor.
Line 8: Extraction Factor
Divide line 6 by line 7.
Calculation:
Extraction Factor = Line 6 ÷ Line 7
Enter the resulting extraction factor.
Sales Within Alaska
The form provides a separate instruction for oil and gas producing companies.
Oil And Gas Producing Companies: Skip Lines 9–12 And Go To Line 13.
If the corporation is an oil and gas producing company, follow this instruction and proceed to the final apportionment calculation.
Other applicable taxpayers should complete the sales section as required.
Lines 9a–9e: Sales Within Alaska
For each applicable corporation, complete the following columns:
- Column A: EIN – Enter the corporation’s Employer Identification Number.
- Column B: Name – Enter the corporation’s legal name.
- Column C: Sales Within Alaska – Enter the applicable sales amount within Alaska.
Line 10: Total Of Line 9, Column C
Add the amounts reported in column C on lines 9a through 9e.
Enter the total sales amount within Alaska.
Line 11: Sales Everywhere
Enter the corporation’s total sales everywhere.
This amount is used to calculate the sales factor.
Line 12: Sales Factor
Divide line 10 by line 11.
Calculation:
Sales Factor = Line 10 ÷ Line 11
Enter the resulting sales factor.
Final Apportionment Factor
Line 13: Add Lines 4, 8, And 12
Add the applicable property, extraction, and sales factors.
Calculation:
Line 13 = Line 4 + Line 8 + Line 12
Follow the special skip instructions for the applicable business type.
Line 14: Apportionment Factor
Divide line 13 by 3 or 2, as applicable.
Calculation:
Line 14 = Line 13 ÷ 3, or Line 13 ÷ 2, as applicable.
Enter the resulting Alaska apportionment factor.
This factor is transferred to several other schedules, including Schedule E, Schedule G, Schedule J, Schedule K, and Schedule L.
Page 6: Schedule J – Alaska Capital And Section 1231 Gains And Losses
Schedule J calculates the Alaska portion of capital gains and losses and Section 1231 gains and losses.
It contains three columns:
- Column A: Combined – Reports the applicable combined amount.
- Column B: AK Factor – Reports the applicable Alaska factor.
- Column C: Alaska Gain Or (Loss) – Reports the amount attributable to Alaska.
Complete the appropriate columns for each line as applicable.
Section 1231 Gains And Losses
Line 1: Current Section 1231 Gains And (Losses)
Enter the corporation’s current Section 1231 gains and losses.
Use the applicable information from the corporation’s federal tax records.
If the amount in column C is a loss, also enter it on line 19.
Line 2: Alaska Net Non-Recaptured Section 1231 Losses From Prior Years
Enter the applicable Alaska net non-recaptured Section 1231 losses from prior years.
The form specifically requires this amount to be entered as a positive number.
Line 3: Adjusted Section 1231 Gain
If the amount on line 1, column C, is a gain, subtract line 2 from line 1, column C.
Do not enter an amount below zero.
Calculation:
Line 3 = Line 1, Column C − Line 2
Enter the result on line 3 and transfer it to line 15.
Line 4: Recaptured Section 1231 Loss Amount
If line 1, column C, is a gain, enter the lesser of line 1, column C, or line 2.
If line 1, column C, is not a gain, enter zero.
Transfer the applicable amount to line 19.
Short-Term Capital Gains And Losses – STCG/(L)
This section calculates current short-term capital gains and losses and determines the amount attributable to Alaska.
Line 5: Total Current STCG/(L)
Enter the corporation’s total current short-term capital gains and losses.
Use the applicable combined amount.
Line 6: Non-Business STCG/(L)
Enter the portion of short-term capital gains and losses classified as non-business income.
Line 7: Apportionable STCG/(L)
Subtract line 6 from line 5.
Calculation:
Line 7 = Line 5 − Line 6
This determines the short-term capital gain or loss subject to apportionment.
Use the applicable Alaska factor to determine the Alaska portion in the designated column.
Line 8: Non-Business STCG/(L) Allocable To Alaska
Enter the non-business short-term capital gain or loss directly allocable to Alaska.
Use the applicable supporting calculations.
Line 9: Alaska Capital Loss Carryover And Carryback Utilized
Enter the applicable Alaska capital loss carryover and carryback amounts utilized during the tax year.
The form provides separate spaces to identify the carryover and carryback amounts.
Enter the combined amount in the designated field.
The form displays this amount in parentheses because it reduces the capital gain calculation.
Line 10: Net STCG/(L)
Add line 7, column C, line 8, and line 9.
Calculation:
Line 10 = Line 7, Column C + Line 8 + Line 9
Enter the resulting net short-term capital gain or loss.
Long-Term Capital Gains And Losses – LTCG/(L)
This section calculates the corporation’s long-term capital gains and losses and the portion attributable to Alaska.
Line 11: Total Current LTCG/(L)
Enter the total current long-term capital gains and losses.
Use the applicable combined amount.
Line 12: Non-Business LTCG/(L)
Enter the portion of long-term capital gains and losses classified as non-business income.
Line 13: Apportionable LTCG/(L)
Subtract line 12 from line 11.
Calculation:
Line 13 = Line 11 − Line 12
This determines the long-term capital gain or loss subject to apportionment.
Use the applicable Alaska factor to determine the Alaska amount in the designated column.
Line 14: Non-Business LTCG/(L) Allocable To Alaska
Enter the non-business long-term capital gain or loss directly allocable to Alaska.
Use the applicable supporting calculations.
Line 15: Amount From Line 3
Transfer the amount calculated on line 3.
Use the same amount without changing the calculation.
Line 16: Net LTCG/(L)
Add line 13, column C, line 14, and line 15.
Calculation:
Line 16 = Line 13, Column C + Line 14 + Line 15
Enter the resulting net long-term capital gain or loss.
Capital Gain And Loss Summary
Line 17: Excess Net Short-Term Capital Gain Over Net Long-Term Capital Loss
Enter the excess of the net short-term capital gain on line 10 over the net long-term capital loss on line 16, if applicable.
Line 18: Excess Net Long-Term Capital Gain Over Net Short-Term Capital Loss
Enter the excess of the net long-term capital gain on line 16 over the net short-term capital loss on line 10, if applicable.
Line 19: Section 1231 Loss Or Recaptured Amount
If line 1, column C, is a loss, enter that loss here.
If line 1, column C, is not a loss, enter the amount from line 4.
This line brings the applicable Section 1231 loss or recaptured amount into the final calculation.
Line 20: Alaska Capital And Section 1231 Gain (Loss)
Add lines 17 through 19.
Calculation:
Line 20 = Line 17 + Line 18 + Line 19
Enter the result on this line.
You must also transfer this amount to Schedule G, line 10a.
Schedule K: Charitable Contribution Deduction
Schedule K calculates the corporation’s allowable Alaska charitable contribution deduction.
It accounts for current charitable contributions, education credit contributions, the Alaska apportionment factor, prior-year carryforwards, and the deduction limitation.
Line 1: Current Charitable Contributions
Enter the corporation’s current charitable contributions for the tax year.
Use the applicable contribution records to determine the amount.
Line 2: Education Credit Contributions From Form 6310
Enter the applicable education credit contributions from Form 6310.
Transfer the amount from the supporting form.
Line 3: Subtract Line 2 From Line 1
Subtract the education credit contributions on line 2 from the current charitable contributions on line 1.
Calculation:
Line 3 = Line 1 − Line 2
Enter the remaining charitable contribution amount.
Line 4: Apportionment Factor From Schedule I, Line 14
Transfer the Alaska apportionment factor from Schedule I, line 14.
Line 5: Current Alaska Charitable Contributions
Multiply line 3 by line 4.
Calculation:
Line 5 = Line 3 × Line 4
Enter the resulting current Alaska charitable contribution amount.
Line 6: Alaska Charitable Contribution Carryover From Form 6385, Line 18
Enter the applicable Alaska charitable contribution carryover from Form 6385, line 18.
Transfer the amount from the supporting form.
Line 7: Total Charitable Contributions Available
Add lines 5 and 6.
Calculation:
Line 7 = Line 5 + Line 6
Enter the total available charitable contribution amount.
Line 8: Taxable Income For Deduction Limitation Purposes
Enter the taxable income amount used to determine the charitable contribution deduction limitation.
The form refers taxpayers to the applicable instructions for this calculation.
Line 9: Multiply Line 8 By 10%
Multiply the amount on line 8 by 10%.
Calculation:
Line 9 = Line 8 × 10%
Enter the resulting deduction limitation.
Line 10: Alaska Charitable Contribution Deduction
Enter the lesser of line 7 or line 9.
Compare the total available charitable contributions with the deduction limitation and use the smaller amount.
You must also transfer this amount to Schedule G, line 10b.
Page 7: Schedule L – Alaska Dividends-Received Deduction (DRD)
Schedule L calculates the Alaska dividends-received deduction.
It identifies total dividend income, removes dividends that are not eligible for the deduction, applies the Alaska apportionment factor, and calculates the applicable deduction percentages.
Dividend Income And Eligibility
Line 1: Dividend Income Included In Combined Income
Enter the total dividend income included in the corporation’s combined income.
Use the applicable combined income records.
Line 2a: Intercompany Dividends From Schedule G, Line 5e
Enter the intercompany dividend amount reported on Schedule G, line 5e.
The form identifies these dividends as not eligible for the dividends-received deduction.
Line 2b: Section 78 Gross-Up Dividends From Schedule G, Line 5f
Enter the Section 78 gross-up dividend amount reported on Schedule G, line 5f.
This amount is also treated as not eligible for the deduction.
Line 2c: Dividends Subtracted On Schedule G, Line 5i As Non-Business Income
Enter dividends included in the non-business income amount subtracted on Schedule G, line 5i.
These dividends are not eligible for the dividends-received deduction under this calculation.
Line 2d: Total Dividends Not Eligible For DRD
Add lines 2a, 2b, and 2c.
Calculation:
Line 2d = Line 2a + Line 2b + Line 2c
Enter the total dividends excluded from the deduction.
Line 3: Total Dividends Eligible For DRD
Subtract line 2d from line 1.
Calculation:
Line 3 = Line 1 − Line 2d
Enter the remaining dividend amount eligible for the dividends-received deduction.
Line 4: Apportionment Factor From Schedule I, Line 14
Transfer the Alaska apportionment factor from Schedule I, line 14.
Line 5: Apportioned Dividends
Multiply line 3 by line 4.
Calculation:
Line 5 = Line 3 × Line 4
Enter the dividend amount apportioned to Alaska.
Line 6: Dividends Allocable To Alaska Included On Schedule G, Line 9
Enter the dividends directly allocable to Alaska that are included in Schedule G, line 9.
Use the corresponding non-business income calculation.
Line 7: Total Dividends Included In Taxable Income
Add lines 5 and 6.
Calculation:
Line 7 = Line 5 + Line 6
Enter the total dividends included in Alaska taxable income for this deduction calculation.
Dividends-Received Deduction Calculation
The bottom portion of Schedule L contains a table with three columns:
- Column A: Apportioned Dividends
- Column B: Percentage
- Column C: DRD (A Times B)
For each category, enter the applicable apportioned dividend amount in column A, apply the appropriate deduction percentage in column B, and calculate the deduction in column C.
Line 8a: Dividends Qualifying For 100% Deduction
Enter the apportioned dividend amount that qualifies for the 100% deduction.
The form provides the 100% percentage in column B.
Multiply column A by 100% and enter the resulting deduction in column C.
Line 8b: Dividends Qualifying For 65% Deduction
Enter the apportioned dividend amount qualifying for the 65% deduction.
The form provides the 65% percentage in column B.
Multiply column A by 65% and enter the resulting deduction in column C.
Line 8c: Dividends Qualifying For 50% Deduction
Enter the apportioned dividend amount qualifying for the 50% deduction.
The form provides the 50% percentage in column B.
Multiply column A by 50% and enter the resulting deduction in column C.
Line 8d: Dividends Qualifying For 26.7% Deduction
Enter the apportioned dividend amount qualifying for the 26.7% deduction.
The form provides the 26.7% percentage in column B.
Multiply column A by 26.7% and enter the resulting deduction in column C.
Line 8e: Dividends Qualifying For 23.3% Deduction
Enter the apportioned dividend amount qualifying for the 23.3% deduction.
The form provides the 23.3% percentage in column B.
Multiply column A by 23.3% and enter the resulting deduction in column C.
Line 8f: Other Dividends, If Applicable
Enter any other applicable dividend amount qualifying for a different deduction percentage.
Enter the applicable percentage in column B.
Multiply the amount in column A by the percentage in column B and enter the result in column C.
Line 9: Tentative Dividends-Received Deduction
Add the deduction amounts in column C from lines 8a through 8f.
Calculation:
Line 9 = Line 8a, Column C + Line 8b, Column C + Line 8c, Column C + Line 8d, Column C + Line 8e, Column C + Line 8f, Column C
Enter the tentative dividends-received deduction.
Use the applicable instructions to determine the final amount reported as the Alaska dividends-received deduction on Schedule G, line 10c.
Final Review Before Filing
Before submitting Alaska Form 6100, review the entire return and verify that every applicable schedule, calculation, and supporting document is complete.
Use the following checklist to reduce common filing errors.
Business Identification And Return Information
- Verify the corporation’s EIN and NAICS code.
- Enter the correct legal business name.
- Complete the contact person’s name and title.
- Verify the mailing address, city, state, and ZIP code.
- Mark the new address checkbox if applicable.
- Enter the contact email, telephone number, and fax number.
- Select all applicable return information checkboxes.
- Attach Form 1120S if the S Corporation checkbox is selected.
- Complete the additional amended return questions when applicable.
- Verify the fiscal year beginning and ending dates if the corporation does not use the calendar year.
Schedule A: Net Income Tax Summary
- Transfer Alaska income or loss from Schedule G, line 11.
- Report the applicable Alaska NOL utilization on line 2.
- Calculate Alaska taxable income on line 3.
- Transfer Alaska income tax from Schedule D, line 2.
- Transfer other taxes from Schedule E, line 7.
- Verify total tax on line 6.
- Report applicable Alaska incentive credits.
- Report applicable federal-based credits.
- Calculate net Alaska income tax on line 9.
- Attach Form 6220 if line 9 exceeds $500.
- Transfer net payments from Schedule C.
- Report any applicable prior minimum tax credit.
- Calculate the tax due or overpayment.
- Verify any estimated tax penalty.
- Complete the 2026 estimated tax credit and refund calculations when applicable.
Schedule B: Alaska Taxpayer Information
- List all additional corporations included in the Alaska consolidated return.
- Enter each corporation’s name and address.
- Complete the applicable property, extraction, and sales factor checkboxes.
- Verify each corporation’s EIN and NAICS code.
- Mark the Public Law 86-272 checkbox where applicable.
- Provide federal consolidated group parent information when required.
- Identify a predecessor business if the corporation is a successor.
- Explain any difference between the current and prior-year business name or EIN.
Schedule C: Tax Payment Record
- Enter the dates and amounts of all four estimated payments.
- Calculate total estimated tax payments.
- Report any payment made with an extension.
- Include applicable prior-year overpayments.
- Subtract applicable Quick Refund amounts from Form 6230.
- Complete amended return payment adjustments when applicable.
- Calculate total net payments.
- Transfer the correct amount to Schedule A, line 10.
Schedule D: Alaska Tax Computation
- Transfer taxable income from Schedule A, line 3.
- Use the applicable Alaska Tax Rate Table.
- Enter the calculated tax on line 2.
- Transfer the result to Schedule A, line 4.
Schedule E: Other Taxes
- Verify the federal alternative minimum tax amount from Form 4626.
- Multiply line 1a by 18%.
- Transfer the apportionment factor from Schedule I, line 14.
- Calculate the apportioned alternative minimum tax.
- Enter the BEAT amount from Form 8991 when applicable.
- Calculate the apportioned BEAT amount.
- Calculate the total on line 3.
- Report personal holding company tax when applicable.
- Report tax on early cessation of LNG storage facility operations when applicable.
- Include other applicable taxes.
- Transfer the total from line 7 to Schedule A, line 5.
Schedule G: Computation Of Alaska Income
- Verify federal taxable income or loss.
- Complete combined reporting adjustments when applicable.
- Include all required additions on lines 3a through 3i.
- Verify the total additions on line 3j.
- Calculate the total on line 4.
- Include all applicable subtractions on lines 5a through 5j.
- Verify the total subtractions on line 5k.
- Calculate apportionable business income or loss.
- Transfer the correct apportionment factor from Schedule I.
- Calculate income or loss apportioned to Alaska.
- Report applicable non-business income or loss.
- Transfer Alaska capital and Section 1231 gains or losses from Schedule J.
- Transfer the charitable contribution deduction from Schedule K.
- Include the applicable dividends-received deduction from Schedule L.
- Verify the final amount on line 11.
- Transfer line 11 to Schedule A, line 1.
Schedule I: Apportionment Factor
- Mark all applicable oil and gas business activity checkboxes.
- Complete the Alaska property information.
- Calculate the property factor.
- Complete extraction information when required.
- Calculate the extraction factor when applicable.
- Complete Alaska sales information when required.
- Calculate the sales factor when applicable.
- Follow the special instructions for oil and gas producing and transportation companies.
- Calculate the combined factor on line 13.
- Divide by the applicable number on line 14.
- Verify the final Alaska apportionment factor.
Schedule J: Capital And Section 1231 Gains And Losses
- Report current Section 1231 gains and losses.
- Include applicable prior-year non-recaptured Section 1231 losses.
- Calculate the adjusted Section 1231 gain.
- Verify the Section 1231 recaptured amount.
- Report current short-term capital gains and losses.
- Separate non-business and apportionable short-term amounts.
- Report Alaska capital loss carryovers and carrybacks used.
- Calculate net short-term capital gains or losses.
- Report current long-term capital gains and losses.
- Separate non-business and apportionable long-term amounts.
- Calculate net long-term capital gains or losses.
- Complete the capital gain and loss summary.
- Transfer the final amount on line 20 to Schedule G, line 10a.
Schedule K: Charitable Contribution Deduction
- Report current charitable contributions.
- Subtract education credit contributions from Form 6310.
- Transfer the apportionment factor from Schedule I.
- Calculate current Alaska charitable contributions.
- Include applicable carryforward amounts from Form 6385.
- Calculate the total available charitable contribution amount.
- Determine taxable income for deduction limitation purposes.
- Calculate the 10% limitation.
- Enter the lesser of line 7 or line 9 on line 10.
- Transfer the deduction to Schedule G, line 10b.
Schedule L: Dividends-Received Deduction
- Enter dividend income included in combined income.
- Identify intercompany dividends.
- Include applicable Section 78 gross-up dividends.
- Identify dividends subtracted as non-business income.
- Calculate total dividends not eligible for the deduction.
- Determine total dividends eligible for the deduction.
- Transfer the apportionment factor from Schedule I.
- Calculate apportioned dividends.
- Include dividends directly allocable to Alaska.
- Calculate total dividends included in taxable income.
- Classify dividends under the applicable deduction percentages.
- Complete columns A, B, and C for lines 8a through 8f.
- Calculate the tentative dividends-received deduction on line 9.
- Verify the applicable amount reported on Schedule G, line 10c.
Signatures And Final Submission
- Make sure the authorized corporate officer signs the return.
- Enter the officer’s signature date and title.
- Complete the paid preparer information when applicable.
- Mark the DOR preparer authorization checkbox if permission is being granted.
- Attach the applicable federal forms and supporting schedules.
- Attach Form 6220 when required.
- Verify that all transferred amounts agree across the schedules.
- Review the current Alaska Department of Revenue filing instructions for the correct submission method and deadline.
- Keep a complete copy of the filed return and supporting records.
Completing Form 6100 accurately requires careful coordination between federal taxable income, Alaska-specific adjustments, business apportionment, deductions, credits, and tax payments. Review every applicable schedule before finalizing the return, verify all amounts transferred between schedules, and make sure the final Alaska tax calculation agrees with the corporation’s supporting records.