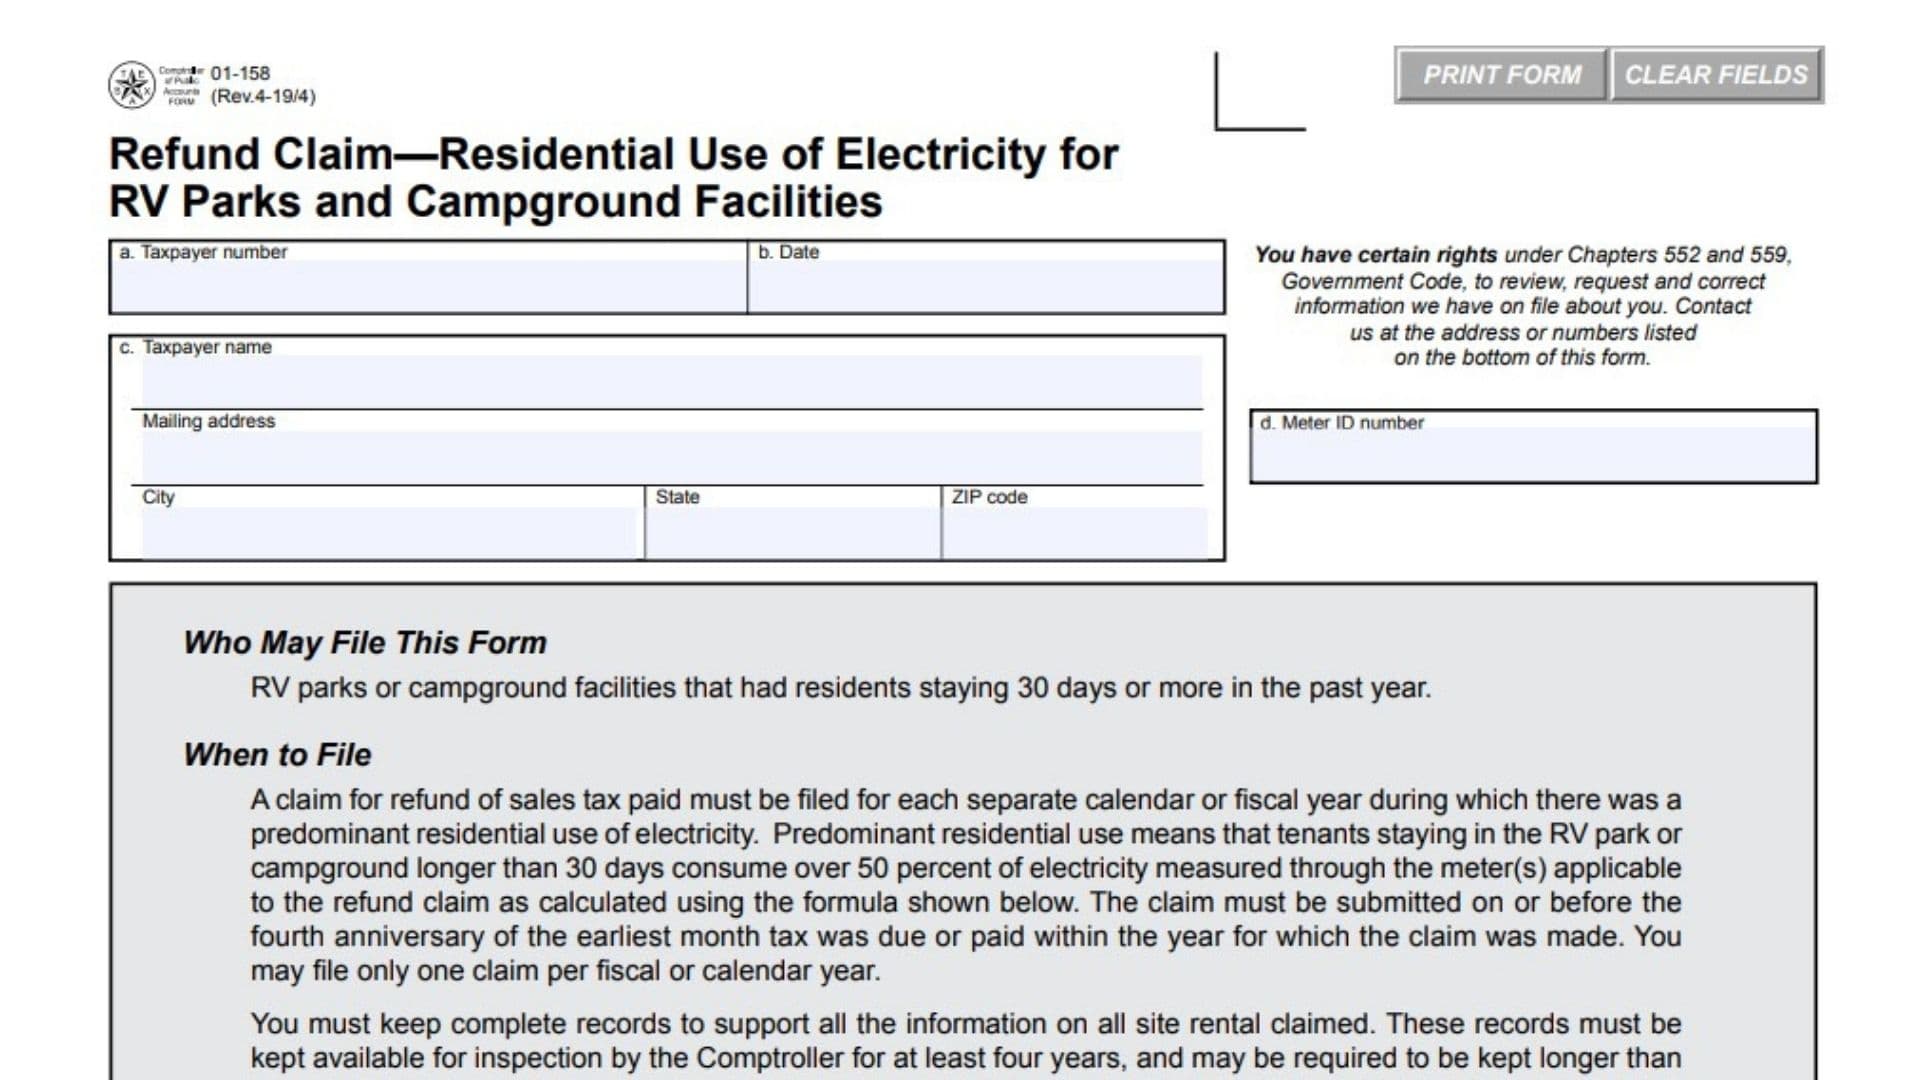
Texas Form 01-158, Refund Claim—Residential Use of Electricity for RV Parks and Campground Facilities, is used by qualifying RV parks and campground facilities to claim a refund of sales tax paid on electricity used for predominantly residential purposes. The form is intended for facilities that had residents staying for at least 30 days during the applicable period and allows the facility to demonstrate whether more than 50 percent of the applicable electricity use was associated with qualifying residential stays. To determine eligibility, the facility identifies the period being claimed, calculates the total qualifying residential rental days, compares those days with the total rental days for the facility, and reports the resulting percentage of residential use. A facility qualifies for this refund based on predominant residential use when tenants who stayed longer than 30 days accounted for more than 50 percent of the applicable electricity use measured through the meter or meters covered by the claim, as determined using the rental-day calculation on the form. A separate refund claim must be filed for each calendar or fiscal year in which the facility had predominant residential use. The claim is subject to a four-year limitation period, so it must be submitted no later than the fourth anniversary of the earliest month in the applicable year when the tax was due or paid. Only one claim may be filed for each fiscal or calendar year. The taxpayer must also retain complete records supporting the site rental information used to prepare the claim because those records must remain available for inspection for at least four years and may need to be retained longer when tax, penalties, interest, an administrative hearing, or a judicial proceeding is involved. 01-158
How To File Form 01-158
A completed Form 01-158 must be signed and submitted with the amount being claimed, the reason the refund is due, and any documentation required to support the claim.
Refund requests and supporting documentation should be sent to:
Comptroller of Public Accounts
ATTN: Sales and Motor Vehicle Tax Refund Section
111 E. 17th Street
Austin, TX 78774-0100
The form also provides the email address refund.request@cpa.texas.gov for the Sales and Motor Vehicle Tax Refund Section.
Before completing the form, prepare the records needed to establish the facility’s qualifying residential rental days and total rental days for the period being claimed. You should also have the taxpayer information, applicable meter identification number, beginning and ending dates, and information needed to support the amount of sales tax refund being requested.
The claim must be filed within the applicable four-year limitation period. A claim that is submitted after the limitation period has expired is not eligible for a refund.
Who May File Form 01-158?
Form 01-158 is intended for an RV park or campground facility that had residents staying for 30 days or more during the past year.
The facility must also satisfy the predominant residential-use requirement for the year being claimed.
Predominant Residential Use Requirement
The facility qualifies when tenants who stay longer than 30 days account for more than 50 percent of the applicable electricity use.
The form uses rental-day information to calculate the percentage of residential use. The number of qualifying residential rental days is divided by the total number of rental days for the facility.
Because the requirement is over 50 percent, a result of exactly 50 percent does not satisfy the stated threshold.
When To File Form 01-158
A separate refund claim must be filed for each calendar year or fiscal year in which the facility had predominant residential use of electricity.
Four-Year Filing Deadline
The claim must be submitted no later than the fourth anniversary of the earliest month in the applicable year when the tax was due or paid.
The four-year limitation period is important because the form states that a refund is available only when the limitation period has not expired.
One Claim Per Year
Only one refund claim may be filed for each fiscal or calendar year.
Recordkeeping Requirements
Supporting Site Rental Records
Keep complete records supporting all of the site rental information reported for the claim.
The records must be available for inspection for at least four years.
The required retention period may extend beyond four years when tax, penalties, or interest may still be assessed, collected, or refunded, or when an administrative hearing or judicial proceeding is pending.
How To Complete Form 01-158
Taxpayer Identification Information
The top section identifies the taxpayer and the electricity meter associated with the refund claim.
Item a: Taxpayer Number
Enter the taxpayer number associated with the facility or reporting taxpayer.
Check the number carefully to make sure the claim is associated with the correct taxpayer account.
Item b: Date
Enter the date associated with preparation or submission of the refund claim.
Use the date on which the form is being completed or signed as appropriate.
Item c: Taxpayer Name
Enter the taxpayer’s name.
Use the legal taxpayer name associated with the refund claim.
Mailing Address
Enter the taxpayer’s complete mailing address.
City
Enter the city for the taxpayer’s mailing address.
State
Enter the state for the taxpayer’s mailing address.
ZIP Code
Enter the ZIP code for the taxpayer’s mailing address.
Item d: Meter ID Number
Enter the identification number of the electricity meter associated with the refund claim.
If the claim involves the meter or meters applicable to the residential-use calculation, make sure the meter identification information corresponds to the electricity usage being used to support the claim.
Eligibility Question
Question 1: Residential Stay Requirement
Question 1: Do You Own Or Represent A Campground Facility With Residents Staying At Least 30 Days?
Check Yes if you own or represent an RV park or campground facility that has residents who have stayed at the facility for at least 30 days.
Check No if the facility does not have residents who have resided there for at least 30 days.
If the answer is No, the form specifically states that the facility is not eligible for a refund based on residential use of electricity.
Yes Checkbox
Select this box when the 30-day residential-stay requirement is satisfied.
No Checkbox
Select this box when the requirement is not satisfied.
Reporting Entity Information
Legal Name Of Reporting Entity
Enter the legal name of the entity submitting the refund claim.
The reporting entity should be the taxpayer or organization responsible for the claim.
Texas Taxpayer Or FEI Number
Enter the Texas taxpayer number or Federal Employer Identification number requested by the form for the reporting entity.
Use the number that properly identifies the entity submitting the claim.
Claim Period
Beginning And Ending Dates
The form requires the period covered by the refund claim to be identified.
Item 2a: Begin Date
Enter the first date of the period covered by the claim.
The form requires the date to be entered in MM/DD/YY format.
For example, enter a date using two digits for the month, two digits for the day, and two digits for the year.
Item 2b: End Date
Enter the final date of the period covered by the claim.
Use the same MM/DD/YY format required for the beginning date.
The beginning and ending dates establish the period used for the rental-day calculations in Items 3 through 5.
Residential Rental-Day Calculation
Calculating Qualifying Residential Use
Items 3, 4, and 5 work together to determine the percentage of residential use for the period identified in Items 2a and 2b.
The calculation compares qualifying residential rental days with the total rental days at the facility.
Item 3: Qualifying Residential Days
Item 3: Qualifying Residential Days
Enter the total number of site rental days associated with residents who qualify as residential stays under the form’s requirements.
The form specifically instructs the filer to include the total site rental days associated with residential stays.
This number represents the residential portion of the rental-day calculation.
Item 4: Total Rental Days At Facility
Item 4: Total Number Of Rental Days At Facility
Enter the total number of site rental days for the entire facility during the period identified in Items 2a and 2b.
This includes the total rental-day figure for the facility and provides the denominator for the residential-use percentage.
Item 5: Percentage Of Residential Use
Item 5: Percentage Of Residential Use
Calculate the percentage by dividing the amount reported in Item 3 by the amount reported in Item 4.
The basic calculation is:
Residential use percentage = Item 3 ÷ Item 4 × 100
For example, if qualifying residential rental days were 600 and total rental days were 1,000:
600 ÷ 1,000 × 100 = 60%
Because the required threshold is more than 50 percent, a result above 50 percent demonstrates predominant residential use under the rental-day calculation.
Make sure the figures used in Items 3 and 4 cover the same period shown in Items 2a and 2b.
Refund Claim Information
Amount And Basis Of Refund
Amount To Be Refunded
The refund claim must state the amount of sales tax being requested for refund.
The form’s filing instructions require the signed refund claim to state the amount to be refunded.
Make sure the amount requested is supported by the records and documentation maintained for the claim.
Basis For The Refund
The claim must explain the basis for requesting the refund.
For this form, the relevant basis is the qualifying residential use of electricity by an RV park or campground facility that meets the requirements for predominant residential use.
Supporting Documentation
Include any documentation required to substantiate the refund claim.
The supporting records should establish the information used to calculate the qualifying residential rental days, total rental days, and residential-use percentage, as well as the amount of tax being claimed for refund.
Declaration And Signature
The bottom portion of Form 01-158 contains the taxpayer’s declaration and signature information.
Print Or Type Name
Enter the printed or typed name of the individual signing the refund claim.
The name should clearly identify the person executing the claim.
Daytime Phone
Enter a daytime telephone number, including the area code, where the person responsible for the claim can be contacted.
Officer, Director, Member, Owner Or Other Authorized Agent
The person signing the form must be an officer, director, member, owner, or another person authorized to act for the reporting entity.
The signer certifies that the information contained in the form and its attachments is true and correct to the best of their knowledge and belief.
Date
Enter the date on which the authorized person signs the refund claim.
Make sure the signature date is completed before submitting the form.
Signature
The authorized individual must sign the form in the designated signature area.
An unsigned refund claim is not properly completed.
Taxpayer Information Rights
The form explains that taxpayers have certain rights under Chapters 552 and 559 of the Government Code concerning information maintained about them.
These rights include the ability to review information on file and request correction of information when appropriate.
Questions regarding these rights can be directed to the Comptroller using the contact information provided on the form.
Refund Claim Contact Information
For questions about the refund claim, the form identifies the Sales and Motor Vehicle Tax Refund Section as the appropriate contact.
Telephone
You can contact the section at:
1-800-531-5441, extension 3-4545
You can also use:
512-463-4545
The form provides:
These contacts are provided for questions concerning the refund claim process.
Where To Send Form 01-158
Send the signed refund claim together with the required supporting documentation to:
Comptroller of Public Accounts
ATTN: Sales and Motor Vehicle Tax Refund Section
111 E. 17th Street
Austin, TX 78774-0100
The form also identifies refund.request@cpa.texas.gov as the email contact for the refund section.
Final Review Before Filing
Before submitting Form 01-158, verify that:
- The taxpayer number is correct.
- The date in Item b is entered.
- The taxpayer’s legal name is correct.
- The mailing address is complete.
- The city, state, and ZIP code are correct.
- The correct meter ID number is reported.
- The facility is an RV park or campground facility.
- The facility had residents who stayed for at least 30 days.
- Question 1 is answered correctly.
- The Yes or No box accurately reflects the facility’s eligibility.
- The legal name of the reporting entity is correct.
- The Texas taxpayer number or FEI number is correct.
- The beginning date in Item 2a is entered in MM/DD/YY format.
- The ending date in Item 2b is entered in MM/DD/YY format.
- Item 3 includes the total qualifying site rental days associated with residential stays.
- Item 4 includes the total site rental days for the entire facility.
- Items 3 and 4 cover the same period.
- Item 5 is calculated by dividing Item 3 by Item 4 and converting the result to a percentage.
- The residential-use percentage is more than 50 percent when claiming the refund based on predominant residential use.
- The amount of the requested refund is stated.
- The basis for the refund is clearly established.
- Required supporting documentation is included.
- Records supporting the site rental information are being retained for at least four years.
- The claim is being filed within the applicable four-year limitation period.
- Only one claim is being filed for the applicable fiscal or calendar year.
- The printed or typed name of the authorized signer is provided.
- The daytime telephone number is complete, including the area code.
- The signer is an officer, director, member, owner, or otherwise authorized agent of the reporting entity.
- The signer has signed the declaration.
- The signature date is entered.
- The completed claim and supporting documentation are being sent to the Sales and Motor Vehicle Tax Refund Section at the required address.