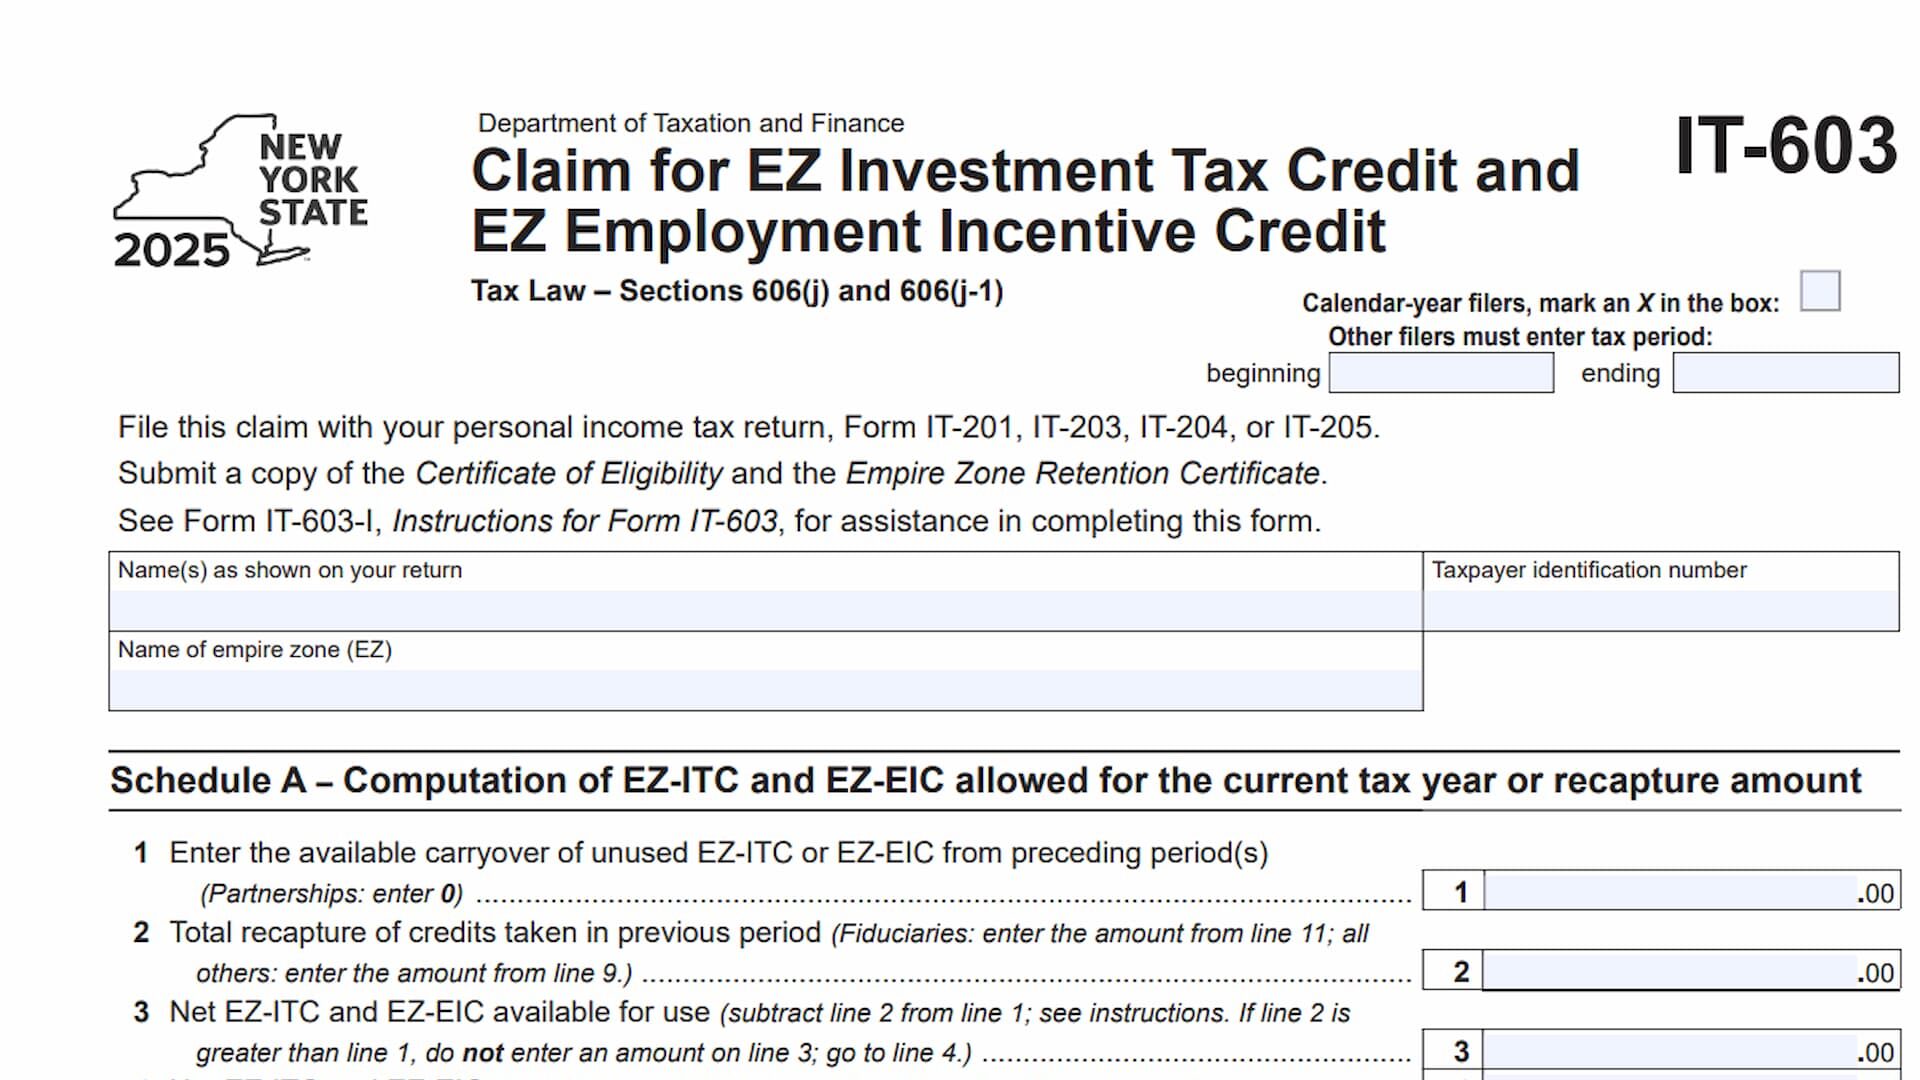
Form IT-603, Claim for EZ Investment Tax Credit and EZ Employment Incentive Credit, is a New York State tax form used to claim the Empire Zone Investment Tax Credit (EZ-ITC) and the Empire Zone Employment Incentive Credit (EZ-EIC). These credits are authorized under Sections 606(j) and 606(j-1) of the New York State Tax Law. The form allows eligible taxpayers to calculate available credits, account for credit recaptures, determine how much credit can be applied during the current tax year, and identify any unused amounts that can be carried forward.
The form is intended for taxpayers claiming these Empire Zone-related tax credits on their New York personal income tax returns. It collects identifying information, details about the applicable Empire Zone, unused credits carried over from previous periods, and information needed to calculate credit recapture amounts. It also accounts for credits received through partnerships, S corporations, estates, and trusts.
Form IT-603 contains three schedules. Schedule A calculates the EZ-ITC and EZ-EIC available for the current tax year or determines the amount subject to recapture. Schedule B provides the detailed property information and calculations needed to determine recaptured credits. Schedule C calculates how much of the available credits can be used against the taxpayer’s current-year tax liability and how much remains available for future tax periods.
Completing Form IT-603 correctly is important because the calculations determine the amount of credit that can be claimed and whether previously claimed credits must be recaptured. Taxpayers must also provide the required supporting eligibility documentation. A copy of the Certificate of Eligibility and the Empire Zone Retention Certificate must be submitted with the claim.
How To File Form IT-603
Form IT-603 must be filed with the taxpayer’s applicable New York personal income tax return. The form can be submitted with any of the following returns:
- Form IT-201
- Form IT-203
- Form IT-204
- Form IT-205
In addition to the completed IT-603, taxpayers must submit copies of both the Certificate of Eligibility and the Empire Zone Retention Certificate.
The appropriate tax period information must also be provided. Calendar-year filers should mark an X in the designated checkbox at the top of Form IT-603. Taxpayers using another tax year must enter the beginning and ending dates of their tax period.
Before completing the form, gather the following information:
- Your New York personal income tax return.
- Your name and taxpayer identification number as shown on the return.
- The name of the applicable Empire Zone (EZ).
- Your Certificate of Eligibility.
- Your Empire Zone Retention Certificate.
- Records of unused EZ-ITC and EZ-EIC credits carried forward from previous periods.
- Information about previously claimed credits that may need to be recaptured.
- Property descriptions, acquisition dates, and dates when properties ceased to qualify, where applicable.
- Supporting information for additional credit recaptures.
- Information about your share of credit addbacks received through partnerships, S corporations, estates, or trusts.
- Your tax liability before credits and the amounts of other credits applied against that liability.
For assistance with the calculations and specific eligibility requirements, consult Form IT-603-I, Instructions for Form IT-603.
How To Complete Form IT-603
Form IT-603 contains taxpayer identification fields and three schedules. Complete the applicable fields in order, using supporting documentation to determine the credit amounts and recapture calculations.
Taxpayer Information
The first section identifies the taxpayer and the applicable tax period. Enter all identifying details consistently with the information reported on your New York income tax return.
Calendar-Year Filers
If you are filing on a calendar-year basis, mark an X in the designated checkbox at the top of the form.
Taxpayers using a calendar tax year should select this option rather than entering separate beginning and ending dates.
Other Filers: Tax Period Beginning
If you use a tax period other than the calendar year, enter the starting date of your tax period in the designated field.
Other Filers: Tax Period Ending
Enter the ending date of your tax period in the corresponding field.
Make sure both dates accurately reflect the reporting period covered by the claim.
Name(s) as Shown on Your Return
Enter the taxpayer’s name exactly as it appears on the associated New York personal income tax return.
If the return includes more than one taxpayer, use the names shown on that return.
Taxpayer Identification Number
Enter the taxpayer identification number associated with the income tax return.
Make sure the number matches the identifying information reported on the applicable IT-201, IT-203, IT-204, or IT-205.
Name of Empire Zone (EZ)
Enter the name of the Empire Zone associated with the tax credit claim.
Use the appropriate zone name corresponding to the Certificate of Eligibility and the Empire Zone Retention Certificate submitted with the form.
Schedule A: Computation of EZ-ITC and EZ-EIC Allowed for the Current Tax Year or Recapture Amount
Schedule A determines the amount of EZ-ITC and EZ-EIC available for use during the current tax year or the amount that must be recaptured.
The calculation begins with unused credits carried forward from previous periods and adjusts that amount for credits that must be recaptured. Depending on the results, the schedule determines either the available credit amount or the net recapture amount.
Line 1: Available Carryover of Unused EZ-ITC or EZ-EIC
Enter the total amount of unused EZ-ITC or EZ-EIC carried forward from preceding tax periods.
Use the applicable carryover information from previous periods to determine the amount available for the current calculation.
Partnerships must enter zero on this line, as specifically indicated on the form.
Line 2: Total Recapture of Credits Taken in Previous Period
Enter the total amount of credits that must be recaptured from previous tax periods.
The amount reported depends on the type of taxpayer:
- Fiduciaries: Enter the amount from line 11.
- All other taxpayers: Enter the amount from line 9.
Use the applicable recapture calculation from Schedule B to determine the amount entered here.
Line 3: Net EZ-ITC and EZ-EIC Available for Use
Subtract the amount on line 2 from the amount on line 1.
Enter the difference on line 3 if line 1 is greater than or equal to line 2.
If line 2 is greater than line 1, do not enter an amount on line 3. Instead, proceed directly to line 4 to calculate the net recapture amount.
Line 4: Net EZ-ITC and EZ-EIC Recapture Amount
Subtract line 1 from line 2.
Enter the difference on line 4. This calculation determines the net amount of credit recapture when the amount being recaptured exceeds the available carryover.
Schedule B: Computation of Recapture of EZ-ITC and EZ-EIC
Schedule B calculates the amount of previously claimed EZ-ITC and EZ-EIC that must be recaptured.
This schedule includes a property-by-property calculation. For each applicable property, enter the relevant acquisition information, the date the property ceased to qualify, its useful life, the remaining unused life, and the amounts associated with the credits being recaptured.
The schedule contains nine columns, labeled A through I.
Property Information and Credit Calculations
Column A: Description of Property
Enter a description identifying the property associated with the credit being reviewed for recapture.
Provide enough information to distinguish the property from other assets included in the schedule.
Column B: Date Acquired
Enter the date the property was acquired.
Use the original acquisition date relevant to the credit calculation.
Column C: Date Property Ceased to Qualify
Enter the date the property ceased to meet the applicable qualification requirements.
This date is used together with the acquisition date and useful life to calculate the remaining unused life.
Column D: Life (Months)
Enter the property’s applicable life in months.
Use the relevant property-life information required for the recapture calculation.
Column E: Unused Life (Months)
Enter the number of months of the property’s life that remained unused when it ceased to qualify.
This figure is used to calculate the percentage reported in Column F.
Column F: Percentage (E ÷ D)
Divide the unused life in Column E by the total life in Column D.
Enter the resulting percentage in Column F. This percentage represents the portion of the property’s life that remained unused and is used in calculating the recaptured EZ-ITC.
Column G: EZ-ITC Allowed
Enter the applicable EZ-ITC amount allowed for the property.
Determine the amount using the calculation instructions provided for Form IT-603 and the relevant property credit information.
Column H: Recaptured EZ-ITC
Multiply the percentage in Column F by the EZ-ITC amount in Column G.
Enter the resulting recaptured EZ-ITC amount in Column H.
Column I: Recaptured EZ-EIC
Enter the recaptured EZ-EIC amount associated with the applicable property.
Use the instructions for Form IT-603 to determine the amount required in this column.
Schedule B Recapture Totals
After completing the applicable property entries, calculate the totals and additional recapture amounts.
Line 5: Recaptured EZ-ITC
Add all amounts reported in Column H.
Enter the combined total on line 5. This represents the total recaptured EZ-ITC from the properties listed in Schedule B.
Line 6: Recaptured EZ-EIC
Add all amounts reported in Column I.
Enter the combined total on line 6. This represents the total recaptured EZ-EIC associated with the listed properties.
Line 7: Additional Recapture
Enter any additional credit recapture amount required under the applicable instructions.
Consult Form IT-603-I to determine whether additional recapture applies and how the amount should be calculated.
Line 8: Partners, S Corporation Shareholders, or Beneficiaries’ Share of Addback
Enter your share of any EZ-ITC and EZ-EIC addback received through a partnership, S corporation, estate, or trust.
This line applies to taxpayers who receive an allocated share of credit addbacks from one of these entities.
Use the applicable allocation information to determine the amount reported.
Line 9: Total Recapture
Add the amounts reported on lines 5, 6, 7, and 8.
Enter the combined total on line 9.
The form provides separate instructions depending on the type of taxpayer:
- Fiduciaries must complete lines 10 and 11.
- All other taxpayers must enter the amount from line 9 on Schedule A, line 2.
Line 10: Recapture Allocated to Beneficiaries
This line is completed by fiduciaries.
Enter the portion of the total recapture amount allocated to beneficiaries.
Use the applicable allocation information to determine the amount reported.
Line 11: Fiduciary Share of Recapture
Subtract line 10 from line 9.
Enter the remaining amount on line 11. This represents the fiduciary’s share of the recapture after accounting for the portion allocated to beneficiaries.
Fiduciaries must also transfer this amount to Schedule A, line 2.
Schedule C: Computation of EZ-ITC and EZ-EIC Used and Carried Over
Schedule C determines how much of the available EZ-ITC and EZ-EIC can be used against the taxpayer’s current-year tax liability and how much remains available for future periods.
The calculation considers the available credit amount, the taxpayer’s tax due before credits, and other credits already applied against the tax liability.
Line 12: EZ-ITC and EZ-EIC Available for Use This Tax Year
Enter the amount from Schedule A, line 3.
This represents the net amount of EZ-ITC and EZ-EIC available for use during the current tax year after accounting for applicable recapture amounts.
Line 13: Tax Due Before Credits
Enter the taxpayer’s tax liability before applying credits.
Use the applicable amount from the associated New York personal income tax return and follow the specific instructions provided for this calculation.
Line 14: All Credits Applied Against Your Tax Before the EZ-ITC and EZ-EIC
Enter the total amount of other credits applied against your tax liability before the EZ-ITC and EZ-EIC.
Use the applicable credit information from your income tax return and follow the instructions for Form IT-603 when determining the amount.
Line 15: Remaining Tax After Other Credits
Subtract the amount on line 14 from the amount on line 13.
Enter the difference on line 15. This amount represents the tax remaining after accounting for credits applied before the EZ-ITC and EZ-EIC.
Line 16: EZ-ITC and EZ-EIC Used This Year
Compare the amounts on lines 12 and 15.
Enter whichever amount is smaller.
This represents the portion of the available EZ-ITC and EZ-EIC that can be used during the current tax year. The amount cannot exceed the available credit or the remaining tax liability.
Line 17: Unused EZ-ITC and EZ-EIC Available to Be Carried Forward
Subtract line 16 from line 12.
Enter the remaining amount on line 17. This represents the portion of the available EZ-ITC and EZ-EIC that was not used during the current tax year and remains available to be carried forward.
Final Review Before Filing
Before submitting Form IT-603 with your New York personal income tax return, review the following checklist to ensure that the required information, calculations, and supporting documents are complete.
- Tax year: Confirm that the correct tax period is identified. Calendar-year filers should mark the appropriate checkbox, while other filers must enter their beginning and ending dates.
- Taxpayer information: Verify that your name and taxpayer identification number match the applicable income tax return.
- Empire Zone identification: Make sure the correct Empire Zone name is entered.
- Supporting certificates: Include copies of the Certificate of Eligibility and the Empire Zone Retention Certificate.
- Correct tax return: Confirm that Form IT-603 is being filed with Form IT-201, IT-203, IT-204, or IT-205, as applicable.
- Schedule A, line 1: Verify the available carryover of unused EZ-ITC and EZ-EIC. Partnerships must enter zero.
- Schedule A, line 2: Confirm that the recapture amount comes from line 11 for fiduciaries or line 9 for all other taxpayers.
- Schedule A, lines 3 and 4: Check that the available credit and net recapture calculations are completed correctly.
- Schedule B: Review the property descriptions, acquisition dates, qualification dates, useful life, and unused life entries.
- Column F: Verify that the percentage is calculated by dividing Column E by Column D.
- Column H: Confirm that the recaptured EZ-ITC equals Column F multiplied by Column G.
- Column I: Verify that the recaptured EZ-EIC amounts are entered using the applicable instructions.
- Lines 5 and 6: Check that the recaptured EZ-ITC and EZ-EIC totals correctly add the amounts in Columns H and I, respectively.
- Line 7: Include any additional recapture required under the applicable instructions.
- Line 8: Report your applicable share of credit addbacks received through a partnership, S corporation, estate, or trust.
- Lines 9 through 11: Verify the total recapture calculation and complete the additional fiduciary calculations when applicable.
- Schedule C, line 12: Confirm that the available credit amount matches Schedule A, line 3.
- Lines 13 and 14: Verify the tax liability before credits and all credits applied before the EZ-ITC and EZ-EIC.
- Line 15: Confirm that line 14 is subtracted from line 13.
- Line 16: Make sure the amount entered is the smaller of line 12 or line 15.
- Line 17: Confirm that unused credits are calculated by subtracting line 16 from line 12.
- Additional instructions: Consult Form IT-603-I for applicable eligibility rules, recapture requirements, and calculation details not provided directly on Form IT-603.
- Final review: Check all amounts, supporting information, and identifying details before submitting the claim with your tax return.
Reviewing each schedule and ensuring that the required certificates accompany the claim can help prevent errors in the calculation and reporting of your EZ-ITC and EZ-EIC. Make sure the final amounts accurately reflect the credits available, credits recaptured, credits used, and any unused amounts carried forward.