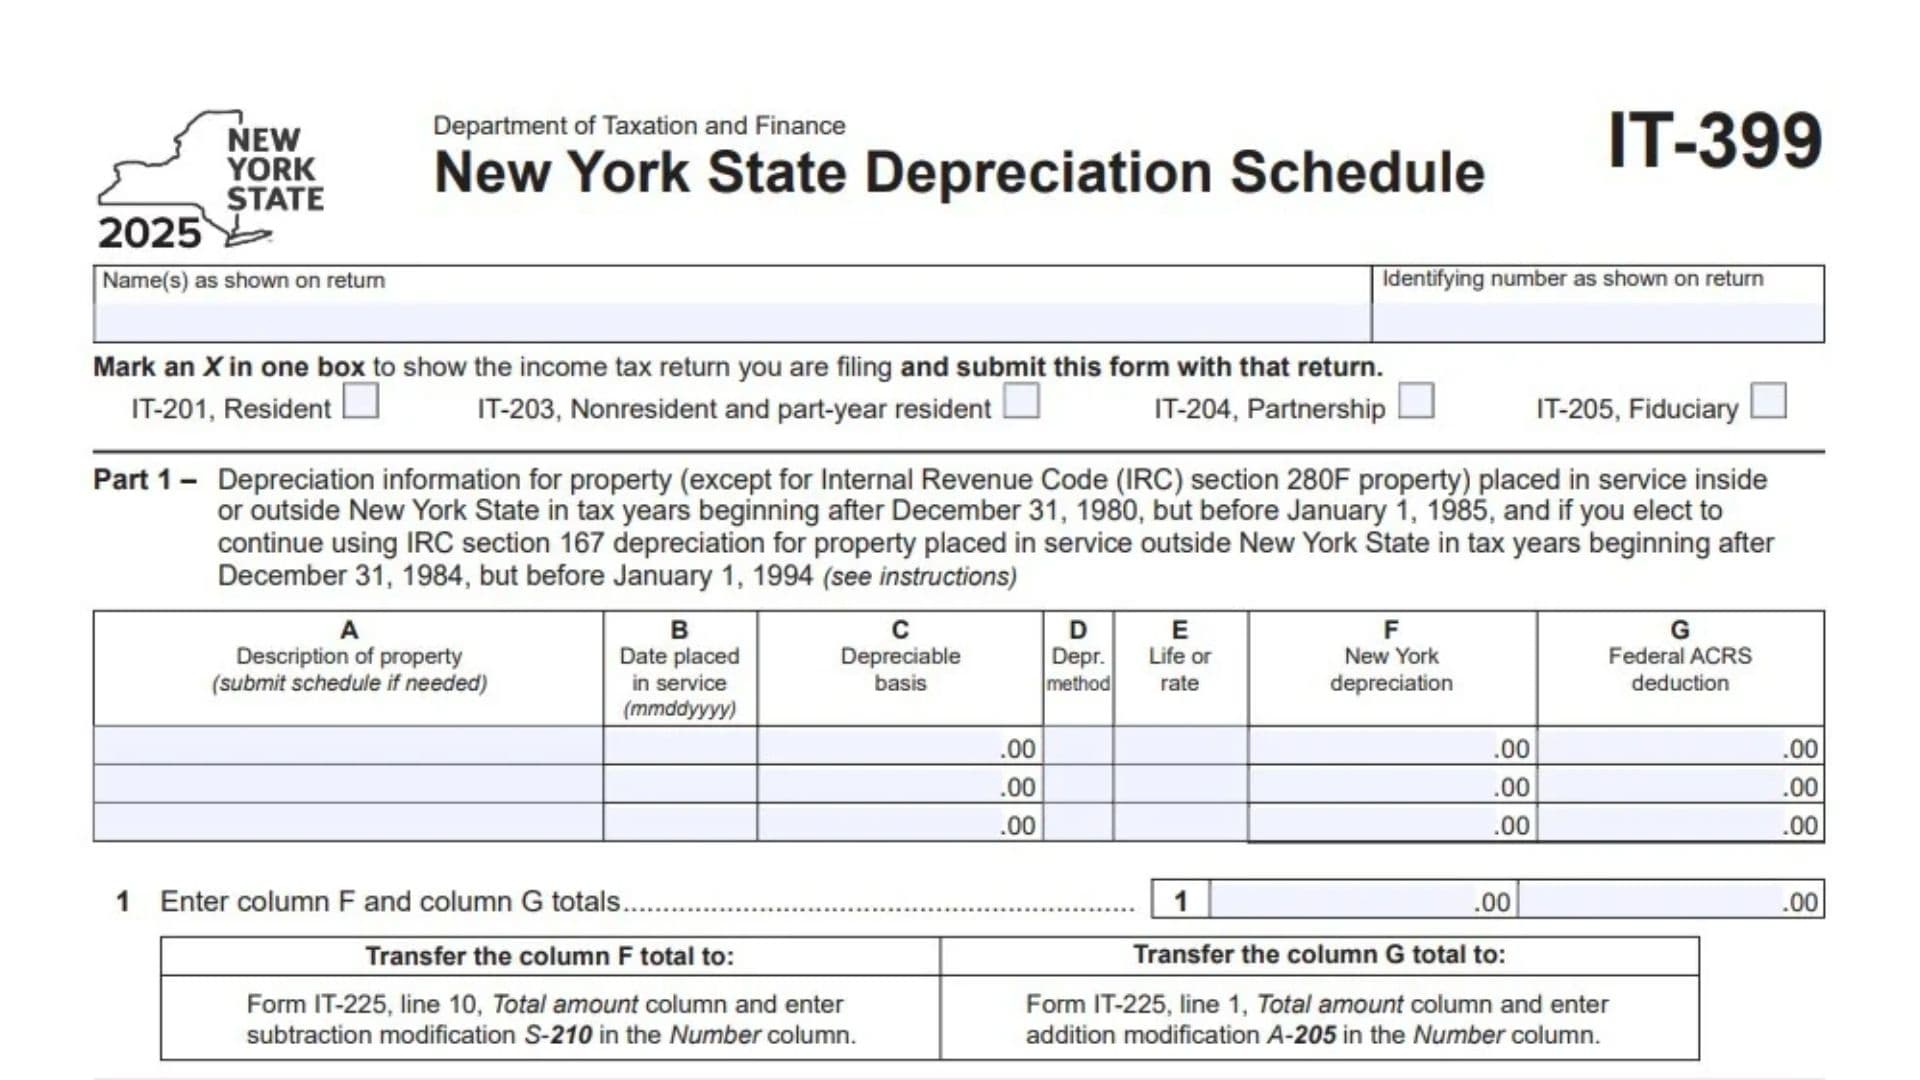
New York Form IT-399, officially known as the New York State Depreciation Schedule, is a tax form issued by the New York State Department of Taxation and Finance. It is used to calculate adjustments between New York State depreciation deductions and federal Accelerated Cost Recovery System (ACRS) depreciation for certain business and investment properties placed in service during specific historical tax years. These adjustments are necessary because New York State did not always follow the federal depreciation rules when determining the amount of depreciation taxpayers could claim. In particular, the state generally required taxpayers to calculate depreciation using methods permitted under Internal Revenue Code (IRC) Section 167 as it existed on December 31, 1980, rather than accepting the federal ACRS deduction for certain properties. Form IT-399 helps taxpayers report the difference between these depreciation amounts, including adjustments required when qualifying property is disposed of. It applies to eligible property placed in service inside or outside New York during tax years beginning after December 31, 1980, but before January 1, 1985, and certain property placed in service outside New York during tax years beginning after December 31, 1984, but before January 1, 1994. Property classified under IRC Section 280F is generally excluded from these calculations. The form collects taxpayer identification information, property descriptions, dates placed in service, depreciable basis, depreciation methods, useful lives, New York depreciation deductions, federal ACRS deductions, and disposition information. Completing Form IT-399 correctly is important because the resulting amounts may increase or decrease New York taxable income through the appropriate additions and subtractions reported on Form IT-225. The form is intended for eligible New York residents, nonresidents, part-year residents, partnerships, and fiduciaries when the relevant depreciation adjustments apply.
Who Needs to File Form IT-399?
You may need Form IT-399 if you claimed federal ACRS depreciation on qualifying property and must calculate the corresponding New York State depreciation adjustments.
The form generally applies to the following situations:
- Property placed in service inside or outside New York during tax years beginning after December 31, 1980, but before January 1, 1985.
- Property placed in service outside New York during tax years beginning after December 31, 1984, but before January 1, 1994, when the applicable New York depreciation treatment requires an adjustment.
- Qualifying property that is disposed of and requires a year-of-disposition adjustment.
- Taxpayers who elect to continue using the pre-1981 IRC Section 167 depreciation method for eligible property.
Do not use Form IT-399 to calculate depreciation for property classified under IRC Section 168(k). That property is covered by Form IT-398, New York State Depreciation Schedule for IRC Section 168(k) Property.
How To File Form IT-399
Form IT-399 must be submitted with the applicable New York State income tax return. It is not intended to be filed as a separate, standalone tax return.
The form provides four return options:
- IT-201: New York State resident income tax return.
- IT-203: Nonresident and part-year resident income tax return.
- IT-204: Partnership return.
- IT-205: Fiduciary income tax return for estates and trusts.
Select the appropriate return type by marking an X in the corresponding box.
Before completing the form, prepare the information needed to calculate the depreciation adjustments. This may include your federal depreciation schedules, property descriptions, original asset costs or other tax bases, dates placed in service, depreciation methods, useful lives, New York depreciation amounts, federal ACRS deductions, and records showing when and how property was disposed of.
You should also have Form IT-225, New York State Modifications, available because the calculated amounts from Form IT-399 are transferred to specific lines on that form.
Important Filing Rules
Nonresidents and Part-Year Residents
If you are a nonresident or part-year resident of New York, complete Form IT-399 using the same approach as if you had been a New York resident for the entire tax year. Transfer the applicable Part 1 and Part 2 amounts to Form IT-225.
Partnerships
When a partnership uses ACRS to calculate depreciation, the partnership itself must complete Form IT-399. Individual partners should not prepare separate IT-399 forms for their partnership interests. Instead, each partner reports their distributive share of the applicable New York depreciation and federal ACRS adjustments on their personal income tax return.
S Corporation Shareholders
If you are a shareholder of an electing New York State S corporation, the corporation should provide your proportionate share of its depreciation deduction.
Married Couples Filing Separate New York Returns
If you file a joint federal income tax return but are required to file separate New York returns, complete only one Form IT-399 using the amounts from the joint federal return. Attach a separate schedule to each New York return showing the amounts attributable to each spouse, calculated as though separate federal returns had been filed. Explain any differences between the amounts.
Estates and Trusts
Special reporting rules apply when depreciation adjustments are attributable to items that are not included in the federal distributable net income of an estate or trust. In these circumstances, the applicable amounts are reported on Form IT-205, line 2, or Form IT-205-A, line 7, when allocation is required. If the amounts are reflected in federal distributable net income, follow the regular transfer instructions on Form IT-399.
How To Complete Form IT-399
The form contains two main parts. Part 1 calculates annual depreciation differences between New York State and federal ACRS depreciation. Part 2 calculates the adjustment required when qualifying property is disposed of.
Complete the identification section first, then work through the applicable parts using your property and depreciation records.
Taxpayer Identification Information
Name(s) as Shown on Return
Enter the taxpayer’s name exactly as it appears on the New York State income tax return associated with Form IT-399. For a joint return, use the names shown on that return.
Identifying Number
Enter the taxpayer’s identifying number used on the income tax return. This will generally be a Social Security number (SSN) or employer identification number (EIN), depending on the taxpayer.
Income Tax Return Selection
Mark an X in only one box to identify the New York State return being filed.
- Select IT-201 for a resident income tax return.
- Select IT-203 for a nonresident or part-year resident return.
- Select IT-204 for a partnership return.
- Select IT-205 for an estate or trust fiduciary return.
Submit Form IT-399 with the selected income tax return.
Part 1: Depreciation Information
Part 1 is used to report depreciation information for qualifying property, excluding IRC Section 280F property. It generally covers property placed in service inside or outside New York during tax years beginning after December 31, 1980, but before January 1, 1985. It also covers eligible property placed in service outside New York during tax years beginning after December 31, 1984, but before January 1, 1994, when the taxpayer elects to continue using IRC Section 167 depreciation.
New York State requires qualifying property to use an applicable depreciation method permitted under IRC Section 167 as it existed on December 31, 1980. The federal ACRS deduction is reported separately so that the required state adjustment can be calculated.
Complete one property entry for each applicable asset. If the available spaces are insufficient, attach an additional schedule containing the required information.
Column A: Description of Property
Enter a clear description of each qualifying business or investment asset. Identify the property sufficiently to distinguish it from other assets listed in your depreciation records.
If you have more assets than the available rows allow, attach an additional schedule containing the same information.
Column B: Date Placed in Service
Enter the date the property was first placed in service using the MMDDYYYY format.
The placed-in-service date is important because it determines whether the property falls within the historical tax-year periods covered by Form IT-399.
Depreciation generally begins when you first use the property in your business or for the production of income.
Column C: Depreciable Basis
Enter the depreciable basis of the property placed in service during the applicable year.
Start with the property’s cost or other tax basis. Then reduce that amount by any portion elected for amortization or deduction under IRC Section 179 and any federal investment credit subtracted when determining the property’s federal unadjusted basis.
Enter the resulting depreciable basis in this column.
Column D: Depreciation Method
Enter the depreciation method elected for New York State purposes.
The method must be permitted under IRC Section 167 as it existed on December 31, 1980. Do not automatically use the federal ACRS method simply because it was used on your federal return.
The selected method determines how the New York depreciation deduction is calculated.
Column E: Life or Rate
Enter the applicable useful life or depreciation rate for the property.
Use the useful life or rate permitted under IRC Section 167 as it existed on December 31, 1980. Do not substitute the federal ACRS recovery period when calculating New York depreciation.
In certain situations, the useful life under the older depreciation rules may happen to be the same as the federal recovery period.
Column F: New York Depreciation
Enter the New York State depreciation deduction for the property.
Calculate this amount using the depreciation method selected in Column D and the applicable useful life or rate entered in Column E.
The amount should reflect the New York depreciation deduction for the applicable tax year.
Column G: Federal ACRS Deduction
Enter the ACRS depreciation deduction claimed for the property on your federal income tax return.
Use the federal amount rather than recalculating the deduction under New York depreciation rules. This column allows the difference between the state and federal depreciation amounts to be determined.
Line 1: Total New York Depreciation and Federal ACRS Deduction
Add all amounts entered in Column F and enter the total in the first amount space on line 1.
Next, add all amounts entered in Column G and enter the federal ACRS total in the second amount space.
These totals represent the combined New York depreciation deduction and federal ACRS deduction for the qualifying properties reported in Part 1.
After calculating line 1, transfer the amounts to Form IT-225 as follows:
- Transfer the Column F total to Form IT-225, line 10, Total Amount column. Enter subtraction modification code S-210 in the Number column.
- Transfer the Column G total to Form IT-225, line 1, Total Amount column. Enter addition modification code A-205 in the Number column.
These entries ensure that the appropriate New York State depreciation adjustments are included in the state income tax calculation.
Special Rule for Part 1: Estates and Trusts
If the depreciation amounts calculated in Part 1 relate to items included in the federal distributable net income of an estate or trust, transfer the amounts using the regular instructions above.
If the amounts are not reflected in federal distributable net income, use the special fiduciary reporting instructions explained earlier.
Part 2: Year-of-Disposition Adjustment
Part 2 calculates the New York State income adjustment required when qualifying property is disposed of.
It applies to property, other than IRC Section 280F property, placed in service inside or outside New York during tax years beginning after December 31, 1980, but before January 1, 1985. It also applies to qualifying property placed in service outside New York during tax years beginning after December 31, 1984, but before January 1, 1994.
When qualifying property is disposed of, New York State requires an adjustment based on the difference between the total New York depreciation deduction and the total federal ACRS deduction claimed for that property.
Investment Credit Checkbox
Mark an X in this box if you claimed an investment credit on Form IT-212, Investment Credit, for any property listed in Part 2.
This checkbox identifies property for which an investment credit was claimed. It is particularly important when the property is disposed of or removed from qualified use before the applicable useful life or required holding period ends.
Column A: Description of Property
Enter the description of each property disposed of during the tax year.
Use a description that clearly identifies the asset and allows it to be matched with the depreciation records used in Part 1 or your federal tax records.
Attach an additional schedule if more property entries are required.
Column B: Date of Disposition
Enter the date the property was disposed of.
The date should reflect when the relevant disposal transaction occurred. This information helps establish the tax year in which the depreciation adjustment must be reported.
Column C: Method of Disposition
Enter the method used to dispose of the property.
Disposition can include several types of transactions, such as:
- Sale of the property.
- Exchange of the property.
- Transfer of the property.
- Disposal because the property became obsolete.
Identify the applicable method for each listed asset.
Column D: Amount of New York Depreciation
Enter the total New York State depreciation claimed for the property being disposed of.
Use the cumulative New York depreciation deductions claimed for that property, rather than only the deduction for the current year.
An important exception applies to property placed in service during 1981. Do not include the ACRS depreciation claimed for that property on the 1981 New York State income tax return.
Column E: Amount of ACRS Deduction
Enter the total federal ACRS depreciation deduction claimed on your federal income tax returns for the property being disposed of.
Use the cumulative federal ACRS amount applicable to the asset.
For property placed in service during 1981, exclude the ACRS depreciation claimed on the 1981 federal income tax return.
Line 2: Total New York Depreciation and ACRS Deductions
Add all amounts in Column D and enter the total in the first amount space on line 2.
Then add all amounts in Column E and enter the federal ACRS total in the second amount space.
These amounts represent the total New York depreciation and federal ACRS deductions for the properties reported in Part 2.
Line 3: Larger Depreciation Amount
Compare the two totals entered on line 2.
Enter the larger amount, whether it comes from Column D or Column E.
This line establishes the higher depreciation total used in the year-of-disposition calculation.
Line 4: Smaller Depreciation Amount
Compare the same two amounts from line 2.
Enter the smaller amount, whether it comes from Column D or Column E.
This amount is used to determine the difference between the New York and federal depreciation deductions.
Line 5: Depreciation Difference
Subtract the amount on line 4 from the amount on line 3.
The result represents the difference between the total New York depreciation and federal ACRS deductions for the disposed property.
The amount is then transferred to Form IT-225 using the appropriate addition or subtraction modification.
- If Column D is larger than Column E, transfer the line 5 amount to Form IT-225, line 1, Total Amount column. Enter addition modification code A-206 in the Number column.
- If Column E is larger than Column D, transfer the line 5 amount to Form IT-225, line 10, Total Amount column. Enter subtraction modification code S-211 in the Number column.
If both totals are equal, line 5 will be zero and neither of the two greater-than conditions applies.
Important Investment Credit Adjustment
A separate tax adjustment may apply when property associated with an investment credit, retail enterprise credit, or research and development credit claimed on Form IT-212 is disposed of or removed from qualified use before the end of its useful life or specified holding period.
In that situation, the difference between the credit originally claimed and the credit allowed based on actual use must be added to the taxpayer’s income tax for the year of disposition.
Use Form IT-212 and its instructions to determine the applicable credit adjustment and calculate the amount.
Special Rule for Part 2: Estates and Trusts
If the amounts calculated in Part 2 relate to items included in the federal distributable net income of an estate or trust, transfer them using the applicable instructions on Form IT-399.
If the amounts are not included in federal distributable net income, report them on the appropriate fiduciary return:
- Form IT-205, line 2.
- Form IT-205-A, line 7, when allocation is required.
Pay attention to whether the adjustment represents an addition or subtraction modification when reporting the amounts.
Important Depreciation Rules And Special Situations
New York Depreciation Versus Federal ACRS
New York State does not always accept the same depreciation deduction used on a federal income tax return.
For qualifying property placed in service during tax years 1981 through 1984, including fiscal years beginning in 1984, New York generally does not allow the federal ACRS deduction, except for property classified under IRC Section 280F.
Instead, taxpayers must calculate New York depreciation using an applicable method permitted under IRC Section 167 as it existed on December 31, 1980. These deductions may generally continue until the property is fully depreciated or disposed of.
Property Placed in Service Outside New York During 1985 Through 1993
For eligible property placed in service outside New York during tax years beginning after 1984 but before 1994, New York generally did not allow ACRS or MACRS depreciation under IRC Section 168. The state instead allowed depreciation based on the older IRC Section 167 rules.
However, following the Reynolds court decision, certain taxpayers who claimed federal ACRS depreciation on eligible property may choose to continue using the pre-1981 IRC Section 167 depreciation method and make the required New York additions and subtractions, or switch to IRC Section 168 depreciation.
If you elect to switch to IRC Section 168 depreciation, you no longer need to make the applicable New York depreciation addition and subtraction adjustments for that property. You must continue using IRC Section 168 depreciation from that tax year forward for all of your subject property.
Passive Activity Loss Limitations
Taxpayers with interests in passive activities must generally calculate the required New York depreciation and ACRS modifications using the full amounts allowable as federal depreciation deductions.
The New York modifications are calculated using 100% of the allowable federal depreciation amount, even when the activity is subject to federal passive loss deduction limitations. The applicable passive loss limitation is governed by IRC Section 469.
Final Review Before Filing
Before submitting Form IT-399 with your New York State income tax return, review the following items carefully:
- Confirm that you are using the correct tax year and Form IT-399 version.
- Enter your name exactly as shown on your income tax return.
- Verify your Social Security number or employer identification number.
- Mark only one applicable New York State income tax return box.
- Confirm that the reported properties fall within the applicable historical placed-in-service periods.
- Exclude property classified under IRC Section 280F.
- Do not use Form IT-399 for property covered by IRC Section 168(k).
- Complete every applicable property description and date field.
- Verify the depreciable basis after applicable IRC Section 179 and federal investment credit adjustments.
- Use the correct IRC Section 167 depreciation method and useful life or rate in Part 1.
- Check that New York depreciation and federal ACRS deductions are entered in the correct columns.
- Verify the totals reported on Part 1, line 1.
- Transfer the Part 1 amounts to the correct Form IT-225 lines using modification codes S-210 and A-205.
- If reporting disposed property, verify its description, disposition date, and disposition method.
- Check the investment credit box when applicable.
- Review the cumulative New York and federal depreciation amounts reported in Part 2.
- Confirm the calculations on lines 2, 3, 4, and 5.
- Transfer the Part 2 adjustment to Form IT-225 using the correct modification code, A-206 or S-211.
- Review any applicable investment credit recapture requirements.
- Apply the special reporting rules for partnerships, S corporation shareholders, nonresidents, married couples, estates, or trusts when relevant.
- Attach additional property schedules if the available spaces are insufficient.
- Make sure Form IT-225 includes all required depreciation modifications.
- Submit Form IT-399 with the appropriate New York State income tax return.
Completing Form IT-399 carefully helps ensure that qualifying depreciation differences between federal and New York State tax rules are properly reflected in your state income tax calculations. Review the property records, verify every calculation, and confirm that all required modifications are transferred correctly before filing.