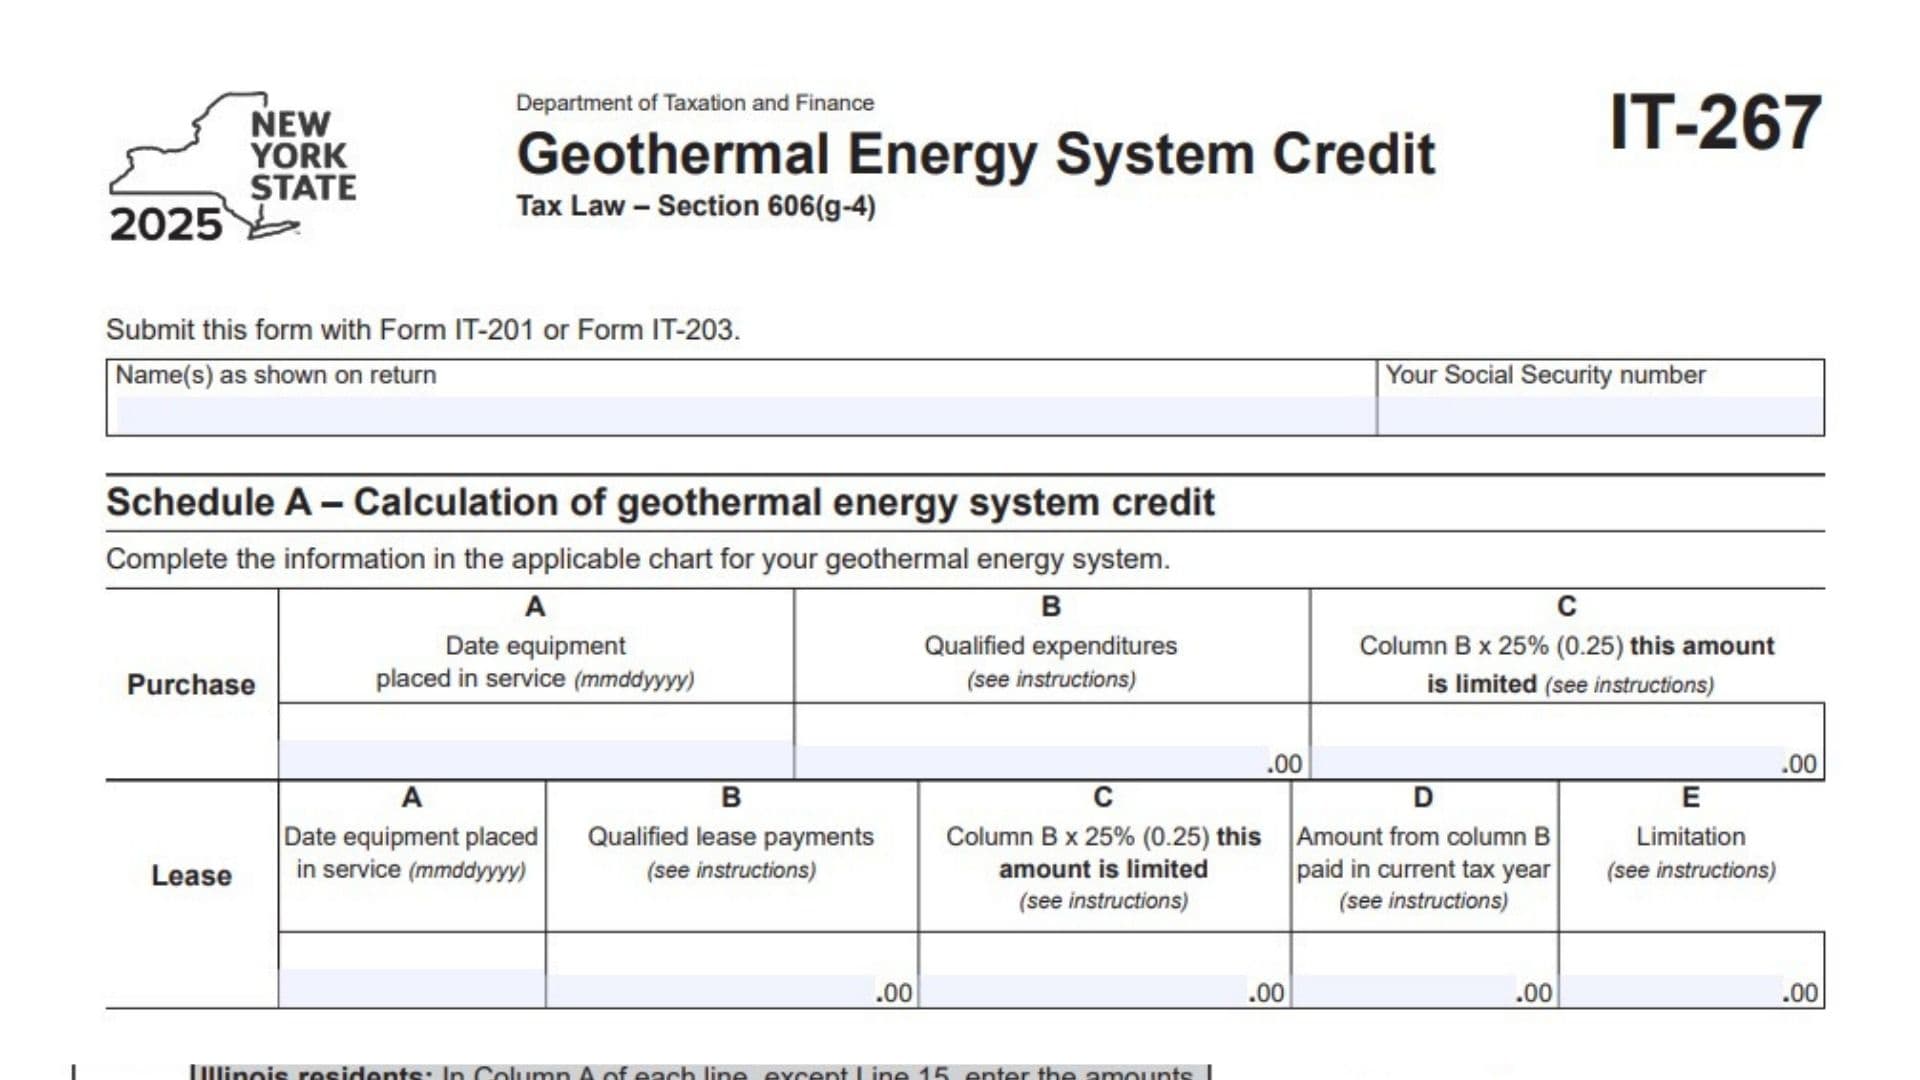
New York Form IT-267, Geothermal Energy System Credit, is a tax form used to calculate and claim a credit for qualifying geothermal energy system expenditures. It is issued by the New York State Department of Taxation and Finance under Tax Law Section 606(g-4). The form allows eligible taxpayers to calculate the credit associated with purchasing or leasing geothermal energy system equipment and apply the available credit against their New York State income tax liability.
Form IT-267 covers two types of geothermal energy system arrangements: equipment purchases and equipment leases. For purchases, taxpayers report the date the equipment was placed in service, qualified expenditures, and the applicable credit calculation. For leases, taxpayers report the equipment’s service date, qualified lease payments, the portion paid during the current tax year, and the applicable limitation.
The form calculates the current-year geothermal energy system credit and combines it with any unused credit carried forward from the previous tax year. It then determines how much credit can be applied against the taxpayer’s income tax liability and how much remains available for future years.
Individuals who qualify for this credit and file a New York State resident income tax return or nonresident and part-year resident income tax return may use Form IT-267. The completed form must accompany Form IT-201 or Form IT-203. Providing accurate equipment information, expenditure amounts, payment details, and previous-year credit balances is important because these figures determine the available credit and its application to the current year’s tax liability.
How To File Form IT-267
Form IT-267 is not a standalone income tax return. It is a supporting tax credit form that must be submitted with the appropriate New York State individual income tax return.
Where To Submit Form IT-267
Submit the completed Form IT-267 with one of the following New York State income tax returns:
- Form IT-201: Used by full-year New York State residents.
- Form IT-203: Used by nonresidents and part-year residents who have New York State income tax filing requirements.
If you file your income tax return electronically, include the geothermal energy system credit information as part of your return preparation and retain the supporting documentation.
Information To Prepare Before Completing Form IT-267
Gather the following information before starting the form:
- Your name or names exactly as they appear on your income tax return.
- Your Social Security number.
- The date each applicable geothermal energy system was placed in service.
- Qualified expenditures associated with purchasing the equipment.
- Qualified lease payments, if applicable.
- The amount of qualifying lease payments made during the current tax year.
- The applicable credit limitations.
- Your previous year’s Form IT-267 showing any available carryover credit.
- Your current-year income tax information.
- Information about other tax credits applied before the geothermal energy system credit.
Keep invoices, purchase records, lease agreements, payment records, and other supporting documents available when calculating the credit. The form refers to separate instructions for determining qualified expenditures and applicable limitations.
How To Complete Form IT-267
The 2025 Form IT-267 contains two main schedules:
- Schedule A: Calculation of Geothermal Energy System Credit.
- Schedule B: Application of Credit and Calculation of Carryover.
Complete the identification section first, followed by the applicable purchase or lease information in Schedule A. Then complete the credit calculations in Schedule B.
Taxpayer Identification Information
Before completing Schedule A, enter the identification information requested at the top of the form.
Name(s) as shown on return
Enter your full name or the names of the taxpayers exactly as they appear on your accompanying Form IT-201 or Form IT-203.
If the income tax return includes more than one taxpayer, make sure the names match the return.
Your Social Security number
Enter the Social Security number associated with the taxpayer claiming the credit. Check the number carefully to avoid identification errors.
Schedule A: Calculation of Geothermal Energy System Credit
Schedule A is used to calculate the geothermal energy system credit based on qualifying equipment purchases or lease payments.
The schedule contains two separate charts:
- Purchase: For geothermal energy system equipment that was purchased.
- Lease: For geothermal energy system equipment that was leased.
Complete the chart that applies to your situation. If both arrangements apply, provide the relevant information in both sections.
Purchase: Geothermal Energy System Equipment
The Purchase section contains three columns. These columns collect information about the equipment, its qualified purchase expenditures, and the resulting credit calculation.
Column A: Date Equipment Placed in Service
Enter the date the geothermal energy system equipment was placed in service.
Use the required MMDDYYYY format. For example, if the equipment was placed in service on March 15, 2025, enter 03152025.
Use the actual date the equipment entered service rather than automatically using its purchase or invoice date.
Column B: Qualified Expenditures
Enter the amount of qualified expenditures associated with purchasing the geothermal energy system equipment.
Use the amount that meets the applicable qualification requirements under the form instructions. Do not automatically include every expense connected with the project.
The instructions referenced by the form determine which expenditures qualify.
Column C: Column B × 25% (0.25)
Multiply the qualified expenditures entered in Column B by 25%.
The calculation is:
Credit calculation = Column B × 0.25
For example, if qualified expenditures are $20,000, the preliminary calculation is:
$20,000 × 25% = $5,000.
Enter the resulting amount in Column C, subject to the applicable limitation described in the form instructions.
Lease: Geothermal Energy System Equipment
The Lease section contains five columns. It collects information about the leased equipment, qualifying payments, current-year payments, and applicable limitations.
Column A: Date Equipment Placed in Service
Enter the date the leased geothermal energy system equipment was placed in service.
Use the MMDDYYYY date format.
For example, equipment placed in service on June 10, 2025, should be entered as 06102025.
Column B: Qualified Lease Payments
Enter the amount of qualified lease payments associated with the geothermal energy system.
Include only payments that meet the applicable qualification requirements. Review the form instructions to determine which lease payments are eligible.
Column C: Column B × 25% (0.25)
Multiply the qualified lease payments in Column B by 25%.
The calculation is:
Column C = Column B × 0.25
This calculates the preliminary credit amount associated with the qualified lease payments. The form indicates that this amount is subject to a limitation.
Column D: Amount From Column B Paid in Current Tax Year
Enter the portion of the qualified lease payments reported in Column B that was actually paid during the current tax year.
Use the amount paid during the tax year covered by the return. Do not automatically enter the entire lease payment amount if some payments were made in another year.
Column E: Limitation
Enter the applicable limitation for the lease credit calculation.
Use the limitation specified in the Form IT-267 instructions. The form does not provide the detailed limitation calculation in this column.
Review the qualified payment amount, the amount paid during the current year, and the applicable limitation before completing this section.
Schedule B: Application of Credit and Calculation of Carryover
Schedule B determines how much of the geothermal energy system credit can be used against your current-year tax liability and how much remains available for a future year.
Complete lines 1 through 3 to establish the total available credit. Then complete lines 4 through 10 to calculate the amount applied and any remaining carryover.
Line 1: Current Year Credit
Enter the geothermal energy system credit calculated for the current tax year.
Use the applicable credit amount determined through Schedule A and follow the Form IT-267 instructions when transferring the amount to this line.
This amount represents the credit generated for the current tax year.
Line 2: Carryover Credit From Last Year’s Form IT-267, Line 10
Enter the unused geothermal energy system credit carried forward from the previous year’s Form IT-267, line 10.
Use the amount reported on the previous year’s completed form.
If you do not have a carryover credit from the previous year, enter zero.
Line 3: Geothermal Energy System Credit
Add the amounts reported on lines 1 and 2.
The calculation is:
Line 3 = Line 1 + Line 2
This amount represents the total geothermal energy system credit available before applying it against your current-year tax liability.
Line 4: Tax Due Before Credits
Enter your tax liability before applying tax credits.
Use the amount determined from your accompanying New York State income tax return and follow the Form IT-267 instructions to identify the correct amount.
This figure establishes how much tax is available to be offset by the geothermal energy system credit.
Line 5: Other Credits Applied Before This Credit
Enter the total amount of other tax credits that you applied before claiming the geothermal energy system credit.
Include the applicable credits in the order required by the tax return instructions.
This amount is used to determine how much tax liability remains available for the geothermal energy system credit.
Line 6: Remaining Tax After Other Credits
Subtract line 5 from line 4.
The calculation is:
Line 6 = Line 4 − Line 5
The result represents the remaining tax liability after accounting for the other credits applied before the geothermal energy system credit.
Line 7: Allowable Geothermal Energy System Credit
Enter the smaller of the amount on line 3, or your applicable portion of line 3, and the amount on line 6.
The calculation is:
Line 7 = Lesser of Line 3 (or your portion of line 3) or Line 6.
This amount represents the geothermal energy system credit that can be applied against your remaining current-year tax liability.
If the available credit exceeds the remaining tax liability, line 7 is limited by the amount on line 6.
Line 8: Remaining Geothermal Energy System Credit
Subtract line 7 from line 3, or your applicable portion of line 3, as directed by the form instructions.
The calculation is:
Line 8 = Line 3 (or your portion of line 3) − Line 7
This amount represents the geothermal energy system credit that was not used against your current-year tax liability.
The remaining amount is considered when determining the credit available for carryover to the next tax year.
Line 9: Credit That Expired During the Current Tax Year
Enter the amount, if any, included on line 8 that expired during the current tax year.
This line accounts for credit amounts that are no longer eligible to be carried forward.
Important: The 2025 Form IT-267 specifically instructs taxpayers to leave line 9 blank because it is not applicable for this tax year. Do not enter an amount on this line when completing the 2025 form.
Line 10: Amount of Credit Available for Carryover to Next Year
Subtract line 9 from line 8.
The calculation is:
Line 10 = Line 8 − Line 9
The result represents the geothermal energy system credit available to carry forward to the next tax year.
For the 2025 tax year, line 9 must remain blank, so the amount on line 10 generally corresponds to the amount reported on line 8.
Keep a copy of the completed form because the amount on line 10 will be needed when completing the following year’s Form IT-267.
Understanding the Geothermal Energy System Credit Calculation
The main purpose of Form IT-267 is to determine the available geothermal energy system credit and how much can be applied against your New York State income tax liability.
The calculation takes place in two stages.
Stage 1: Calculate the Available Credit
Schedule A collects the information needed to calculate the credit for purchased or leased geothermal energy system equipment.
The purchase calculation uses qualified expenditures multiplied by 25%, subject to the applicable limitation.
The lease calculation uses qualified lease payments multiplied by 25%, together with the current-year payment information and applicable limitation.
The resulting current-year credit is entered on Schedule B, line 1.
Any unused credit from the previous year is entered on line 2.
Adding these amounts gives the total available credit on line 3.
Stage 2: Apply the Credit and Calculate the Carryover
Schedule B determines how much of the available credit can be applied against current-year tax liability.
First, line 6 establishes the remaining tax after other credits have been applied.
Next, line 7 limits the geothermal energy system credit to the smaller applicable amount.
Line 8 calculates the unused portion of the available credit.
Finally, line 10 determines the amount available for carryover to the following tax year.
Final Review Before Filing
Before submitting Form IT-267 with your New York State income tax return, review the following items carefully.
- Confirm that you are using the correct 2025 Form IT-267.
- Enter your name exactly as shown on Form IT-201 or Form IT-203.
- Verify your Social Security number.
- Complete the Purchase chart if you purchased qualifying geothermal energy system equipment.
- Complete the Lease chart if you leased qualifying geothermal energy system equipment.
- Enter the correct equipment service dates using the MMDDYYYY format.
- Verify the qualified expenditures reported in the Purchase section.
- Check the qualified lease payments reported in the Lease section.
- Confirm the amount of lease payments made during the current tax year.
- Apply the 25% calculation in the appropriate columns.
- Review the applicable limitations using the form instructions.
- Enter the correct current-year credit on line 1.
- Transfer the previous year’s carryover credit to line 2.
- Verify that line 3 equals the sum of lines 1 and 2.
- Enter the correct tax due before credits on line 4.
- Include the applicable previously applied credits on line 5.
- Subtract line 5 from line 4 to calculate line 6.
- Enter the allowable geothermal energy system credit on line 7.
- Calculate the remaining credit on line 8.
- Leave line 9 blank for the 2025 tax year.
- Calculate the available carryover amount on line 10.
- Check all calculations for accuracy.
- Submit Form IT-267 with Form IT-201 or Form IT-203.
Completing Form IT-267 carefully helps ensure that your geothermal energy system credit is calculated and applied correctly. Keep the completed form and supporting records with your tax documents, especially the amount reported on line 10, which may be needed when calculating a credit carryover in a future tax year.