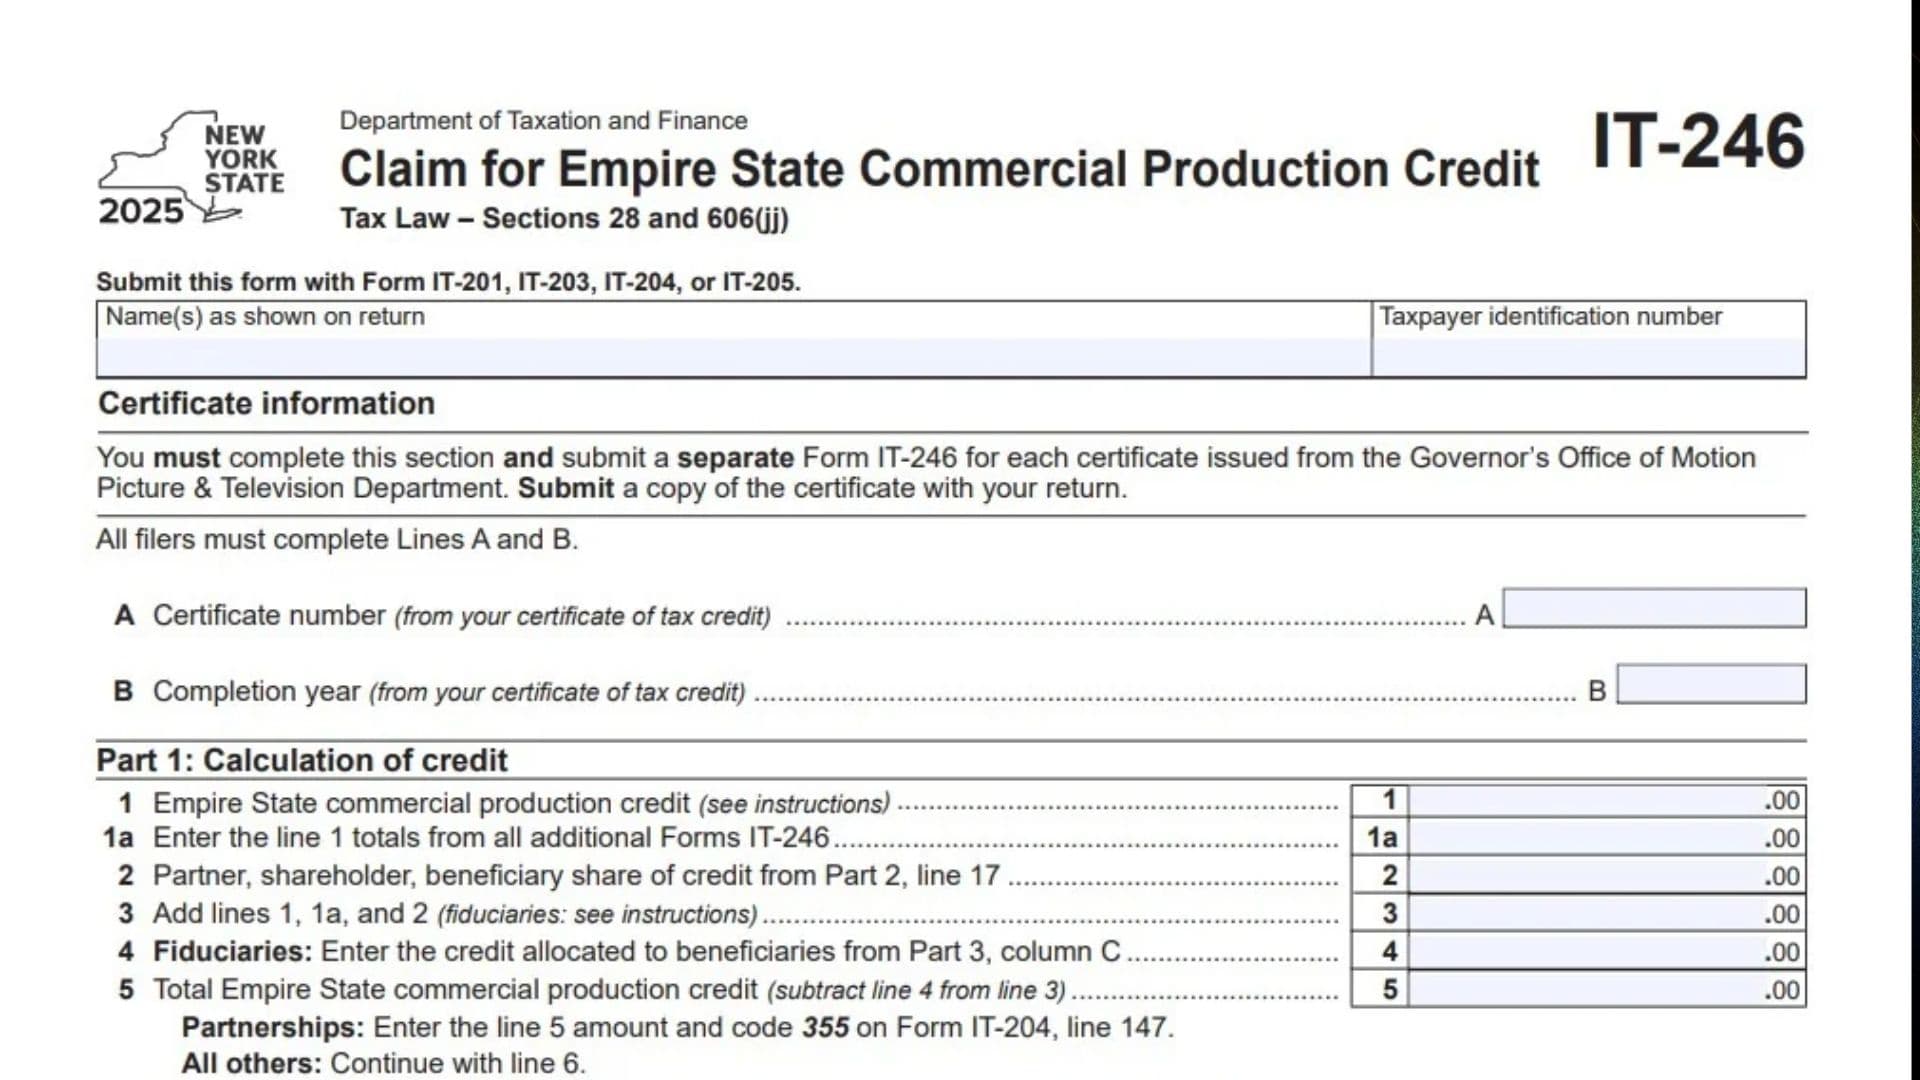
New York Form IT-246, officially titled Claim for Empire State Commercial Production Credit, is a tax form issued by the New York State Department of Taxation and Finance. It is used by eligible taxpayers to calculate and claim the Empire State Commercial Production Credit under Sections 28 and 606(jj) of the New York Tax Law. The credit relates to qualifying commercial production activities and is supported by a tax credit certificate issued by the Governor’s Office of Motion Picture and Television Development. The form collects information about the taxpayer, the tax credit certificate, the amount of credit available, and the allocation of credit among partners, shareholders, beneficiaries, and fiduciaries. It also determines the nonrefundable and refundable portions of the credit and calculates any amount that can be carried forward to a future tax year. Form IT-246 contains three main parts. Part 1 calculates the credit and determines how it affects the taxpayer’s tax liability. Part 2 reports the names, entity types, employer identification numbers, and credit shares of partnerships, New York S corporations, and estates or trusts. Part 3 identifies beneficiaries and calculates the allocation of credit between beneficiaries and the fiduciary. Taxpayers must complete the certificate information and submit a separate Form IT-246 for each certificate issued by the relevant New York State office. A copy of each certificate must accompany the tax return. The completed form must be submitted with the applicable New York tax return, which may be Form IT-201, IT-203, IT-204, or IT-205, depending on the taxpayer’s filing situation. Accurate completion is important because the form determines the amount of credit that can be claimed, allocated, refunded, or carried forward. Errors in certificate details, entity information, beneficiary allocations, or credit calculations can affect the amount of credit reported on the taxpayer’s return.
How To File Form IT-246
Form IT-246 must be filed with the applicable New York income tax or fiduciary tax return. It is not intended to be submitted as a standalone tax return.
Which Tax Returns Must Include Form IT-246?
Submit Form IT-246 with the applicable return:
- Form IT-201: New York State Resident Income Tax Return.
- Form IT-203: Nonresident and Part-Year Resident Income Tax Return.
- Form IT-204: Partnership Return.
- Form IT-205: Fiduciary Income Tax Return.
Choose the return that corresponds to the taxpayer’s filing status and entity type.
Tax Credit Certificate Requirements
Before completing Form IT-246, review the tax credit certificate issued by the Governor’s Office of Motion Picture and Television Development.
The form establishes two important requirements:
- A separate Form IT-246 must be completed for each certificate issued.
- A copy of the applicable tax credit certificate must be submitted with the tax return.
All filers must complete the certificate information in Lines A and B.
Information To Prepare Before Completing Form IT-246
Gather the following information:
- Taxpayer’s name as shown on the tax return.
- Taxpayer identification number.
- Tax credit certificate number.
- Completion year shown on the certificate.
- Empire State commercial production credit amount.
- Credit amounts reported on additional Forms IT-246, if applicable.
- Partner, shareholder, or beneficiary credit allocation information.
- Previously reported or applicable tax amounts from the required New York tax returns.
- Other credit information.
- Prior-year credit carryforward information.
- Partnership, S corporation, estate, and trust identification details, when applicable.
- Beneficiary names and identifying numbers, when applicable.
- Fiduciary credit allocation information.
How To Complete Form IT-246
The form contains three main parts:
- Part 1: Calculation of credit.
- Part 2: Partnership, New York S corporation, and estate and trust information.
- Part 3: Beneficiary’s and fiduciary’s share of the Empire State commercial production credit.
Which Sections Must You Complete?
The applicable sections depend on your role:
- Individual taxpayers, including sole proprietors: Complete Part 1, Lines 1 through 16.
- Partnerships: Complete Part 1, Lines 1 through 5.
- Partners, shareholders of New York S corporations, and beneficiaries of estates or trusts: Complete Part 1, Lines 2 through 16, and Part 2.
- Fiduciaries: Complete Part 1, Lines 1 through 16, and Part 3.
- Married couples using an IRC Section 761(f) election: If filing jointly and using two federal Schedule C forms instead of a partnership return, calculate the credit as though one federal Schedule C had been filed for the business. Complete Part 1, Lines 1 through 16.
If more than one category applies, complete all relevant sections on the same form.
Tax Credit Calculation Rules
The Empire State Commercial Production Credit is generally available for the tax year in which the qualified commercial production is completed.
The credit is allocated through a certificate issued by the Governor’s Office of Motion Picture and Television Development.
When the available credit exceeds the tax for the year:
- 50% of the excess is treated as an overpayment that can be refunded or credited.
- The remaining excess can be carried forward to the following tax year.
- If the credit is not fully used in the following year, the remaining amount may be requested as a refund or applied to the next year’s tax.
- The New York State Department of Taxation and Finance does not pay interest on the refund or overpayment.
You also cannot use the same production costs to calculate another tax credit.
Part 1: Calculation Of Credit
Part 1 determines the total Empire State Commercial Production Credit available to the taxpayer, the portion that can be used against tax, the refundable portion, and the amount carried forward.
Line 1: Empire State Commercial Production Credit
Enter the credit amount shown on the tax credit certificate issued by the Governor’s Office of Motion Picture and Television Development.
A separate Form IT-246 must be completed for each certificate issued.
Submit a copy of the applicable certificate with your tax return.
If you have multiple credit amounts that require additional forms, follow the additional-form instructions and include the applicable totals on the first form.
Line 1a: Total Credit From Additional Forms IT-246
Enter the combined Line 1 amounts from all additional Forms IT-246.
This line is used when additional forms are necessary to report other credit amounts.
Include the total from those additional forms so that all applicable credits are included in the main calculation.
Line 2: Partner, Shareholder, Or Beneficiary Share Of Credit
Enter the amount of commercial production credit allocated to you through a partnership, New York S corporation, or estate or trust.
Obtain the applicable amount from Part 2, Line 17.
If you received credit through multiple entities, include the combined applicable amount.
Line 3: Total Credit Before Beneficiary Allocation
Add Lines 1, 1a, and 2.
The calculation is:
Line 1 + Line 1a + Line 2 = Line 3.
Enter the resulting amount.
Fiduciaries must also review the instructions for allocating credit to beneficiaries through Part 3.
Line 4: Credit Allocated To Beneficiaries
This line applies to fiduciaries filing for an estate or trust.
Enter the total amount of credit allocated to beneficiaries from Part 3, Column C.
The amount represents the credit distributed to beneficiaries rather than retained by the fiduciary.
Make sure the amount matches the total beneficiary allocation reported in Part 3.
Line 5: Total Empire State Commercial Production Credit
Subtract Line 4 from Line 3.
The calculation is:
Line 3 − Line 4 = Line 5.
Enter the remaining credit available to the taxpayer after accounting for the amount allocated to beneficiaries.
Important partnership instruction: Partnerships must enter the Line 5 amount and code 355 on Form IT-204, Line 147.
All other taxpayers should continue to Line 6.
Line 6: Tax Before Applying The Credit
Enter the applicable tax amount from the corresponding New York tax return.
Use the appropriate line based on your filing status:
- Form IT-201 filers: Enter the amount from Form IT-201, Line 39.
- Form IT-203 filers: Enter the amount from Form IT-203, Line 46.
- Form IT-205 resident fiduciaries: Enter the amount from Form IT-205, Line 8.
- Form IT-205 nonresident or part-year resident fiduciaries: Enter the amount from Form IT-205, Line 9.
Make sure you use the amount from the correct tax return and filing category.
Line 7: Other Applicable Credits
Enter the applicable credits already reported on the corresponding New York tax return.
Use the appropriate source:
- Form IT-201 filers: Enter the amount from Form IT-201-ATT, Line 21.
- Form IT-203 filers: Enter the amount from Form IT-203-ATT, Line 20.
- Form IT-205 filers: Enter the credits shown on Line 1 of the Addbacks worksheet in the instructions for Form IT-205, Line 12.
Use the applicable amount for your return type.
Line 8: Total Tax And Other Credits
Add Lines 6 and 7.
The calculation is:
Line 6 + Line 7 = Line 8.
Enter the resulting total.
Line 9: Other Credits
Enter the amount of other tax credits that must be applied before the Empire State Commercial Production Credit.
The credit ordering rules must be followed when calculating this amount.
The applicable order is:
- Household credit.
- Credits that cannot be carried forward or refunded.
- Credits that can be carried forward for a limited period.
- Credits that can be carried forward for an unlimited period.
- Refundable credits.
Use the appropriate credit information from your New York tax return and supporting schedules.
Line 10: Tax After Other Credits
Subtract Line 9 from Line 8.
The calculation is:
Line 8 − Line 9 = Line 10.
This amount represents the remaining tax after accounting for other applicable credits.
Line 11: Nonrefundable Portion Of Credit
Enter the smaller amount from Line 5 or Line 10.
The calculation is:
Line 11 = The lesser of Line 5 or Line 10.
This is the nonrefundable portion of the Empire State Commercial Production Credit that can be applied against the available tax.
Transfer this amount with code 355 to the appropriate return:
- Form IT-201 filers: Form IT-201-ATT, Line 6.
- Form IT-203 filers: Form IT-203-ATT, Line 7.
- Form IT-205 filers: Form IT-205, Line 10.
Line 12: Remaining Credit After Nonrefundable Portion
Subtract Line 11 from Line 5.
The calculation is:
Line 5 − Line 11 = Line 12.
This amount represents the credit remaining after calculating the nonrefundable portion.
If Line 12 is zero and you have no prior-year carryover, stop. You do not have a refundable credit or a credit to carry forward to the next year.
Line 13: Refundable Portion Calculation
Multiply Line 12 by 50% (0.5).
The calculation is:
Line 12 × 50% = Line 13.
This calculates half of the remaining credit as the refundable portion under the credit calculation rules.
Line 14: Prior-Year Carryover
Enter the unused credit carried forward from the previous tax year.
Use the amount reported on last year’s Form IT-246.
Make sure the amount agrees with the carryforward calculation from the previous year’s return.
Line 15: Refundable Portion Of Credit
Add Lines 13 and 14.
The calculation is:
Line 13 + Line 14 = Line 15.
This amount represents the refundable credit available after including the prior-year carryover.
Transfer the amount with code 355 to the appropriate return:
- Form IT-201 filers: Form IT-201-ATT, Line 12.
- Form IT-203 filers: Form IT-203-ATT, Line 12.
- Form IT-205 filers: Form IT-205, Line 33.
Line 16: Credit To Be Carried Forward To Next Year
Subtract Line 13 from Line 12.
The calculation is:
Line 12 − Line 13 = Line 16.
Enter the resulting amount.
This is the remaining credit that can be carried forward to the next tax year. Keep this amount because it will be needed when completing the following year’s Form IT-246.
Part 2: Partnership, New York S Corporation, And Estate And Trust Information
Part 2 identifies the partnerships, New York S corporations, estates, and trusts from which the taxpayer received a share of the Empire State Commercial Production Credit.
Complete this section when you received credit through one or more of these entities.
The section contains four columns.
Column A: Name Of Entity
Enter the complete name of each partnership, New York S corporation, estate, or trust from which you received a share of the credit.
Use the entity’s official name as provided in its tax or credit allocation information.
If you received credit from multiple entities, list each entity separately.
Column B: Type
Enter the appropriate entity classification using the codes specified on the form.
The available codes are:
- P: Partnership.
- S: New York S corporation.
- ET: Estate or trust.
Enter the correct code for each entity listed in Column A.
Column C: Employer Identification Number
Enter the federal employer identification number (EIN) of the partnership, S corporation, estate, or trust listed in Column A.
Verify the EIN against the entity’s tax documentation.
Each entity must be identified using its corresponding EIN.
Column D: Share Of Credit
Enter the amount of Empire State Commercial Production Credit allocated to you by the corresponding entity.
Use the credit allocation information provided by the partnership, S corporation, estate, or trust.
If you received credit from multiple entities, enter each allocated amount on the appropriate row.
Line 17: Total Share Of Credit
Add all amounts entered in Column D.
The calculation is:
Total of all amounts in Column D = Line 17.
Include amounts reported on additional Forms IT-246, if applicable.
Transfer the resulting total to Part 1, Line 2.
Make sure the amount reported on Line 17 matches the combined credit allocated to you by the listed entities.
Part 3 is specifically designed for estates and trusts that receive or allocate the Empire State Commercial Production Credit.
Estates and trusts must complete this section.
When a fiduciary distributes the credit to beneficiaries, the allocation must be based on each beneficiary’s share of the income of the estate or trust.
The fiduciary must provide each beneficiary with their allocated share of the credit.
Part 3 contains three columns and separate rows for the beneficiary allocations and the fiduciary’s retained share.
Column A: Beneficiary’s Name
Enter the full name of each beneficiary receiving a share of the Empire State Commercial Production Credit.
The beneficiary’s name must match the name reported on Form IT-205, Schedule C.
If multiple beneficiaries receive the credit, list each beneficiary separately.
Column B: Identifying Number
Enter the applicable identifying number for each beneficiary.
Use the beneficiary’s appropriate taxpayer identification number, such as a Social Security number or employer identification number, as applicable.
Make sure the identifying number corresponds to the beneficiary named in Column A.
Column C: Share Of Credit
Enter the amount of commercial production credit allocated to each beneficiary.
Determine the allocation based on each beneficiary’s share of the income of the estate or trust.
Each beneficiary’s amount should reflect their allocated portion of the available credit.
Total: Beneficiaries’ Share Of Credit
Add the amounts allocated to all beneficiaries in Column C.
Enter the combined beneficiary allocation on the Total line.
Transfer this amount to Part 1, Line 4.
Make sure the total matches the amount deducted from Line 3 when calculating the fiduciary’s remaining credit on Line 5.
Fiduciary: Fiduciary’s Share Of Credit
Enter the amount of commercial production credit retained by the fiduciary in Column C.
This represents the portion of the credit remaining with the estate or trust after accounting for beneficiary allocations.
The amount should be consistent with the credit calculation in Part 1.
Additional Forms For Part 2 And Part 3
If you have more entries than the available spaces in Part 2 or Part 3, submit additional Forms IT-246.
Follow these requirements:
- Complete only the necessary sections on the additional forms.
- Include the taxpayer’s name on every additional form.
- Include the taxpayer identification number on every additional form.
- Include the totals from all additional forms on the appropriate lines of the first Form IT-246.
- Place the additional forms behind the first Form IT-246.
- Submit all forms together with the applicable tax return.
This procedure allows taxpayers to report additional partnerships, S corporations, estates, trusts, and beneficiaries without omitting any credit allocation information.
Important Tax Credit Reporting Requirements
After completing Form IT-246, transfer the applicable credit amounts to the corresponding New York tax return.
Reporting The Nonrefundable Credit
The amount reported on Line 11 is the nonrefundable portion of the credit.
Use code 355 when transferring this amount to:
- Form IT-201-ATT, Line 6.
- Form IT-203-ATT, Line 7.
- Form IT-205, Line 10.
Reporting The Refundable Credit
The amount reported on Line 15 is the refundable portion of the credit.
Use code 355 when transferring this amount to:
- Form IT-201-ATT, Line 12.
- Form IT-203-ATT, Line 12.
- Form IT-205, Line 33.
Reporting A Partnership’s Credit
Partnerships must report the amount from Line 5 and code 355 on Form IT-204, Line 147.
The partnership should follow the applicable instructions for reporting and allocating the credit.
Carrying Forward Unused Credit
The amount on Line 16 represents the credit carried forward to the following tax year.
Keep a copy of the completed Form IT-246 and the carryforward calculation for use when preparing the next year’s return.
Common Mistakes To Avoid When Completing Form IT-246
Review these common mistakes before submitting the form:
- Using an incorrect certificate number: Enter the certificate number exactly as issued.
- Entering the wrong completion year: Use the completion year shown on the tax credit certificate.
- Failing to submit a certificate copy: Include a copy of the applicable certificate with the tax return.
- Combining multiple certificates incorrectly: Complete a separate Form IT-246 for each certificate.
- Forgetting additional credit amounts: Include the applicable totals from additional Forms IT-246 on Line 1a.
- Entering an incorrect pass-through credit: Verify Line 2 against Part 2, Line 17.
- Incorrectly calculating Line 3: Make sure Lines 1, 1a, and 2 are added correctly.
- Forgetting beneficiary allocations: Fiduciaries must account for the amount allocated to beneficiaries on Line 4.
- Using the wrong tax return line: Verify the source amount for Line 6 based on whether you file Form IT-201, IT-203, or IT-205.
- Ignoring credit ordering rules: Complete Line 9 using the applicable order of tax credits.
- Incorrectly calculating the nonrefundable portion: Line 11 must be the smaller of Line 5 or Line 10.
- Using the wrong refundable percentage: Line 13 is calculated using 50% of Line 12.
- Forgetting prior-year carryover: Include the applicable amount from last year’s Form IT-246 on Line 14.
- Incorrectly calculating the refundable credit: Add Lines 13 and 14 to determine Line 15.
- Failing to calculate the carryforward: Subtract Line 13 from Line 12 to determine Line 16.
- Using an incorrect entity type: Enter P, S, or ET as appropriate in Part 2.
- Entering an incorrect EIN: Verify each entity’s identification number.
- Allocating beneficiary credit incorrectly: Use each beneficiary’s share of estate or trust income.
- Using incorrect beneficiary names: Match the names reported on Form IT-205, Schedule C.
- Forgetting additional forms: Attach additional Forms IT-246 when the available spaces are insufficient.
- Reporting credit on the wrong tax return line: Use the applicable reporting line and code 355.
Final Review Before Filing
Before submitting Form IT-246, review the following checklist to make sure all required information, calculations, and supporting documents are complete.
Taxpayer And Certificate Information
- The taxpayer’s name matches the applicable tax return.
- The taxpayer identification number is correct.
- The certificate number has been entered correctly.
- The completion year matches the tax credit certificate.
- A separate Form IT-246 has been completed for each certificate.
- A copy of each tax credit certificate is included with the return.
Part 1: Calculation Of Credit
- Line 1 contains the credit amount from the certificate.
- Line 1a includes applicable totals from additional Forms IT-246.
- Line 2 reflects the credit received from partnerships, S corporations, estates, or trusts.
- Line 3 correctly adds Lines 1, 1a, and 2.
- Line 4 includes the credit allocated to beneficiaries, if applicable.
- Line 5 correctly subtracts Line 4 from Line 3.
- The partnership reporting requirement for Line 5 has been followed, if applicable.
- Line 6 contains the correct tax amount from the applicable New York return.
- Line 7 includes the applicable credits from the required tax return or worksheet.
- Line 8 correctly adds Lines 6 and 7.
- Line 9 includes other credits applied before this credit.
- The required credit ordering rules have been followed.
- Line 10 correctly subtracts Line 9 from Line 8.
- Line 11 contains the smaller amount from Line 5 or Line 10.
- Line 12 correctly subtracts Line 11 from Line 5.
- Line 13 correctly calculates 50% of Line 12.
- Line 14 includes the applicable prior-year carryover.
- Line 15 correctly adds Lines 13 and 14.
- Line 16 correctly calculates the amount carried forward.
Part 2: Partnership, S Corporation, Estate And Trust Information
- Every applicable partnership is listed.
- Every applicable New York S corporation is listed.
- Every applicable estate or trust is listed.
- The correct entity type is entered using P, S, or ET.
- Each entity’s EIN is correct.
- The allocated credit amount is entered in Column D.
- Line 17 correctly totals all amounts in Column D.
- Line 17 matches the amount entered on Part 1, Line 2.
Part 3: Beneficiary And Fiduciary Allocation
- Part 3 has been completed if filing as an estate or trust.
- Each beneficiary’s name matches Form IT-205, Schedule C.
- Each beneficiary’s identifying number is correct.
- Each beneficiary’s share of credit is entered in Column C.
- Credit allocations are based on each beneficiary’s share of estate or trust income.
- The Total line correctly adds all beneficiary allocations.
- The Total line matches Part 1, Line 4.
- The fiduciary’s retained share is entered correctly.
- Additional forms have been attached if more beneficiary entries are required.
Final Tax Return Reporting
- The nonrefundable credit from Line 11 is reported using code 355.
- The refundable credit from Line 15 is reported using code 355.
- The correct reporting lines are used for Form IT-201, IT-203, or IT-205.
- Partnerships report the applicable Line 5 amount and code 355 on Form IT-204, Line 147.
- The carryforward amount from Line 16 is retained for next year’s tax return.
- All additional Forms IT-246 are placed behind the first form.
- The completed Form IT-246 is submitted with the applicable New York tax return.
Final Reminder: New York Form IT-246 is used to claim the Empire State Commercial Production Credit for qualifying commercial production activities. Complete the certificate information, calculate the available credit, account for any pass-through allocations, and determine the nonrefundable, refundable, and carryforward portions. Estates and trusts must also complete Part 3 when applicable. Make sure all supporting tax credit certificates and additional forms are included with the appropriate New York tax return.