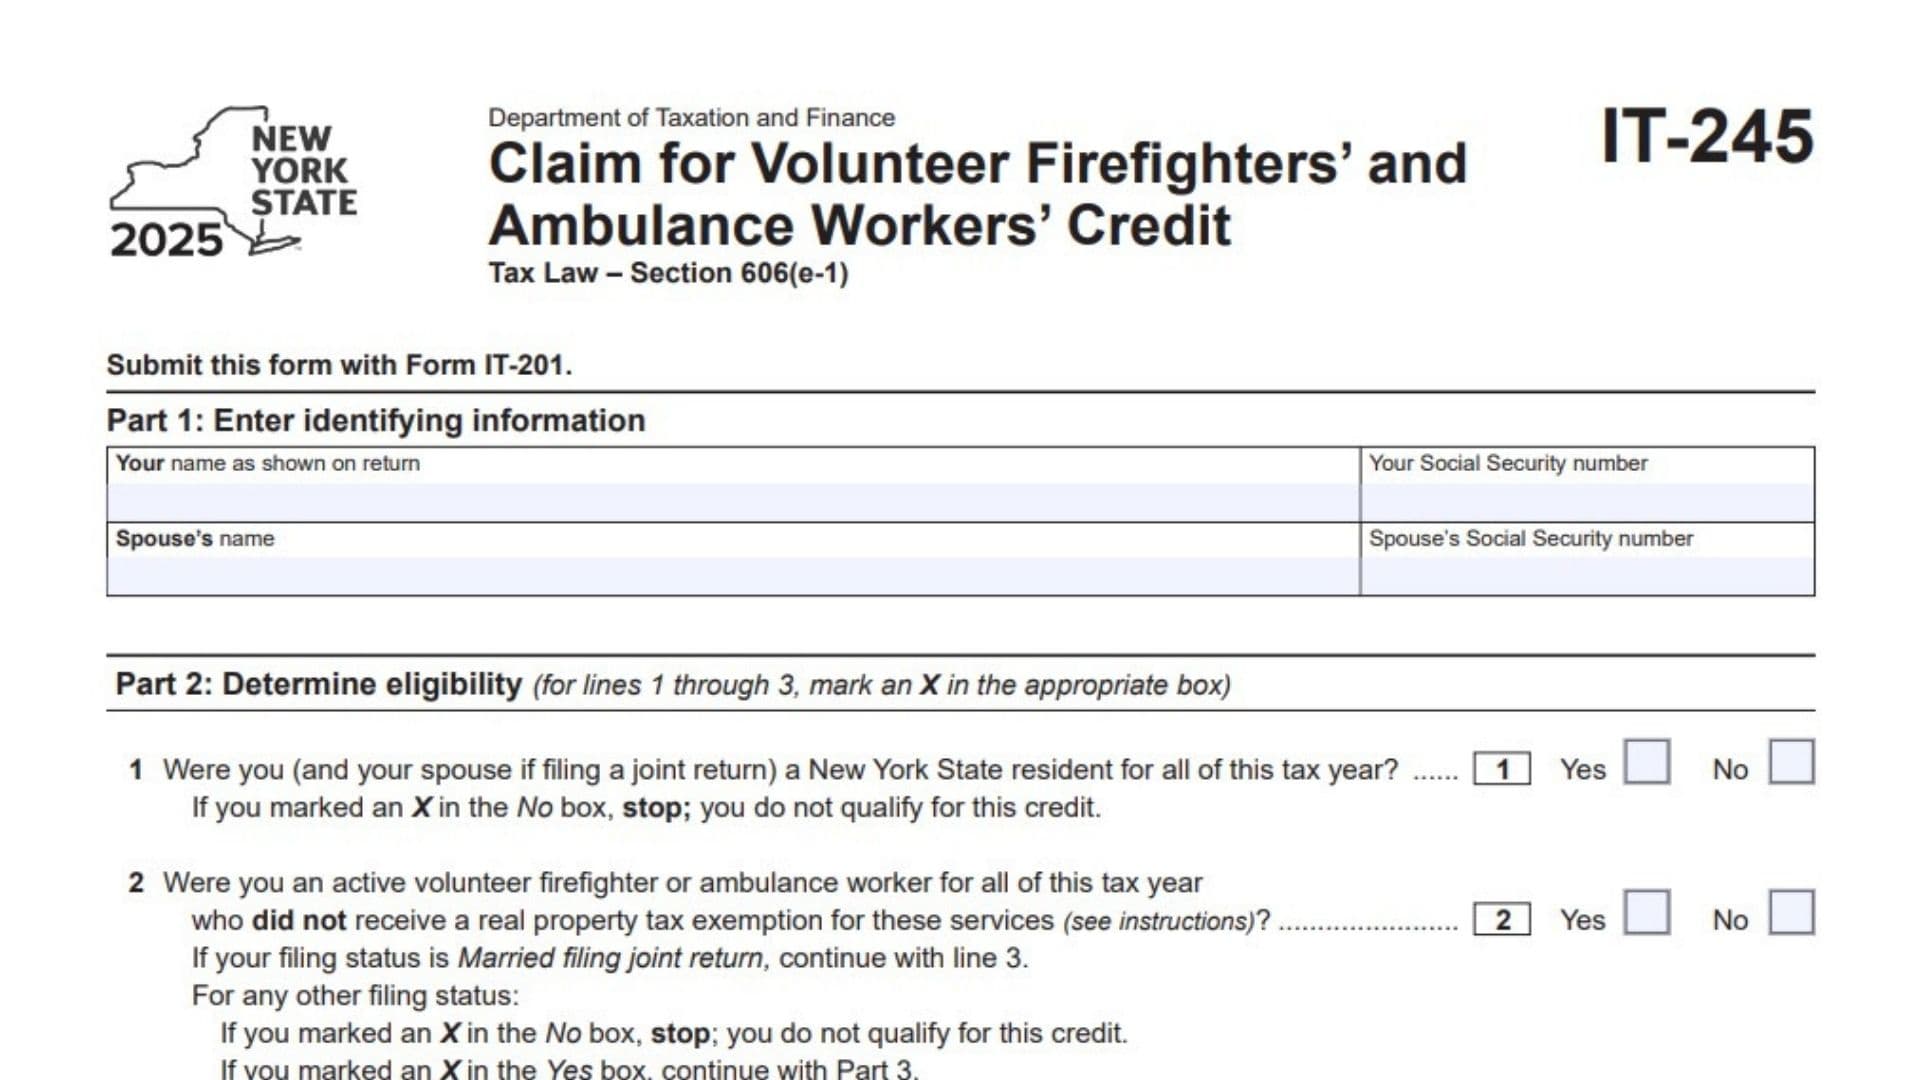
Form IT-245, Claim for Volunteer Firefighters’ and Ambulance Workers’ Credit, is a New York State tax form that eligible residents use to claim a tax credit for their service as volunteer firefighters or volunteer ambulance workers. The credit recognizes individuals who dedicate their time to protecting their communities through volunteer fire protection and emergency ambulance services. Under New York State Tax Law Section 606(e-1), qualifying individuals may claim a $200 credit for the tax year. Married couples filing a joint tax return may claim a combined credit of $400 when both spouses meet the eligibility requirements. To qualify, the taxpayer must have been a New York State resident for the entire tax year and must have served as an active volunteer firefighter or ambulance worker throughout that year. Individuals who receive a real property tax exemption related to their volunteer service cannot claim this credit. The form collects the taxpayer’s identifying information, residency status, volunteer service details, and information about the fire department or ambulance company associated with the qualifying service. It also determines the amount of credit the taxpayer can claim. Completing Form IT-245 correctly is important because the information establishes eligibility and determines the credit amount that must be reported on the appropriate New York State tax forms. The credit is refundable, meaning eligible taxpayers may receive a refund of any unused credit or apply the overpayment to the following year’s tax.
Who Qualifies for the IT-245 Tax Credit?
An individual may qualify for this credit if they meet the following requirements:
- They were a New York State resident for the entire tax year.
- They served as an active volunteer firefighter or volunteer ambulance worker throughout the entire tax year.
- They did not receive a real property tax exemption related to their volunteer service.
An active volunteer firefighter must have been officially approved by the authorities responsible for a recognized New York State volunteer fire company or department and must have actively performed emergency-response duties involving the protection of people and property.
A volunteer ambulance worker must be an active member of a New York State ambulance company and be included on the membership list maintained by that company for the applicable volunteer ambulance workers’ benefit program.
For married couples filing jointly, both spouses may qualify independently. If only one spouse meets the requirements, the couple may claim $200. If both qualify, the combined credit increases to $400.
How Much Is the Form IT-245 Credit?
The credit amount depends on how many spouses qualify when filing a joint return.
- One qualifying taxpayer: $200.
- Both spouses qualifying on a joint return: $400.
- Neither spouse qualifying: No credit is available.
The credit is refundable. If the credit exceeds the taxpayer’s tax liability, the unused amount may be requested as a refund or applied to the following tax year’s liability. New York State does not pay interest on the refunded amount.
How To File Form IT-245
Form IT-245 must be submitted with New York State Form IT-201, Resident Income Tax Return. It is not intended to be filed as a standalone tax return.
The credit amount calculated on Form IT-245 must also be reported on Form IT-201-ATT, Other Tax Credits and Taxes, line 12, using credit code 354.
Where Should You Submit Form IT-245?
Submit Form IT-245 as part of your New York State resident income tax return (Form IT-201).
- Electronic filing: Include the credit information and required forms through your tax preparation software’s New York State return process.
- Paper filing: Include Form IT-245 with your completed Form IT-201 return package and follow the applicable mailing instructions for Form IT-201.
Make sure the amount reported on Form IT-201-ATT, line 12, agrees with the credit calculated on Form IT-245.
Information to Prepare Before Completing the Form
Gather the following information before starting:
- Your full legal name as reported on your New York State tax return.
- Your Social Security number.
- Your spouse’s name and Social Security number, when applicable.
- Confirmation that you were a New York State resident for the entire tax year.
- Information about your volunteer firefighter or ambulance worker service.
- The name of your volunteer fire company, fire department, or ambulance company.
- The organization’s complete address.
- Information about any real property tax exemption received in connection with volunteer service.
- Your New York State Form IT-201 information.
It is also helpful to keep relevant volunteer membership and service records available so you can verify that you meet the full-year eligibility requirements. The form does not list these records as mandatory attachments.
How To Complete Form IT-245
Form IT-245 contains four main parts. Each part collects specific information needed to establish eligibility and calculate the credit.
Part 1: Enter Identifying Information
Part 1 collects the personal identification details of the taxpayer and spouse. Enter the information carefully and make sure it agrees with the names and Social Security numbers reported on your New York State income tax return.
Your Name as Shown on Return
Enter your full name exactly as it appears on your New York State Form IT-201. Avoid using nicknames, shortened names, or a different spelling. Keeping the name consistent helps the tax department match the credit claim with your income tax return.
Your Social Security Number
Enter your Social Security number in the designated field. Check every digit before submitting the form because this number is used to identify your tax account and connect the credit claim to your return.
Spouse’s Name
If you are filing a joint return, enter your spouse’s full name as it appears on the joint income tax return. Make sure the spelling and name details are consistent with the information reported on Form IT-201.
Spouse’s Social Security Number
Enter your spouse’s Social Security number in the appropriate field. Verify that it belongs to the spouse identified in the previous field.
If you are filing separately, provide spouse information as applicable to your filing circumstances and follow the relevant New York State return instructions.
Part 2: Determine Eligibility
Part 2 is the eligibility section of Form IT-245. It contains three questions, each requiring you to select either the Yes or No checkbox.
Read every question carefully before selecting an answer. Your responses determine whether you can continue completing the form and how much credit you may claim.
Line 1: New York State Residency for the Entire Tax Year
This question determines whether you and, when applicable, your spouse meet the full-year New York State residency requirement.
Select Yes if you were a New York State resident throughout the entire tax year. If you are filing a joint return, both you and your spouse must have been New York State residents for the full year.
Select No if you did not meet the full-year residency requirement. For a joint return, select No if either spouse did not meet this requirement.
If you select No, you must stop completing the form because you do not qualify for this credit. You should not continue to the remaining eligibility questions.
Line 2: Your Volunteer Firefighter or Ambulance Worker Status
This question asks whether you personally served as an active volunteer firefighter or volunteer ambulance worker for the entire tax year without receiving a real property tax exemption related to that service.
Select Yes if both conditions apply:
- You were an active volunteer firefighter or ambulance worker throughout the entire tax year.
- You did not receive a real property tax exemption because of that volunteer service.
Select No if you were not an active volunteer for the entire year or received a real property tax exemption related to your volunteer service.
If you received a property tax exemption connected to your volunteer work, you cannot claim the credit based on that same service.
Your filing status determines what you should do next:
- Married filing jointly: Continue to Line 3, even if you selected No at Line 2, because your spouse may independently qualify.
- Any other filing status: If you selected No, stop because you do not qualify. If you selected Yes, continue to Part 3.
One important exception concerns jointly owned property. If a property tax exemption was granted because of another owner’s volunteer service, a different owner whose own volunteer service was not the basis for that exemption may still qualify.
Line 3: Spouse’s Volunteer Firefighter or Ambulance Worker Status
Complete Line 3 only if your filing status is Married filing jointly.
This question determines whether your spouse independently meets the volunteer service requirements for the credit.
Select Yes if your spouse:
- Was an active volunteer firefighter or ambulance worker throughout the entire tax year.
- Did not receive a real property tax exemption related to their volunteer service.
Select No if your spouse did not serve as an active volunteer for the entire year or received a property tax exemption connected to their volunteer service.
If both Line 2 and Line 3 are marked No, neither spouse qualifies for the credit, and you must stop completing the form.
If either Line 2 or Line 3 is marked Yes, you may continue to Part 3.
Remember that both spouses do not need to qualify to claim the credit on a joint return. One qualifying spouse may receive the $200 credit, while two qualifying spouses may receive the $400 credit.
Part 3: Enter Qualifying Information
Part 3 collects details about the individual who qualifies for the volunteer firefighters’ and ambulance workers’ credit. You must identify the qualifying volunteer and provide information about the organization where the individual performed volunteer service.
The section contains three information columns and space for two entries.
Name of Qualifying Volunteer
Enter the full name of the individual who meets the eligibility requirements.
For a joint return where both spouses qualify, identify each qualifying spouse in a separate row.
If only one spouse qualifies, enter that person’s name in the appropriate row.
Make sure the name matches the taxpayer or spouse information entered in Part 1.
Volunteer Fire Company/Department or Ambulance Company
Enter the official name of the volunteer organization associated with the qualifying service.
Depending on your volunteer role, provide the name of either:
- Your New York State volunteer fire company.
- Your New York State volunteer fire department.
- Your New York State ambulance company.
If you are an active volunteer for both a fire company or department and an ambulance company, you should enter the qualifying information for either organization, not both. You do not need to list both organizations for the same qualifying volunteer.
Address of Volunteer Fire Company/Department or Ambulance Company
Enter the complete address of the organization identified in the previous column.
Use the organization’s official address, including the street address, city, state, and ZIP code.
Double-check the address to ensure that it corresponds to the correct fire company, fire department, or ambulance company.
If both spouses qualify, provide the relevant organization information for each qualifying volunteer in the available rows.
Part 4: Determine Credit Amount
Part 4 calculates the total credit you are eligible to claim based on your answers to Lines 2 and 3.
Unlike the previous sections, this part does not require additional eligibility questions. You simply determine the appropriate credit amount and enter it on Line 4.
Line 4: Volunteer Firefighters’ and Ambulance Workers’ Credit Amount
Enter the credit amount based on the Yes answers you selected in Part 2.
Follow these rules:
- If you marked Yes at Line 2 but No at Line 3, enter $200.
- If you marked No at Line 2 but Yes at Line 3, enter $200.
- If you marked Yes at both Lines 2 and 3, enter $400.
If both lines are marked No, you are not eligible to claim this credit and should not complete the credit calculation.
For example, if only the taxpayer qualifies as a volunteer firefighter, the amount entered on Line 4 should be $200. If both the taxpayer and spouse qualify as active volunteer ambulance workers, the amount should be $400.
Enter the applicable amount in the space provided on Line 4, including the cents as shown in the form.
Reporting the Line 4 Amount on Form IT-201-ATT
After calculating the credit, transfer the amount from Line 4 to Form IT-201-ATT, line 12.
You must also enter credit code 354 in the designated code field on Form IT-201-ATT, line 12.
Make sure the amount and code are entered correctly. This step ensures that the credit calculated on Form IT-245 is properly reported with your New York State income tax return.
Important Rules to Remember When Filing Form IT-245
Before submitting the form, keep these important eligibility and filing rules in mind:
Full-Year Residency Is Required
You must have been a New York State resident for the entire tax year. For married couples filing jointly, both spouses must satisfy the residency requirement.
Volunteer Service Must Cover the Entire Tax Year
Being a volunteer firefighter or ambulance worker for only part of the year does not satisfy the full-year service requirement.
Property Tax Exemption Can Affect Eligibility
You cannot claim this credit if you receive a real property tax exemption related to your volunteer service. However, another property owner whose volunteer service was not the basis for the exemption may still qualify.
Only Qualifying Volunteers Should Be Listed
Part 3 should identify the individuals who meet the eligibility requirements. When both spouses qualify, provide their information separately.
Do Not Report Both Types of Organizations for the Same Volunteer
If you serve as both a volunteer firefighter and an ambulance worker, identify either the fire organization or ambulance company in Part 3. Do not enter both organizations for the same person.
Form IT-245 Must Accompany Form IT-201
Do not treat Form IT-245 as a separate income tax return. Submit it with your New York State Form IT-201 and report the calculated amount and code 354 on Form IT-201-ATT, line 12.
Final Review Before Filing
Before submitting Form IT-245, review every section to make sure the information is complete and accurate.
Use the following checklist:
- Your name matches the name reported on Form IT-201.
- Your Social Security number is entered correctly.
- Your spouse’s name and Social Security number are provided when applicable.
- You were a New York State resident for the entire tax year.
- Both spouses meet the residency requirement if filing jointly.
- You were an active volunteer firefighter or ambulance worker for the entire tax year, if claiming the credit.
- Your qualifying volunteer service was not the basis for a real property tax exemption received by you.
- You answered Lines 1, 2, and 3 according to your eligibility and filing status.
- You stopped completing the form if you failed the residency requirement or neither spouse qualified.
- The correct qualifying volunteer’s name is entered in Part 3.
- The correct fire company, fire department, or ambulance company is identified.
- The organization’s complete address is provided.
- You have not listed both a fire organization and an ambulance company for the same qualifying volunteer.
- Line 4 shows $200 if one spouse qualifies or $400 if both spouses qualify on a joint return.
- The credit amount is transferred correctly to Form IT-201-ATT, line 12.
- Credit code 354 is entered on Form IT-201-ATT, line 12.
- Form IT-245 is included with your New York State Form IT-201 return.
- If filing married filing separately and both spouses qualify, each spouse has completed a separate Form IT-245 with their respective Form IT-201.
Completing Form IT-245 accurately helps eligible New York State volunteer firefighters and ambulance workers receive the tax credit available for their community service. Review the eligibility questions carefully, provide complete volunteer organization information, calculate the correct credit amount, and make sure the credit is properly reported on your New York State income tax return.