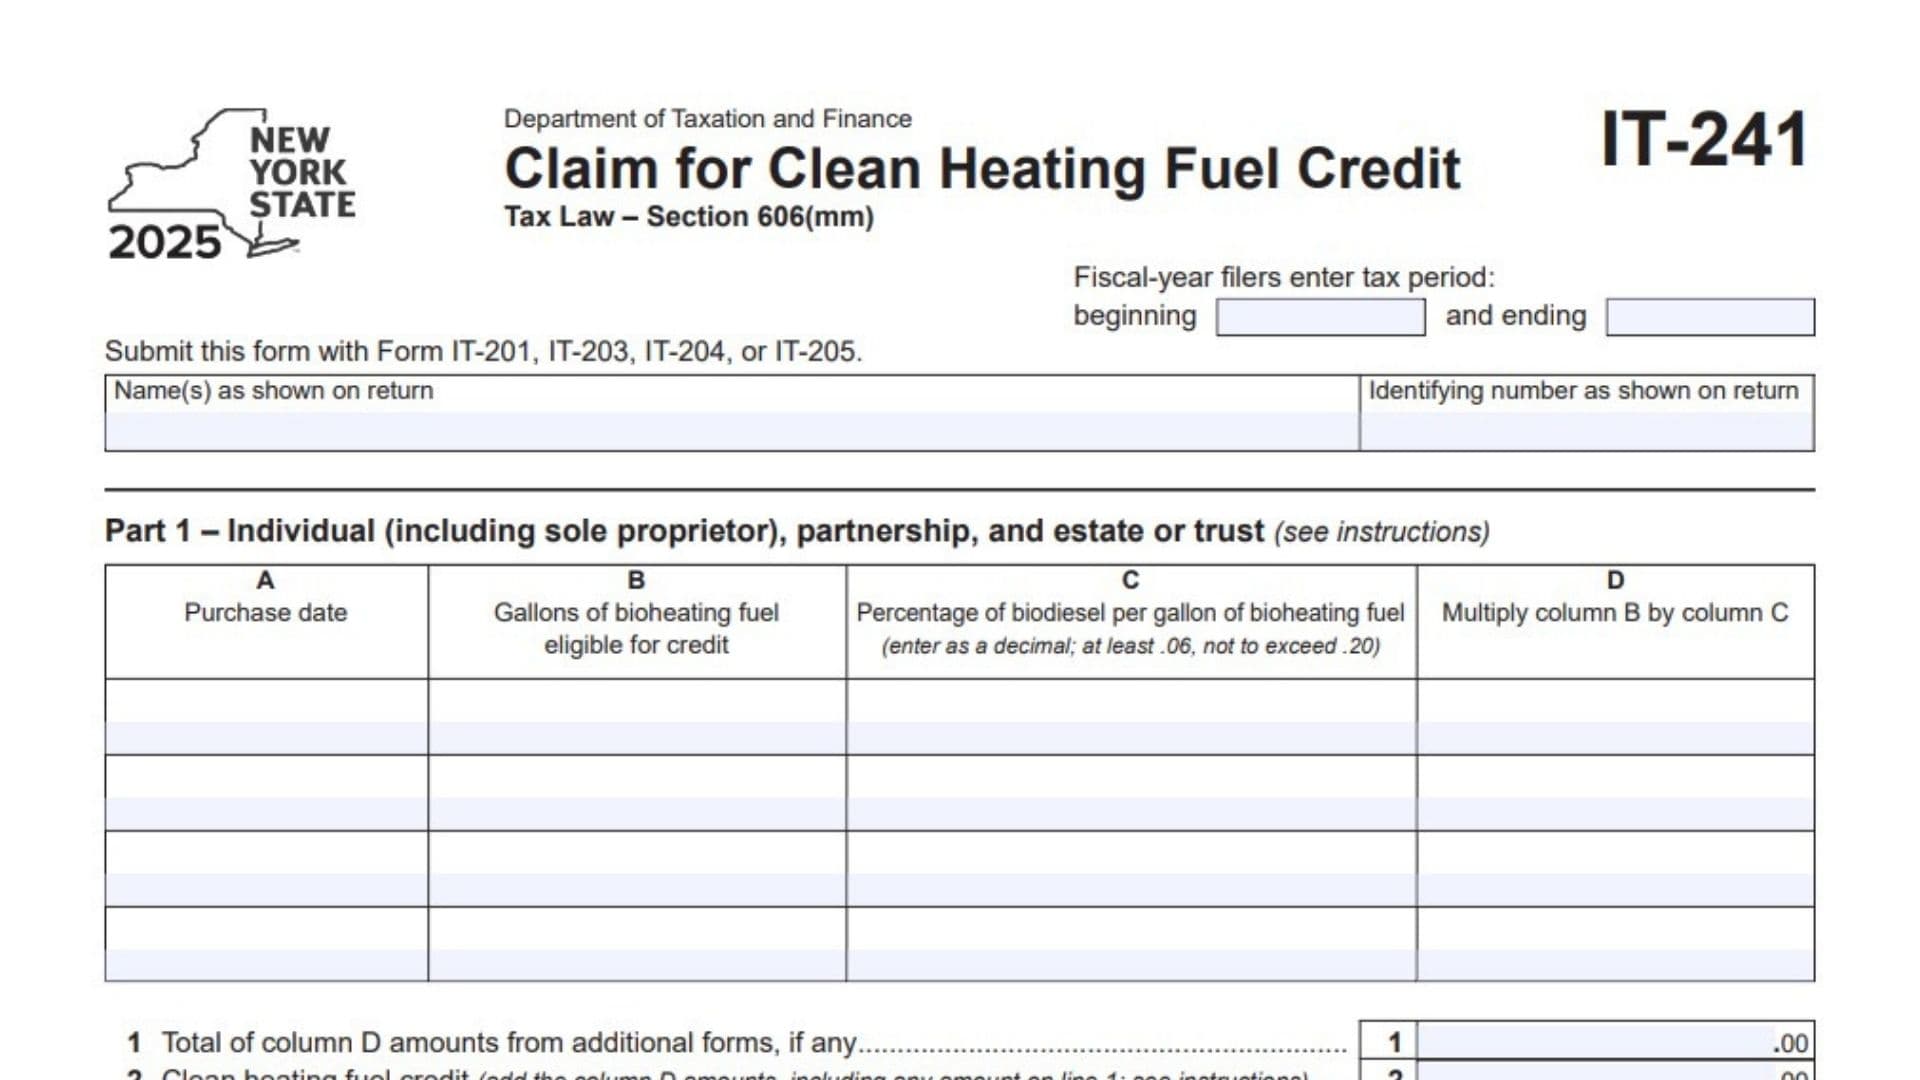
New York Form IT-241, officially titled Claim for Clean Heating Fuel Credit, is a tax form used to calculate and claim the clean heating fuel credit under New York Tax Law Section 606(mm). The 2025 form provides a way for eligible individuals, sole proprietors, partnerships, estates, and trusts to report qualifying purchases of bioheating fuel and determine the credit available based on the quantity purchased and the percentage of biodiesel contained in the fuel.
The form focuses on purchases of bioheating fuel that meet the applicable biodiesel percentage requirements. Taxpayers must report the purchase date, the number of gallons eligible for the credit, and the percentage of biodiesel per gallon. The biodiesel percentage must be entered as a decimal and must be at least 0.06 but cannot exceed 0.20. The credit calculation is based on multiplying the eligible gallons by the applicable biodiesel percentage.
Form IT-241 also accommodates taxpayers who receive an allocated share of the clean heating fuel credit through a partnership, New York S corporation, estate, or trust. For these situations, the form collects information about the entity distributing the credit and calculates the taxpayer’s allocated share. Separate sections are provided for partners, S corporation shareholders, beneficiaries, and fiduciaries.
The form is divided into five parts. Part 1 calculates the credit based on qualifying bioheating fuel purchases. Part 2 identifies partnerships, New York S corporations, estates, and trusts from which the taxpayer received an allocated credit. Part 3 calculates the taxpayer’s share of the credit received through these entities. Part 4 records the allocation of credit between beneficiaries and fiduciaries. Part 5 combines the applicable credit amounts to determine the final clean heating fuel credit.
Form IT-241 is a supporting tax credit form rather than a standalone income tax return. It must be submitted with Form IT-201, IT-203, IT-204, or IT-205, depending on the taxpayer’s filing circumstances. Completing the form accurately is important because the credit depends on eligible fuel purchases, biodiesel concentration, entity-level allocations, and the correct transfer of amounts between the different parts.
How To File Form IT-241
New York Form IT-241 must be submitted with the taxpayer’s applicable New York income tax return. It is not filed as an independent income tax return.
The 2025 form identifies four possible filing destinations:
- Form IT-201: For applicable New York State resident individual income tax filers.
- Form IT-203: For applicable nonresident and part-year resident individual income tax filers.
- Form IT-204: For applicable partnership filers.
- Form IT-205: For applicable fiduciary income tax filers.
Choose the appropriate return based on the taxpayer’s filing status and circumstances.
Information To Prepare Before Completing Form IT-241
Gather the following information before starting:
- Taxpayer’s legal name as shown on the applicable income tax return.
- Taxpayer’s identifying number.
- Applicable calendar or fiscal tax year.
- Beginning and ending dates for fiscal-year filers.
- Dates of qualifying bioheating fuel purchases.
- Number of gallons eligible for the credit for each purchase.
- Biodiesel percentage per gallon for each purchase.
- Supporting fuel purchase records.
- Names of partnerships, New York S corporations, estates, or trusts distributing the credit.
- Employer Identification Numbers (EINs) of those entities.
- Type of entity associated with each credit allocation.
- Partnership credit allocation information.
- S corporation shareholder credit allocation information.
- Beneficiary credit allocation information.
- Beneficiary names and identifying numbers, where applicable.
- Fiduciary credit allocation information.
Important Filing Considerations
Eligible Bioheating Fuel Purchases
Part 1 requires information about each qualifying bioheating fuel purchase. Keep purchase records showing the date, eligible gallons, and biodiesel percentage.
Biodiesel Percentage Requirement
The biodiesel percentage must be entered as a decimal. The form specifies a minimum of 0.06 and a maximum of 0.20.
Additional Forms
If the taxpayer has more qualifying purchase entries than the available spaces allow, additional Forms IT-241 may be used. The totals must be carried to line 1.
Credit Received Through Another Entity
Taxpayers receiving the credit through a partnership, New York S corporation, estate, or trust must complete the applicable sections of Parts 2 and 3.
Fiduciary Allocations
Fiduciaries must complete Part 4 to report the allocation of the credit between beneficiaries and the fiduciary.
Fiscal-Year Filers
Fiscal-year taxpayers must enter the beginning and ending dates of their tax period in the designated fields.
How To Complete New York Form IT-241
Form IT-241 contains taxpayer identification fields and five parts covering qualifying fuel purchases, entity information, allocated credits, beneficiary distributions, and the final credit calculation.
Complete the identification section first, followed by the parts applicable to the taxpayer’s circumstances.
Tax Year And Taxpayer Identification
Tax Year
The 2025 version of Form IT-241 applies to the 2025 tax year.
Calendar-year filers should use the applicable calendar year. Fiscal-year filers must enter the beginning and ending dates of their tax period in the spaces provided.
Name(s) As Shown On Return
Enter the taxpayer’s full legal name exactly as it appears on the associated New York income tax return.
For joint returns, enter the names as shown on the main return.
Identifying Number As Shown On Return
Enter the taxpayer’s identifying number exactly as it appears on the associated income tax return.
Use the identification number associated with the taxpayer claiming the credit.
Part 1: Individual, Partnership, And Estate Or Trust
Part 1 calculates the clean heating fuel credit based on qualifying bioheating fuel purchases.
It provides a table with four columns, labeled A through D. Each row represents a separate purchase of eligible bioheating fuel.
For each purchase, the taxpayer must report the purchase date, eligible gallons, biodiesel percentage, and resulting calculation.
Understanding The Columns In Part 1
Column A: Purchase Date
Enter the date on which the qualifying bioheating fuel was purchased.
Use the actual purchase date shown on the relevant purchase documentation.
If multiple qualifying purchases were made during the tax year, enter each purchase separately.
Column B: Gallons Of Bioheating Fuel Eligible For Credit
Enter the number of gallons of bioheating fuel eligible for the credit for the corresponding purchase.
Use the eligible gallon quantity supported by the purchase records.
Do not include gallons that do not qualify for the credit.
Column C: Percentage Of Biodiesel Per Gallon Of Bioheating Fuel
Enter the biodiesel percentage contained in each gallon of the purchased bioheating fuel.
The form requires this percentage to be entered as a decimal.
The permitted range is:
- Minimum: 0.06.
- Maximum: 0.20.
For example, a biodiesel concentration of 6% is entered as 0.06, while a concentration of 20% is entered as 0.20.
Ensure that the decimal entered falls within the range specified on the form.
Column D: Multiply Column B By Column C
Multiply the eligible gallons reported in column B by the biodiesel percentage entered in column C.
The calculation is:
\[ \text{Column D}=\text{Column B}\times\text{Column C} \]
Enter the resulting amount in column D.
Repeat this calculation separately for every qualifying purchase reported in Part 1.
Individual Bioheating Fuel Purchase Entries
Purchase Entry 1
Enter the first qualifying purchase date in column A, eligible gallons in column B, and biodiesel percentage in column C.
Multiply columns B and C and report the result in column D.
Purchase Entry 2
Enter the second qualifying purchase using the same four-column structure.
Ensure that the purchase date, gallon quantity, and biodiesel percentage correspond to the same transaction.
Purchase Entry 3
Report the third qualifying bioheating fuel purchase, if applicable.
Calculate the amount in column D by multiplying the eligible gallons by the applicable biodiesel percentage.
Purchase Entry 4
Enter the fourth qualifying purchase, if applicable.
Complete all four columns and verify the calculation.
The form provides four purchase rows. If additional qualifying purchases need to be reported, use additional Forms IT-241 as applicable.
Part 1: Credit Calculation
Line 1: Total Of Column D Amounts From Additional Forms, If Any
If additional Forms IT-241 have been completed, enter the combined column D amounts from those forms on line 1.
This line allows taxpayers to include qualifying purchase calculations that exceed the four entries available on the main form.
If no additional Forms IT-241 are used, there is no additional-form amount to include.
Line 2: Clean Heating Fuel Credit
Add all amounts reported in column D for the current form and include the amount entered on line 1, if applicable.
The calculation is:
\[ \text{Line 2}= \text{Current Form Column D Total}+\text{Line 1} \]
Enter the combined amount on line 2.
This represents the clean heating fuel credit calculated from the qualifying bioheating fuel purchases reported in Part 1.
The form provides different transfer instructions depending on the taxpayer’s role:
- Fiduciaries: Include the line 2 amount on the Total line of Part 4, column C.
- All Others: Enter the line 2 amount on Part 5, line 7.
Part 2: Partnership, New York S Corporation, Estate, And Trust Information
Part 2 identifies the partnerships, New York S corporations, estates, and trusts from which the taxpayer received a share of the clean heating fuel credit.
Complete this section when the taxpayer is a partner, shareholder, or beneficiary who received an allocated credit from one or more of these entities.
The form provides three columns and multiple rows for reporting the entities.
Understanding The Columns In Part 2
Column A: Name Of Entity
Enter the full legal name of the partnership, New York S corporation, estate, or trust from which the taxpayer received the credit.
Use the name shown in the relevant tax documentation.
Column B: Type
Enter the applicable entity classification using the codes specified on the form:
- P: Partnership.
- S: New York S corporation.
- ET: Estate or trust.
Use the correct code for each entity.
Column C: Employer Identification Number
Enter the federal Employer Identification Number (EIN) of the partnership, S corporation, estate, or trust.
Verify the EIN against the entity’s tax documentation.
Reporting Multiple Entities
Partnership Entry
If the taxpayer received a clean heating fuel credit from a partnership, enter the partnership’s name, use P in column B, and provide its EIN in column C.
New York S Corporation Entry
If the taxpayer received an allocated credit from a New York S corporation, enter its legal name, use S as the entity type, and provide its EIN.
Estate Or Trust Entry
If the taxpayer received the credit as a beneficiary of an estate or trust, enter the entity’s name, use ET, and provide its EIN.
Additional Entity Entries
Repeat the process for every applicable partnership, New York S corporation, estate, or trust from which a credit was received.
Ensure that the entity information is complete and agrees with the supporting allocation records.
Part 3 calculates the clean heating fuel credit received through partnerships, New York S corporations, estates, and trusts.
The section contains four numbered lines, covering the different types of allocated credit.
Complete the lines that apply to the taxpayer’s circumstances.
Line 3: Enter Your Share Of The Credit From Your Partnership
Partners must enter their allocated share of the clean heating fuel credit received from a partnership.
Use the amount assigned to the taxpayer by the partnership.
If credit was received from multiple partnerships, combine the applicable allocations and report the total on this line.
Line 4: Enter Your Share Of The Credit From Your S Corporation
Shareholders of New York S corporations must enter their allocated share of the clean heating fuel credit received from the S corporation.
Use the credit amount reported in the applicable shareholder tax documentation.
If multiple S corporations allocated credit to the taxpayer, combine the applicable amounts and enter the total.
Line 5: Enter Your Share Of The Credit From The Fiduciary’s Form IT-241, Part 4, Column C
Beneficiaries must enter the amount of clean heating fuel credit allocated to them by an estate or trust.
Transfer the beneficiary’s share from the fiduciary’s Form IT-241, Part 4, column C.
Ensure that the amount agrees with the fiduciary’s allocation records.
Line 6: Total
Add the amounts reported on lines 3, 4, and 5.
The calculation is:
\[ \text{Line 6}=\text{Line 3}+\text{Line 4}+\text{Line 5} \]
Enter the combined amount on line 6.
This represents the total clean heating fuel credit received through partnerships, S corporations, estates, and trusts.
The form provides different transfer instructions:
- Fiduciaries: Include the line 6 amount on the Total line of Part 4, column C.
- All Others: Enter the line 6 amount on Part 5, line 8.
Part 4 is used by fiduciaries to report how the clean heating fuel credit is allocated between beneficiaries and the fiduciary.
The section contains three columns:
- Column A: Beneficiary’s name.
- Column B: Identifying number.
- Column C: Share of clean heating fuel credit.
Complete this section when an estate or trust is distributing the credit among beneficiaries or retaining a portion for the fiduciary.
Understanding The Columns In Part 4
Column A: Beneficiary’s Name
Enter the beneficiary’s name exactly as it appears on Form IT-205, Schedule C.
Use the same name reported on the related fiduciary income tax return.
Column B: Identifying Number
Enter the beneficiary’s identifying number.
Use the identification number associated with the beneficiary’s tax records.
Column C: Share Of Clean Heating Fuel Credit
Enter the amount of the clean heating fuel credit allocated to the beneficiary.
Use the applicable allocation information to determine each beneficiary’s share.
Part 4: Credit Allocation Entries
Total: Fiduciaries, Enter The Amount From Line 2 Plus The Amount From Line 6
The Total line combines the credit calculated directly through Part 1 with any credit received through partnerships, S corporations, or other fiduciary allocations.
Add the amounts from:
- Part 1, line 2.
- Part 3, line 6.
The calculation is:
\[ \text{Part 4 Total}=\text{Line 2}+\text{Line 6} \]
Enter the combined amount in column C of the Total line.
This represents the total credit available for the fiduciary’s allocation process.
Beneficiary Entry 1
Enter the first beneficiary’s name in column A, identifying number in column B, and allocated credit amount in column C.
Beneficiary Entry 2
If another beneficiary receives a share of the clean heating fuel credit, enter that beneficiary’s name, identifying number, and allocated credit amount.
Additional Beneficiary Entries
Use the remaining available rows to report additional beneficiaries.
Make sure that each beneficiary’s allocation is supported by the relevant fiduciary records.
Fiduciary: Share Of Credit
Enter the portion of the clean heating fuel credit allocated to the fiduciary in the Fiduciary line of column C.
This amount is transferred to Part 5, line 9.
The form does not provide a separate calculation formula for determining each beneficiary’s allocation percentage. The amounts should be determined using the applicable fiduciary allocation records.
Part 5: Computation Of Clean Heating Fuel Credit
Part 5 combines the clean heating fuel credit amounts calculated in the earlier sections.
The final calculation depends on whether the taxpayer is an individual, partnership, partner, S corporation shareholder, beneficiary, or fiduciary.
The section contains lines 7 through 10.
Line 7: Individual And Partnership
Individuals, including sole proprietors, and partnerships must enter the amount, or their share of the amount, from Part 1, line 2.
This amount represents the clean heating fuel credit calculated from qualifying bioheating fuel purchases.
If the taxpayer is claiming the credit directly, transfer the applicable amount from line 2.
Line 8: Partner, S Corporation Shareholder, Beneficiary
Partners, shareholders of New York S corporations, and beneficiaries must enter the amount from Part 3, line 6.
This amount represents the combined credit received through the applicable partnerships, S corporations, estates, and trusts.
Line 9: Fiduciary
Fiduciaries must enter the amount from the Fiduciary line of Part 4, column C.
This represents the clean heating fuel credit allocated to the fiduciary.
Line 10: Total Clean Heating Fuel Credit
Add lines 7, 8, and 9.
The calculation is:
\[ \text{Line 10}=\text{Line 7}+\text{Line 8}+\text{Line 9} \]
Enter the resulting total on line 10.
This is the final clean heating fuel credit calculated on Form IT-241.
Use the applicable New York income tax return instructions to determine how the amount is reported on the associated return.
Final Review Before Filing
Before submitting New York Form IT-241, review all five parts and verify that the fuel purchase information, biodiesel percentages, entity details, allocated credit amounts, and final calculations are accurate.
Use the following checklist to conduct a final review.
Taxpayer Identification
- Confirm the correct calendar or fiscal tax year.
- Enter the beginning and ending dates for fiscal-year filers.
- Verify the taxpayer’s name as shown on the main return.
- Check the taxpayer’s identifying number.
- Confirm that the correct main income tax return has been selected.
Part 1: Bioheating Fuel Purchases
- Enter the purchase date for every qualifying transaction.
- Verify the eligible gallons in column B.
- Enter the biodiesel percentage as a decimal in column C.
- Confirm that each percentage is at least 0.06 and does not exceed 0.20.
- Multiply columns B and C correctly.
- Verify the resulting amounts in column D.
- Include additional Form IT-241 calculations on line 1, where applicable.
- Recalculate the total clean heating fuel credit on line 2.
- Confirm the correct transfer destination for line 2.
Part 2: Entity Information
- List all partnerships that allocated credit.
- List all New York S corporations that allocated credit.
- Include applicable estates and trusts.
- Verify each entity’s legal name.
- Enter P for partnerships.
- Enter S for New York S corporations.
- Enter ET for estates or trusts.
- Check every entity’s EIN.
Part 3: Allocated Credit
- Verify partnership credit on line 3.
- Confirm S corporation credit on line 4.
- Check beneficiary credit from Part 4, column C, on line 5.
- Recalculate the combined amount on line 6.
- Confirm the correct transfer destination for fiduciaries and other taxpayers.
Part 4: Beneficiary And Fiduciary Allocation
- Verify each beneficiary’s name against Form IT-205, Schedule C.
- Confirm beneficiary identifying numbers.
- Check each beneficiary’s allocated credit in column C.
- Include Part 1, line 2, and Part 3, line 6, in the Total line.
- Verify the fiduciary’s allocated credit amount.
- Confirm that beneficiary and fiduciary allocations agree with supporting records.
Part 5: Final Credit Calculation
- Confirm line 7 agrees with Part 1, line 2, where applicable.
- Verify line 8 agrees with Part 3, line 6.
- Check line 9 against Part 4, Fiduciary line, column C.
- Recalculate the final credit on line 10.
- Ensure that the total reflects the correct taxpayer classification.
Final Filing Checks
- Ensure all applicable parts have been completed.
- Reconcile purchase information with fuel purchase records.
- Verify the biodiesel percentages.
- Confirm that all entity allocations are supported by relevant tax documentation.
- Attach additional Forms IT-241 if required.
- Submit Form IT-241 with Form IT-201, IT-203, IT-204, or IT-205, as applicable.
- Retain copies of the completed form and supporting purchase and allocation records.
Important Filing Reminder
New York Form IT-241 is a supporting tax credit form used to calculate and claim the Clean Heating Fuel Credit under Tax Law Section 606(mm).
The most important calculation in Part 1 is multiplying the eligible gallons of bioheating fuel by the applicable biodiesel percentage. The form requires that percentage to be entered as a decimal between 0.06 and 0.20.
Taxpayers receiving the credit through partnerships, New York S corporations, estates, or trusts must also complete the relevant allocation sections. Fiduciaries must report beneficiary and fiduciary shares separately before completing the final calculation.
Accurate reporting of qualifying fuel purchases, biodiesel percentages, entity allocations, and beneficiary distributions is essential for correctly calculating and claiming the New York Clean Heating Fuel Credit for the 2025 tax year.