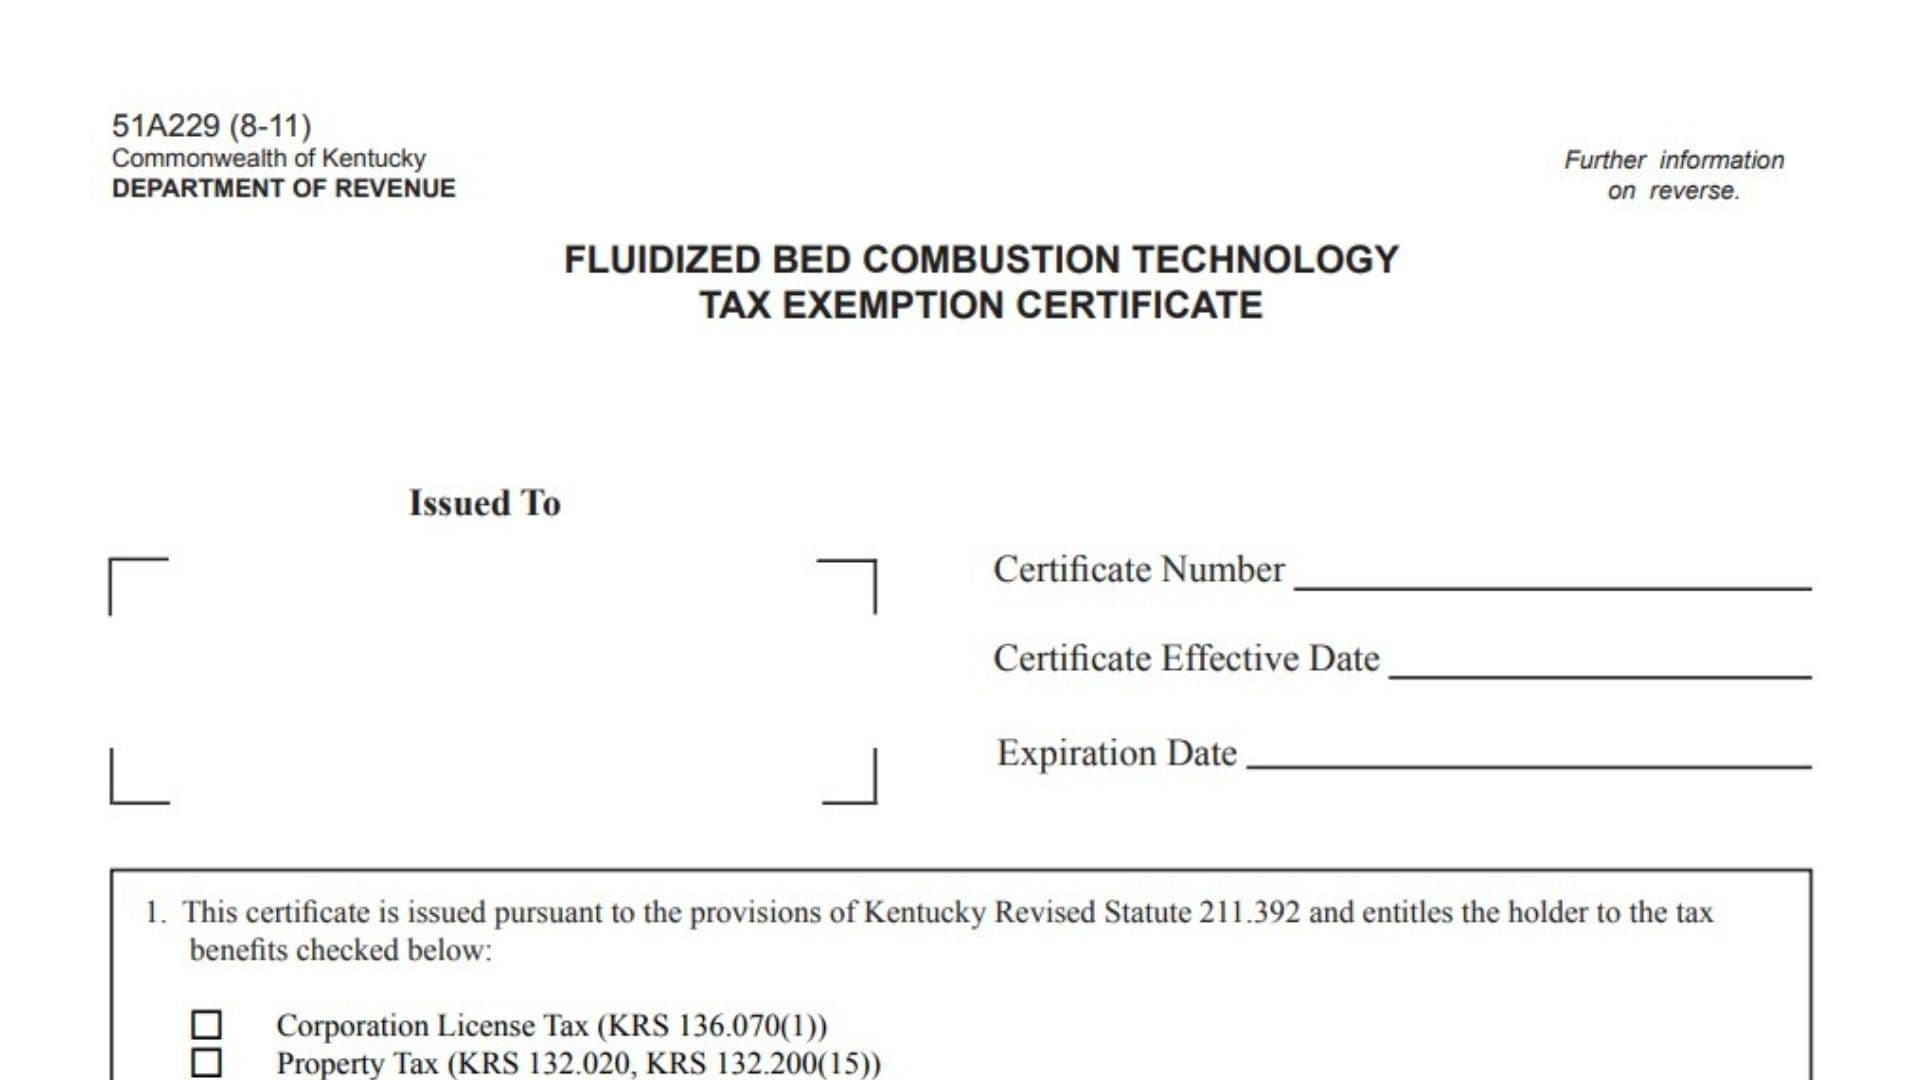
Kentucky Form 51A229 is the Fluidized Bed Combustion Technology Tax Exemption Certificate issued by the Kentucky Department of Revenue. This certificate is used to identify qualifying fluidized bed energy production facilities and provide eligible tax benefits under Kentucky Revised Statutes (KRS) 211.390 and KRS 211.392. The certificate provides tax benefits that may include corporation license tax benefits, property tax benefits, and sales and use tax benefits. The specific benefits available depend on the approvals granted and are limited to the facility location listed on the certificate and the items identified as qualifying. This certificate records important details about the approved facility, including its location, construction cost, estimated market value, qualifying items, certificate number, effective date, and expiration date. It serves as documentation that the listed facility or equipment has been reviewed and determined to qualify for exemption benefits.
How To File Form 51A229
Form 51A229 is issued after review and approval of an application for a qualifying fluidized bed energy production facility. The certificate holder should maintain the certificate as proof of eligibility for approved tax benefits.
For sales and use tax benefits, the certificate holder or the certificate holder together with a purchasing construction contractor may purchase qualifying materials and equipment without paying sales tax when used for construction, installation, or erection of the approved fluidized bed energy production facility.
The certificate holder or authorized purchasing contractor must provide a Certificate of Exemption for Fluidized Bed Energy Production Facility, Revenue Form 51A230, to the supplier as evidence supporting the tax-free purchase.
Before using the certificate, verify that:
- The facility location matches the approved location.
- The purchases relate only to qualifying items listed on the certificate.
- The required exemption documentation is provided to suppliers.
How To Complete Form 51A229
Certificate Identification Information
This section identifies the certificate holder and approval details.
Issued To
Enter the name of the person, company, or organization receiving the certificate.
Certificate Number
Enter the identification number assigned to the approved exemption certificate.
Certificate Effective Date
Enter the date on which the exemption certificate becomes valid.
Expiration Date
Enter the date on which the certificate expires.
Section 1: Approved Tax Benefits
Section 1 identifies the tax benefits available under the certificate. The certificate holder may receive the benefits selected on the form.
Corporation License Tax
This benefit applies to qualifying corporation license tax treatment under KRS 136.070(1).
For corporation license tax purposes, certified fluidized bed energy production facility property is excluded from the numerator and denominator of the property factor calculation.
Property Tax
This benefit applies to qualifying property tax treatment under KRS 132.020 and KRS 132.200(15).
Certified fluidized bed energy production facilities are subject to state tax treatment based on the applicable valuation rules. The actual cost of the facility and equipment is used for valuation purposes.
Facilities financed through industrial revenue bonds under KRS Chapter 103 may qualify for tax-exempt treatment.
Sales And Use Tax
This benefit applies to qualifying sales and use tax exemption treatment under KRS 139.480(20).
The exemption applies only to the approved facility location and qualifying items listed on the certificate.
Section 2: Location Of Facility
Location Of Facility
Enter the physical location of the fluidized bed energy production facility.
The tax benefits granted under the certificate are limited to this approved facility location.
Include complete location information such as:
- Street address
- City
- State
- ZIP code
Section 3: Estimated Or Actual Capitalized Cost Of Construction
Estimated Or Actual Capitalized Cost Of Construction Of The Facility
Enter the estimated or actual capitalized construction cost of the facility as determined by IRS guidelines.
This amount should represent the qualifying facility construction cost reported as part of the application process.
Section 4: Estimated Market Value Of Facility
Estimated Market Value Of The Facility
Enter the estimated market value of the facility for which the exemption application was submitted.
This value is reported for the approved facility and is part of the certificate information.
Section 5: Qualifying Items Approved For Exemption
Approved Qualifying Items
This section lists the machinery, equipment, or other items that have been reviewed and approved for exemption under KRS 211.390 and KRS 211.392.
Only items identified in this section qualify for the approved tax benefits.
The certificate holder should confirm that purchases match the approved items before claiming exemption benefits.
Supervisor Approval Section
Supervisor Signature
The authorized supervisor from the Division of Sales and Use Tax signs the certificate after approval.
Date
The approval date is entered by the Department of Revenue representative.
Explanatory Notes For Tax Benefits
Corporation License Tax
The certified facility receives special treatment for corporation license tax calculations. The certified fluidized bed energy production facility property is excluded when calculating the property factor used for corporation license tax purposes.
Property Tax
Certified fluidized bed energy production facilities are subject to specific state property tax rules. The facility’s actual cost, including qualifying equipment, is used for valuation purposes.
Sales And Use Tax
The certificate allows qualifying materials and equipment purchases for construction, installation, or erection of the approved facility to be made without sales tax when proper exemption documentation is provided.
Final Review Before Using Form 51A229
Before relying on the Fluidized Bed Combustion Technology Tax Exemption Certificate, verify the following:
- Confirm the certificate is issued to the correct entity.
- Check that the certificate number and effective dates are accurate.
- Verify the approved facility location.
- Confirm that the tax benefit being claimed is listed on the certificate.
- Ensure purchases relate only to qualifying items listed on the certificate.
- Maintain supporting records for all exempt purchases.
- Provide the required exemption certificate documentation to suppliers.
- Confirm that contractors and vendors have proper evidence supporting tax-free purchases.
- Review expiration dates before claiming benefits.
The certificate holder should use the exemption only for approved facilities and qualifying items identified through the Kentucky Department of Revenue approval process.