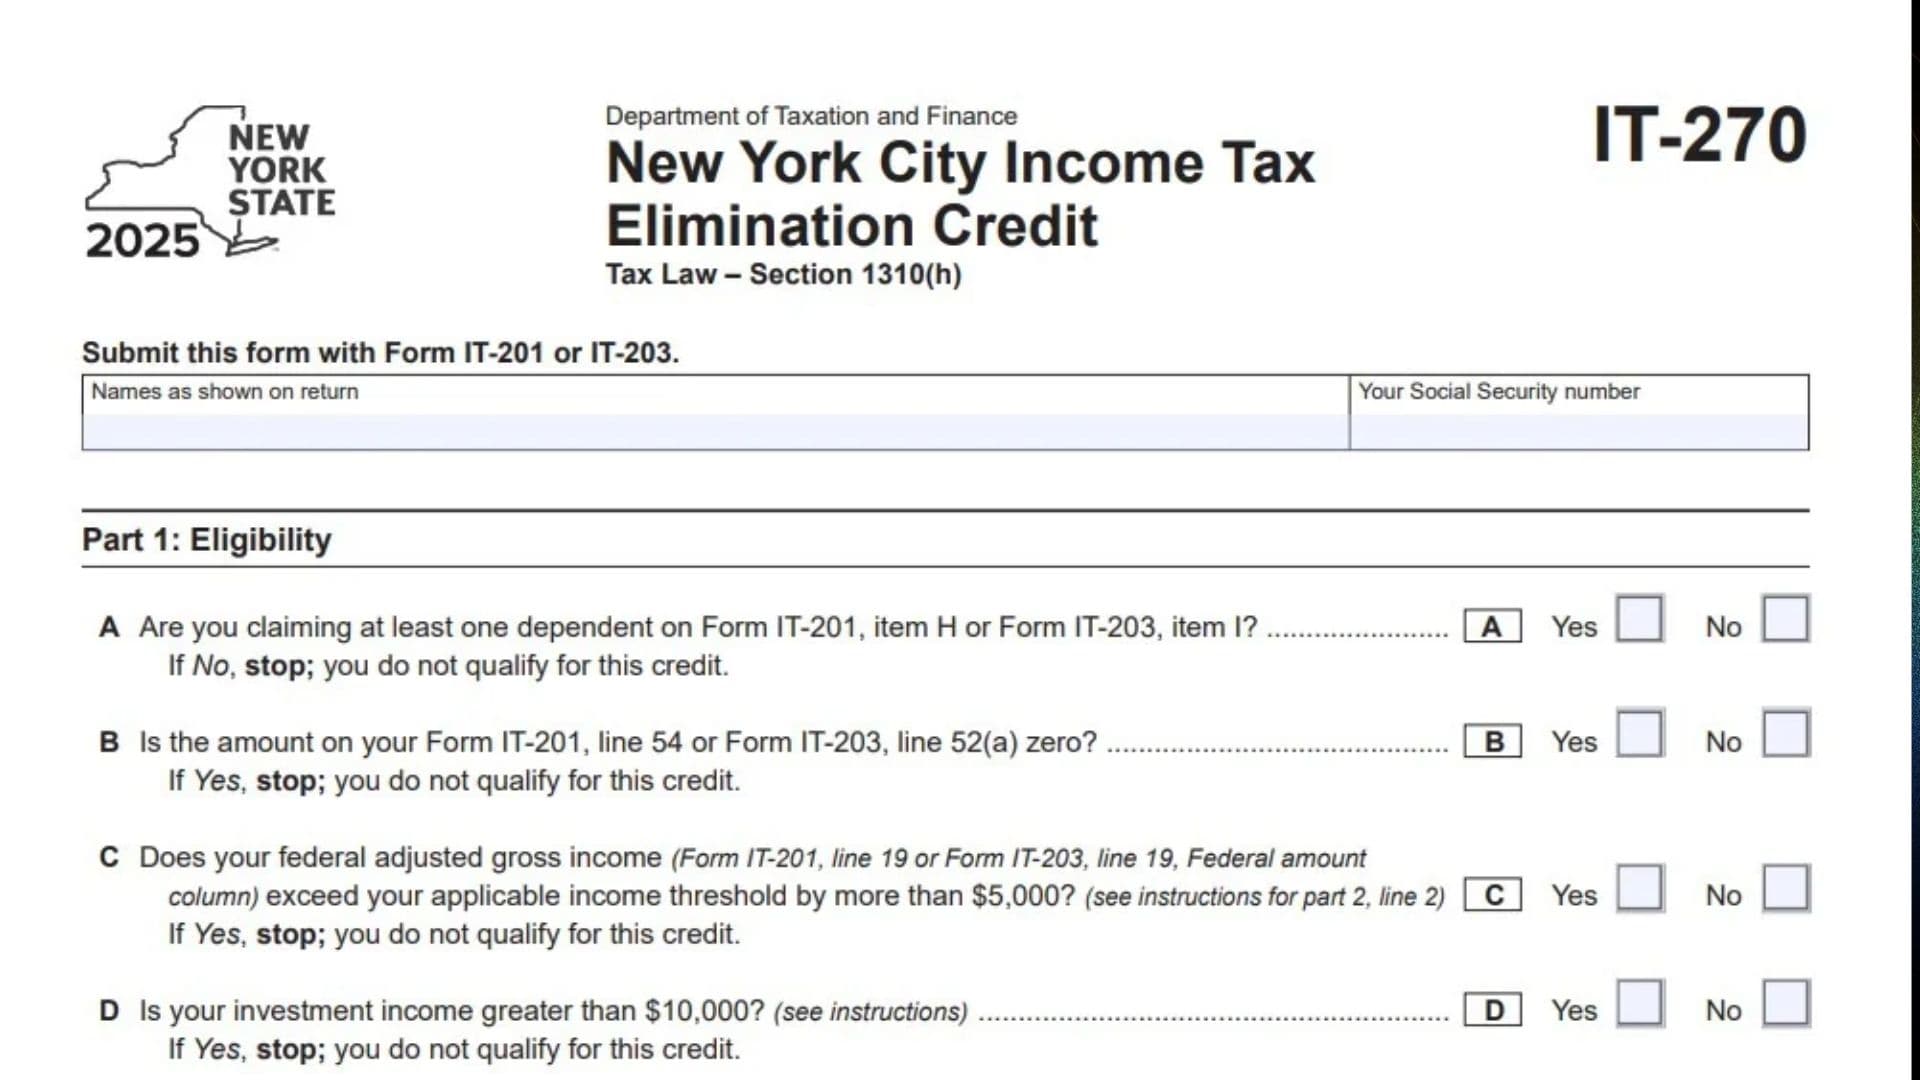
New York Form IT-270, officially known as the New York City Income Tax Elimination Credit, is a tax form issued by the New York State Department of Taxation and Finance under Section 1310(h) of the New York Tax Law. It allows eligible full-year and part-year residents of New York City to claim a credit that can reduce or eliminate their New York City personal income tax liability. The credit is primarily intended to provide tax relief to eligible taxpayers who claim one or more dependents on their New York State income tax return. Eligibility depends on several factors, including the taxpayer’s filing status, number of dependents, federal adjusted gross income (FAGI), investment income, and whether the taxpayer claims a New York City or New York State Pass-Through Entity Tax (PTET) credit. The form contains two main parts. Part 1 establishes whether the taxpayer meets the eligibility requirements through five Yes/No questions. Part 2 calculates the allowable credit by comparing federal adjusted gross income with the applicable income threshold and adjusting the remaining New York City tax liability for other credits already claimed. The calculation also considers the refundable New York City child and dependent care credit and the New York City earned income credit. Depending on the taxpayer’s income, the credit may be available in full or reduced proportionally. Taxpayers whose federal adjusted gross income does not exceed the applicable income threshold generally receive a credit equal to their remaining eligible New York City tax liability after other applicable credits. Taxpayers whose income exceeds the threshold by no more than $5,000 may qualify for a partial credit. However, taxpayers whose income exceeds the threshold by more than $5,000 are not eligible. The form must be submitted with Form IT-201, Resident Income Tax Return, or Form IT-203, Nonresident and Part-Year Resident Income Tax Return. It is not designed to be filed independently. Completing Form IT-270 accurately is important because incorrect dependent information, income thresholds, investment income calculations, or credit amounts may result in an incorrect claim or processing delays.
Who Qualifies For The New York City Income Tax Elimination Credit?
For the 2025 tax year, taxpayers may qualify for the credit if they meet all the applicable eligibility requirements.
Generally, you must:
- Be a full-year or part-year resident of New York City.
- Claim at least one dependent on Form IT-201, Item H, or Form IT-203, Item I.
- Not claim a New York City or New York State Pass-Through Entity Tax (PTET) credit.
- Have federal adjusted gross income that does not exceed your applicable income threshold by more than $5,000.
- Have investment income of $10,000 or less.
- Have an eligible New York City income tax amount remaining for the credit calculation.
Meeting these requirements does not automatically mean you will receive the maximum credit. The final amount depends on the calculation in Part 2.
How The Credit Amount Is Determined
The credit calculation follows three possible income situations:
Income At Or Below The Applicable Threshold
If your federal adjusted gross income is equal to or below the applicable income threshold, you may receive the full credit equal to the remaining eligible New York City tax after other applicable credits.
Income Up To $5,000 Above The Threshold
If your federal adjusted gross income exceeds the applicable threshold by $5,000 or less, you may qualify for a partial credit.
The credit is reduced according to the percentage calculated on Line 5.
Income More Than $5,000 Above The Threshold
If your federal adjusted gross income exceeds the applicable threshold by more than $5,000, you are not eligible for this credit.
How To File Form IT-270
Form IT-270 must be submitted with your New York State income tax return.
Where To Submit Form IT-270
Submit the completed form with one of the following returns:
- Form IT-201: Resident Income Tax Return.
- Form IT-203: Nonresident and Part-Year Resident Income Tax Return.
Do not submit Form IT-270 as a separate tax return.
If you file electronically, include the applicable credit information as part of your electronic tax return. If you file by paper, include Form IT-270 with the applicable return.
Information To Prepare Before Completing Form IT-270
Gather the following information before starting:
- Your name as shown on your New York tax return.
- Your Social Security number.
- Your federal adjusted gross income.
- Your New York State filing status.
- The number of dependents claimed on your tax return.
- The applicable income threshold based on filing status and dependents.
- Your New York City income tax amount.
- Your investment income information.
- Any refundable New York City child and dependent care credit.
- Any New York City earned income credit.
- Information about any New York City or New York State PTET credit claimed.
Having these details ready will make the eligibility review and credit calculation easier.
How To Complete Form IT-270
Form IT-270 contains two sections:
- Part 1: Eligibility – Determines whether you qualify for the credit.
- Part 2: Credit Calculation – Calculates the amount of credit you can claim.
Complete Part 1 first. If you fail any of the eligibility requirements, you generally cannot continue with the credit claim.
Part 1: Eligibility
Part 1 contains five questions labeled A through E.
Each question must be answered Yes or No. Carefully review the instructions associated with each answer because certain responses require you to stop completing the form.
Name(s) As Shown On Return
Enter your full name exactly as it appears on Form IT-201 or Form IT-203.
If you are filing jointly, enter the names as shown on the joint tax return.
Make sure the information matches your primary return.
Your Social Security Number
Enter your Social Security number in the designated field.
Use the SSN associated with your New York State income tax return.
Check the number carefully before submitting the form.
Eligibility Questions
Question A: Are You Claiming At Least One Dependent?
Determine whether you are claiming at least one dependent on your New York State income tax return.
Use the following locations:
- Form IT-201, Item H.
- Form IT-203, Item I.
Select the appropriate Yes or No checkbox.
- Yes: You are claiming at least one dependent. Continue to Question B.
- No: You do not qualify for the credit.
If you select No, stop completing the form.
Question B: Is The Amount On Form IT-201, Line 54, Or Form IT-203, Line 52(a), Zero?
Check the applicable New York City income tax amount on your tax return.
Use:
- Form IT-201, Line 54, if filing as a full-year resident.
- Form IT-203, Line 52(a), if filing as a nonresident or part-year resident.
Select Yes if the applicable amount is zero.
- Yes: You are not eligible for the New York City Income Tax Elimination Credit. Stop completing the form.
- No: Continue to Question C.
Question C: Does Your Federal Adjusted Gross Income Exceed The Applicable Income Threshold By More Than $5,000?
Compare your federal adjusted gross income with the applicable income threshold based on your filing status and number of dependents.
Your federal adjusted gross income is reported on:
- Form IT-201, Line 19.
- Form IT-203, Line 19, Federal amount column.
To answer this question, first determine your applicable income threshold using the table in Part 2, Line 2 instructions.
Add $5,000 to that threshold.
If your federal adjusted gross income exceeds the resulting amount by any amount, select Yes.
- Yes: Your income is too high to qualify for this credit. Stop completing the form.
- No: Your income is within the permitted range. Continue to Question D.
For example, if your applicable threshold is $31,503, your maximum permitted income is $36,503.
If your federal adjusted gross income is $38,000, you exceed the permitted amount and cannot claim the credit.
Question D: Is Your Investment Income Greater Than $10,000?
Determine your total investment income for the tax year.
For most taxpayers, investment income includes:
- Taxable interest income from federal Form 1040, Line 2b.
- Tax-exempt interest income from federal Form 1040, Line 2a.
- Ordinary dividends from federal Form 1040, Line 3b.
- Net capital gains from federal Form 1040, Line 7a, if the amount is greater than zero.
Investment income may also include other income categories, such as:
- Rental income.
- Royalties.
- Income from passive activities.
Select the appropriate checkbox:
- Yes: Your investment income exceeds $10,000. You are not eligible for the credit.
- No: Your investment income is $10,000 or less. Continue to Question E.
Use the applicable federal investment income calculation rules when determining the total.
Question E: Are You Claiming A New York City Or New York State Pass-Through Entity Tax Credit (PTET)?
Determine whether you are claiming either of the following credits:
- New York City Pass-Through Entity Tax (NYC PTET) credit.
- New York State Pass-Through Entity Tax (NYS PTET) credit.
Select the appropriate checkbox.
- Yes: You are not eligible for the New York City Income Tax Elimination Credit. Stop completing the form.
- No: You may proceed to Part 2, provided you meet all the other eligibility requirements.
Part 2: Credit Calculation
Part 2 contains 11 numbered lines used to calculate the New York City Income Tax Elimination Credit.
The calculation begins with federal adjusted gross income and the applicable income threshold. It then determines the income-based reduction percentage and applies that percentage to the remaining eligible New York City tax.
Line-By-Line Credit Calculation
Line 1: Federal Adjusted Gross Income
Enter your federal adjusted gross income (FAGI).
Use the amount reported on:
- Form IT-201, Line 19.
- Form IT-203, Line 19, Federal amount column.
Enter the full amount in dollars and cents.
This amount is used to determine whether your income falls within the applicable eligibility range.
Line 2: Applicable Income Threshold Amount
Enter the income threshold that applies to your filing status and number of dependents.
The threshold is determined using the 2025 income threshold table below.
Select the correct amount based on your filing status and the number of dependents claimed on your New York State income tax return.
| Number Of Dependents | Married Filing Jointly Or Qualifying Surviving Spouse | Married Filing Separately, Single Or Head Of Household |
|---|---|---|
| 1 | $36,789 | $31,503 |
| 2 | $46,350 | $36,824 |
| 3 | $54,545 | $46,512 |
| 4 | $61,071 | $53,711 |
| 5 | $68,403 | $59,928 |
| 6 | $75,204 | $65,712 |
| 7 | $91,902 | $74,565 |
| 8 or more | $91,902 | $88,361 |
Enter the applicable threshold in Line 2.
Make sure you use the correct filing-status column and dependent count.
Line 3: Income Above The Applicable Threshold
Compare the amount on Line 1 with the amount on Line 2.
There are two possible situations:
- If Line 1 is less than or equal to Line 2, enter zero on Line 3.
- If Line 1 is greater than Line 2, subtract Line 2 from Line 1 and enter the difference.
The calculation is:
Line 1 − Line 2 = Line 3.
If the result is more than $5,000, stop. You do not qualify for the credit.
For example:
If Line 1 is $34,000 and Line 2 is $31,503:
$34,000 − $31,503 = $2,497.
Enter $2,497 on Line 3.
Line 4: Remaining Amount From The $5,000 Income Allowance
Subtract the amount on Line 3 from $5,000.
The calculation is:
$5,000 − Line 3 = Line 4.
Enter the result.
This amount determines how much of the original $5,000 income allowance remains available for the credit calculation.
For example:
If Line 3 is $2,497:
$5,000 − $2,497 = $2,503.
Enter $2,503 on Line 4.
Line 5: Income-Based Credit Percentage
Divide the amount on Line 4 by $5,000.
The calculation is:
Line 4 ÷ $5,000 = Line 5.
Enter the result as a decimal rounded to four decimal places.
For example:
$2,503 ÷ $5,000 = 0.5006.
Enter 0.5006 on Line 5.
This percentage determines the portion of your remaining New York City tax that can qualify for the credit.
If your federal adjusted gross income is equal to or below the applicable income threshold, Line 3 is zero, Line 4 is $5,000, and Line 5 is 1.0000.
If your income exceeds the threshold by exactly $5,000, Line 4 and Line 5 are zero.
Line 6: New York City Income Tax Amount
Enter the amount from the applicable New York State income tax return.
Use:
- Form IT-201, Line 54.
- Form IT-203, Line 52(a).
Enter the amount in dollars and cents.
This amount represents the New York City income tax used in the credit calculation.
Line 7: Refundable NYC Child And Dependent Care Credit
Enter the refundable New York City child and dependent care credit.
Use the applicable amount from:
- Form IT-216, Line 24.
- Form IT-216, Line 28.
Use the appropriate line based on your tax filing situation.
Enter the amount in dollars and cents.
This amount is included when determining the credits that have already reduced your eligible New York City tax.
Line 8: NYC Earned Income Credit
Enter your New York City earned income credit amount.
Use the applicable amount from:
- Form IT-215, Line 27.
- Form IT-209, Line 45.
Select the applicable source based on the credit form used.
Enter the amount in dollars and cents.
Line 9: Total Of Other Applicable Credits
Add the amounts reported on Lines 7 and 8.
The calculation is:
Line 7 + Line 8 = Line 9.
Enter the combined amount in dollars and cents.
This represents the total of the refundable New York City child and dependent care credit and the New York City earned income credit included in this calculation.
Line 10: Remaining New York City Tax After Other Credits
Subtract Line 9 from Line 6.
The calculation is:
Line 6 − Line 9 = Line 10.
Enter the resulting amount in dollars and cents.
This calculation determines the remaining New York City tax after accounting for the two credits reported on Lines 7 and 8.
If the amount on Line 10 is zero or less, you are not eligible to claim the New York City Income Tax Elimination Credit.
Do not complete this form or submit it with your tax return in that situation.
If the amount is positive, continue to Line 11.
Line 11: New York City Income Tax Elimination Credit
Multiply the amount on Line 10 by the percentage on Line 5.
The calculation is:
Line 10 × Line 5 = Line 11.
Enter the resulting amount in dollars and cents.
This is your final New York City Income Tax Elimination Credit.
Transfer the amount as follows:
- Form IT-201 filers: Enter the amount from Line 11 on Form IT-201, Line 70a.
- Form IT-203 filers: Enter the amount from Line 11 on Form IT-203, Line 60b.
Make sure the amount transferred matches the final calculation on Form IT-270.
Example Of Form IT-270 Credit Calculation
The following example demonstrates how the credit is calculated for a taxpayer filing as single with one dependent.
Assume the taxpayer has:
- Filing status: Single.
- Number of dependents: One.
- Federal adjusted gross income: $34,000.
- New York City income tax amount: $1,200.
- Refundable NYC child and dependent care credit: $100.
- NYC earned income credit: $200.
- Investment income: $5,000.
- No NYC or NYS PTET credit claimed.
The applicable income threshold for a single taxpayer with one dependent is $31,503.
The calculation is:
| Line | Description | Calculation | Amount |
|---|---|---|---|
| Line 1 | Federal adjusted gross income | Given amount | $34,000 |
| Line 2 | Applicable income threshold | Single, one dependent | $31,503 |
| Line 3 | Income above threshold | $34,000 − $31,503 | $2,497 |
| Line 4 | Remaining $5,000 allowance | $5,000 − $2,497 | $2,503 |
| Line 5 | Income-based percentage | $2,503 ÷ $5,000 | 0.5006 |
| Line 6 | NYC income tax | Given amount | $1,200 |
| Line 7 | NYC child and dependent care credit | Given amount | $100 |
| Line 8 | NYC earned income credit | Given amount | $200 |
| Line 9 | Total other credits | $100 + $200 | $300 |
| Line 10 | Remaining NYC tax | $1,200 − $300 | $900 |
| Line 11 | NYC Income Tax Elimination Credit | $900 × 0.5006 | $450.54 |
The taxpayer’s calculated New York City Income Tax Elimination Credit is $450.54.
The amount should be entered on Form IT-201, Line 70a.
Common Mistakes To Avoid When Completing Form IT-270
Review these common mistakes before submitting the form:
- Not claiming a dependent: You must claim at least one dependent on Form IT-201, Item H, or Form IT-203, Item I.
- Using the wrong taxpayer information: Your name and Social Security number must match your primary tax return.
- Ignoring the NYC residency requirement: The credit is intended for eligible full-year or part-year New York City residents.
- Using the wrong income threshold: The threshold depends on filing status and the number of dependents.
- Comparing income with the wrong threshold: Always use the applicable amount from the correct filing-status column.
- Exceeding the $5,000 income allowance: If federal adjusted gross income exceeds the threshold by more than $5,000, the taxpayer does not qualify.
- Incorrectly calculating investment income: Include the applicable taxable interest, tax-exempt interest, ordinary dividends, positive net capital gains, and other relevant investment income.
- Ignoring the $10,000 investment income limit: Investment income greater than $10,000 makes the taxpayer ineligible.
- Claiming a PTET credit: Claiming either the NYC or NYS PTET credit makes the taxpayer ineligible for this credit.
- Entering the wrong federal adjusted gross income: Use the correct amount from Form IT-201 or Form IT-203.
- Using an incorrect dependent count: The number of dependents must match the applicable New York State return.
- Incorrectly calculating Line 3: Subtract Line 2 from Line 1 only when Line 1 exceeds Line 2.
- Using the wrong percentage on Line 5: Divide Line 4 by $5,000 and round to four decimal places.
- Forgetting other credits: Include the applicable amounts from Forms IT-216, IT-215, or IT-209.
- Incorrectly calculating Line 10: Subtract the total on Line 9 from the amount on Line 6.
- Submitting the form when Line 10 is zero or negative: The instructions state that you must not complete or submit the form in this situation.
- Transferring the credit to the wrong line: Use Form IT-201, Line 70a, or Form IT-203, Line 60b.
- Submitting Form IT-270 separately: The form must accompany the applicable New York State income tax return.
Final Review Before Filing
Before submitting Form IT-270, use this checklist to verify that the eligibility questions and credit calculations are complete.
Taxpayer Information
- The taxpayer’s name matches Form IT-201 or Form IT-203.
- The Social Security number is correct.
- The applicable tax return has been identified.
- The taxpayer meets the New York City residency requirement.
Part 1: Eligibility
- Question A confirms that at least one dependent is claimed.
- Question B confirms that the applicable New York City income tax amount is not zero.
- Question C confirms that federal adjusted gross income does not exceed the applicable threshold by more than $5,000.
- Question D confirms that investment income is $10,000 or less.
- Question E confirms that neither NYC nor NYS PTET credit is being claimed.
- All five eligibility questions have been answered correctly.
Part 2: Credit Calculation
- Line 1 contains the correct federal adjusted gross income.
- Line 2 contains the correct income threshold for the filing status and number of dependents.
- Line 3 correctly calculates income above the threshold.
- Line 3 does not exceed $5,000.
- Line 4 correctly subtracts Line 3 from $5,000.
- Line 5 correctly divides Line 4 by $5,000 and uses four decimal places.
- Line 6 contains the correct New York City income tax amount.
- Line 7 contains the applicable refundable NYC child and dependent care credit.
- Line 8 contains the applicable NYC earned income credit.
- Line 9 correctly adds Lines 7 and 8.
- Line 10 correctly subtracts Line 9 from Line 6.
- Line 10 is greater than zero.
- Line 11 correctly multiplies Line 10 by Line 5.
Final Submission
- The final credit amount is entered on Form IT-201, Line 70a, or Form IT-203, Line 60b.
- All calculations have been reviewed.
- The completed Form IT-270 is included with the applicable New York State tax return.
- A copy of the completed form is retained for personal tax records.
Final Reminder: New York Form IT-270 allows eligible full-year and part-year New York City residents to claim the NYC Income Tax Elimination Credit. To qualify, taxpayers must claim at least one dependent, meet the applicable income requirements, have investment income of $10,000 or less, and not claim NYC or NYS PTET credits. Complete all five eligibility questions, calculate the income-based percentage, account for applicable credits, and transfer the final amount to the correct line of Form IT-201 or IT-203.