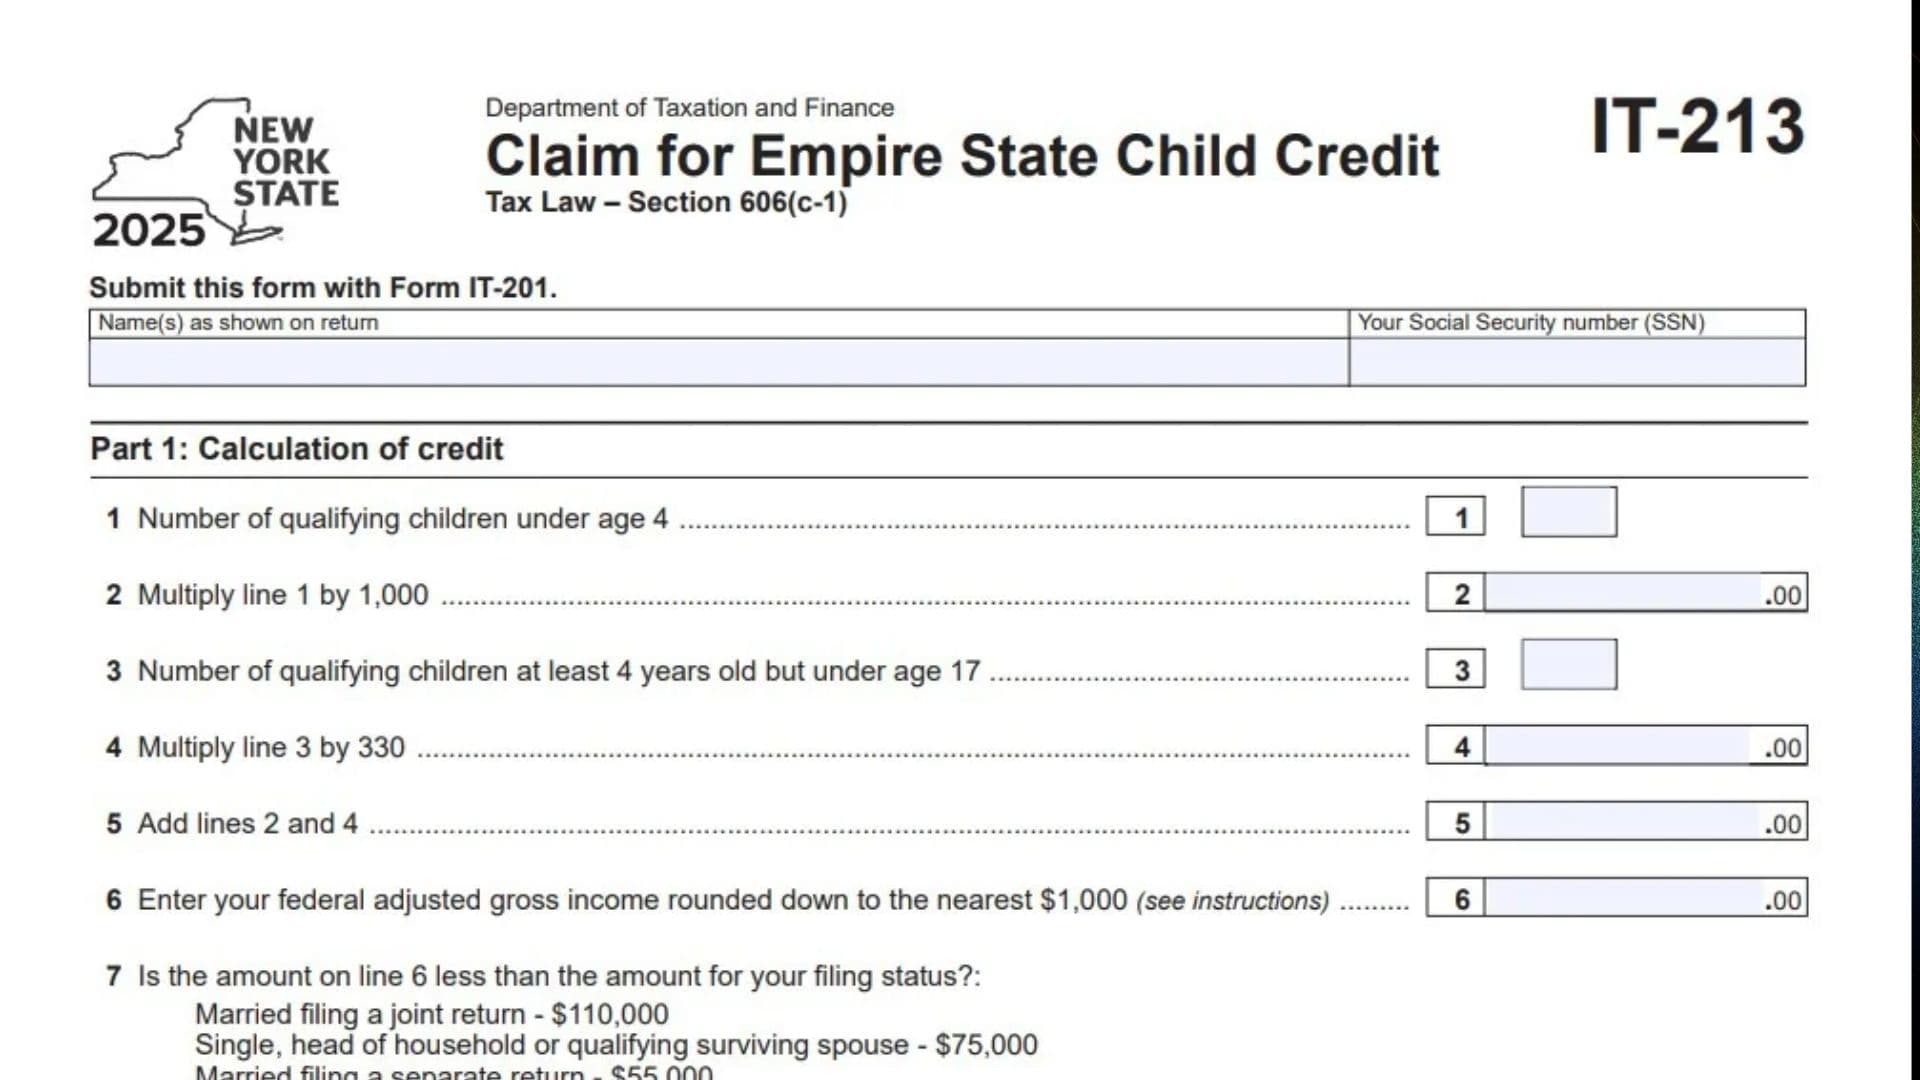
New York Form IT-213, officially known as the Claim for Empire State Child Credit, is a tax form issued by the New York State Department of Taxation and Finance. It allows eligible full-year New York State residents to claim a refundable tax credit for qualifying children. The credit is authorized under Section 606(c-1) of the New York Tax Law. For the 2025 tax year, the credit provides $1,000 for each qualifying child under four years old and $330 for each qualifying child who is at least four years old but younger than 17. The amount of credit a taxpayer can receive depends on the number and ages of qualifying children and the taxpayer’s federal adjusted gross income (FAGI) and filing status. The form collects the taxpayer’s name, Social Security number, number of qualifying children in each age category, adjusted gross income, and information about each child, including their name, Social Security number or Individual Taxpayer Identification Number (ITIN), and date of birth. It also calculates the credit reduction when income exceeds the applicable filing-status threshold. Form IT-213 contains two main parts. Part 1 calculates the Empire State Child Credit using the number of qualifying children, applicable credit amounts, and income-based reduction. Part 2 collects identifying information for every qualifying child included in the calculation. Taxpayers must submit Form IT-213 with their New York State resident income tax return, Form IT-201. Providing complete and accurate information is important because missing child identification details, incorrect dates of birth, or inaccurate income calculations may result in a delayed refund or denial of the credit. Unlike a credit that can only reduce tax liability, the Empire State Child Credit is refundable. If the eligible credit exceeds the tax liability, the taxpayer may request a refund or apply the overpayment toward the following year’s tax. The New York State Department of Taxation and Finance does not pay interest on the resulting refund or overpayment.
Who Qualifies For The Empire State Child Credit?
The Empire State Child Credit is generally available to full-year New York State residents who have at least one qualifying child under age 17 on December 31 of the tax year.
For the 2025 tax year, a qualifying child must meet the following requirements:
- Relationship: The child must be your child, sibling, stepsibling, or a descendant of any of these individuals. This includes stepchildren, eligible foster children, adopted children, and children placed with you for legal adoption.
- Residency: The child must have lived with you for more than half of the tax year.
- Age: The child must be younger than 17 on December 31, 2025.
- Financial support: The child must not have provided more than half of their own financial support.
- Joint return: The child must not have filed a joint tax return, except when filing only to claim a refund of withholding or estimated tax payments.
- Citizenship or identification: The child must be a U.S. citizen or national or have an individual taxpayer identification number issued by the IRS, as applicable.
You must also provide a valid SSN or ITIN for yourself and each child included in the claim.
Special Rules When More Than One Person Can Claim A Child
Sometimes two or more taxpayers may qualify to claim the same child.
The following rules determine who can claim the child:
- If two or more taxpayers can claim the same child, the child is generally considered the qualifying child of the parent. If neither parent claims the child, the taxpayer with the highest federal adjusted gross income may claim the child.
- If the parents do not file a joint return, the child generally qualifies for the parent with whom the child lived for the longest period during the year.
- If the child lived with both parents for an equal amount of time, the parent with the higher federal adjusted gross income who files a New York State return generally has priority.
- If neither parent claims the child, another eligible taxpayer may claim the child if that taxpayer’s federal adjusted gross income is higher than that of the parent with the highest federal adjusted gross income.
These rules help prevent multiple taxpayers from claiming the same qualifying child.
How To File Form IT-213
Form IT-213 must be submitted with Form IT-201, the New York State Resident Income Tax Return.
It is not intended to be filed as a standalone tax return.
Where To Submit Form IT-213
Attach the completed Form IT-213 to your New York State Form IT-201.
The form does not provide a separate mailing address. Follow the submission instructions for Form IT-201 based on your filing method.
When Should You File Form IT-213?
File Form IT-213 when you:
- Are eligible for the Empire State Child Credit.
- Have at least one qualifying child.
- Meet the applicable New York State residency requirements.
- Have calculated a positive credit amount.
- Are submitting your New York State resident income tax return.
If the calculated credit on Line 9 is zero or less, you are not eligible to claim the credit using this form. Do not complete or submit Form IT-213 in that situation.
Information To Prepare Before Completing Form IT-213
Gather the following information:
- Your complete name as shown on Form IT-201.
- Your Social Security number or applicable taxpayer identification information.
- Your filing status.
- Your federal adjusted gross income from Form IT-201, Line 19.
- The total number of qualifying children under age four.
- The total number of qualifying children aged four through sixteen.
- Each qualifying child’s full legal name.
- Each qualifying child’s SSN or ITIN.
- Each qualifying child’s date of birth.
- Any additional child information required on Form IT-213-ATT.
Having these details available will help you complete the form accurately.
How To Complete Form IT-213
Form IT-213 contains two main sections:
- Part 1: Calculation of credit.
- Part 2: Qualifying child information.
Complete the taxpayer identification fields first, followed by the credit calculation and child information.
Part 1: Calculation Of Credit
Part 1 contains nine lines used to calculate the Empire State Child Credit.
The calculation considers the number of qualifying children in each age group, the applicable credit amounts, and the reduction based on federal adjusted gross income.
Taxpayer Identification Information
Name(s) As Shown On Return
Enter your full name exactly as it appears on your New York State income tax return, Form IT-201.
If you are filing jointly, enter the names as they appear on the joint return.
Make sure the information matches your primary tax return to avoid identification problems.
Your Social Security Number (SSN)
Enter your Social Security number in the designated field.
Use the SSN associated with your New York State income tax return.
Verify the number before submitting the form.
Credit Calculation Lines
Line 1: Number Of Qualifying Children Under Age 4
Enter the total number of qualifying children who were younger than four years old on December 31 of the tax year.
Count only children who meet the qualifying child requirements.
For the 2025 tax year, include children who had not yet reached their fourth birthday by December 31, 2025.
Do not include children who were already four years old on that date. They belong in the next age category.
Line 2: Credit For Children Under Age 4
Multiply the number entered on Line 1 by $1,000.
The calculation is:
Line 1 × $1,000 = Line 2.
For example, if you have two qualifying children under age four, enter $2,000.
This amount represents the initial credit for qualifying children in this age group.
Line 3: Number Of Qualifying Children At Least Age 4 But Under Age 17
Enter the total number of qualifying children who were at least four years old but younger than 17 on December 31 of the tax year.
Include children who meet all the applicable qualifying child requirements.
Do not include children under four because they are already counted on Line 1.
Line 4: Credit For Children At Least Age 4 But Under Age 17
Multiply the number entered on Line 3 by $330.
The calculation is:
Line 3 × $330 = Line 4.
For example, if you have three qualifying children between four and sixteen years old, enter $990.
This amount represents the initial credit for children in this age category.
Line 5: Total Credit Before Income Reduction
Add the amounts from Lines 2 and 4.
The calculation is:
Line 2 + Line 4 = Line 5.
Enter the combined amount.
This represents your total Empire State Child Credit before applying the income-based reduction.
Line 6: Federal Adjusted Gross Income Rounded Down To The Nearest $1,000
Enter your federal adjusted gross income (FAGI) rounded down to the nearest $1,000.
Use the amount reported on Form IT-201, Line 19.
Do not round to the nearest thousand using ordinary rounding. Always reduce the amount to the lower $1,000.
For example:
- If your adjusted gross income is $35,999, enter $35,000.
- If your adjusted gross income is $75,850, enter $75,000.
- If your adjusted gross income is $110,999, enter $110,000.
If your adjusted gross income is zero or less, enter zero.
This amount is used to determine whether your income exceeds the applicable threshold for your filing status.
Line 7: Income Above The Applicable Filing Status Threshold
Compare the amount on Line 6 with the income threshold for your filing status.
The form provides three different thresholds:
- Married filing a joint return: $110,000.
- Single, head of household, or qualifying surviving spouse: $75,000.
- Married filing a separate return: $55,000.
Follow these instructions:
If the amount on Line 6 is less than the applicable threshold, enter zero on Line 7.
If the amount on Line 6 is equal to or greater than the applicable threshold, subtract the threshold from Line 6 and enter the result.
For example:
If you are filing as single and your amount on Line 6 is $85,000:
$85,000 − $75,000 = $10,000.
Enter $10,000 on Line 7.
If you are married filing jointly and Line 6 is $100,000, enter zero because your income is below the $110,000 threshold.
Line 8: Income-Based Credit Reduction
Multiply the amount on Line 7 by 1.65% (0.0165).
The calculation is:
Line 7 × 0.0165 = Line 8.
For example, if Line 7 is $10,000:
$10,000 × 0.0165 = $165.
Enter $165 on Line 8.
This amount represents the reduction applied to your initial credit because your adjusted gross income exceeds the applicable filing-status threshold.
Line 9: Empire State Child Credit
Subtract Line 8 from Line 5.
The calculation is:
Line 5 − Line 8 = Line 9.
Enter the resulting amount.
Line 9 represents your final Empire State Child Credit after applying the income-based reduction.
If the result is zero or less, you are not eligible to claim the credit. Do not complete or submit Form IT-213 with your tax return.
If the result is positive, transfer the amount to Form IT-201, Line 63.
Part 2: Enter Qualifying Child Information
Part 2 collects identifying information for every qualifying child included in the credit calculation.
You must provide information for each child counted on Lines 1 and 3.
The form provides six spaces for qualifying children.
Important: Failure to provide complete information for every qualifying child may result in the denial of the credit or delay the processing of your tax return.
Child Identification Fields
First Name
Enter the qualifying child’s first legal name.
Use the name associated with the child’s tax identification records.
MI (Middle Initial)
Enter the child’s middle initial, if applicable.
If the child does not have a middle name, follow the form’s applicable entry requirements.
Last Name
Enter the child’s complete legal last name.
Make sure the spelling matches the child’s identification records.
Suffix
Enter the applicable name suffix, if any.
Examples include:
- Jr.
- Sr.
- II
- III
Leave the field blank if the child does not have a suffix.
SSN Or ITIN
Enter the child’s Social Security number or Individual Taxpayer Identification Number.
Use the appropriate identification number assigned to the child.
Check every digit carefully. An incorrect or missing identification number may delay processing or affect eligibility for the credit.
Date Of Birth (MMDDYYYY)
Enter the child’s complete date of birth using the required month, day, and year format.
For example, if the child was born on March 15, 2022, enter:
03152022
The date of birth helps determine which credit category applies to the child.
Make sure the age category entered on Line 1 or Line 3 agrees with the child’s date of birth.
Additional Children: Form IT-213-ATT
The standard Form IT-213 provides space for six qualifying children.
If you have more than six qualifying children to report, use Form IT-213-ATT, Child Information for Empire State Child Credit Attachment to Form IT-213.
Enter the required information for the additional children on the attachment.
Submit Form IT-213-ATT together with Form IT-213 and Form IT-201.
Make sure every qualifying child included in the credit calculation is properly identified.
How To Transfer The Credit To Form IT-201
After completing Part 1 and Part 2, review the amount on Line 9.
Form IT-201, Line 63: Empire State Child Credit
Transfer the positive credit amount from Form IT-213, Line 9, to Form IT-201, Line 63.
Attach or submit Form IT-213 with Form IT-201.
If you are eligible for the credit but the amount exceeds your tax liability, you may request a refund or apply the overpayment toward the following year’s tax.
The Tax Department does not pay interest on the refund or overpayment.
Example Of Form IT-213 Credit Calculation
The following example demonstrates how the credit calculation works for the 2025 tax year.
Assume a taxpayer has:
- One qualifying child under age four.
- Two qualifying children between four and sixteen years old.
- Filing status: Single.
- Federal adjusted gross income: $85,750.
The calculation would be:
| Line | Calculation | Amount |
|---|---|---|
| Line 1 | One child under age 4 | 1 |
| Line 2 | 1 × $1,000 | $1,000 |
| Line 3 | Two children aged 4–16 | 2 |
| Line 4 | 2 × $330 | $660 |
| Line 5 | $1,000 + $660 | $1,660 |
| Line 6 | $85,750 rounded down | $85,000 |
| Line 7 | $85,000 − $75,000 | $10,000 |
| Line 8 | $10,000 × 0.0165 | $165 |
| Line 9 | $1,660 − $165 | $1,495 |
The taxpayer’s calculated Empire State Child Credit is $1,495.
This amount should be entered on Form IT-201, Line 63.
Common Mistakes To Avoid When Completing Form IT-213
Review these common mistakes before submitting your claim:
- Using the wrong tax year: Make sure you use the 2025 credit amounts when completing the 2025 form.
- Counting children in the wrong age category: Separate children under four from those aged four through sixteen.
- Including ineligible children: Verify that each child meets the qualifying child requirements.
- Entering an incorrect child identification number: Check every SSN or ITIN.
- Leaving out a child’s date of birth: Provide the complete date of birth for every qualifying child.
- Using the wrong adjusted gross income: Use the amount from Form IT-201, Line 19.
- Rounding income incorrectly: Always round down to the nearest $1,000.
- Using the wrong filing-status threshold: Apply the correct $110,000, $75,000, or $55,000 threshold.
- Incorrectly calculating Line 7: Enter zero when income is below the applicable threshold.
- Applying the wrong reduction rate: Use 1.65% (0.0165) on Line 8.
- Incorrectly calculating Line 9: Subtract Line 8 from Line 5.
- Forgetting additional child information: Use Form IT-213-ATT when more than six children must be reported.
- Failing to submit Form IT-213 with Form IT-201: The credit form must accompany the New York State resident income tax return.
- Reporting the credit on the wrong return line: Transfer the amount from Line 9 to Form IT-201, Line 63.
- Submitting the form when Line 9 is zero or negative: Do not submit the form if the calculated credit is zero or less.
Final Review Before Filing
Before submitting Form IT-213, use the following checklist to make sure all information and calculations are complete.
Taxpayer Identification
- The taxpayer’s name matches Form IT-201.
- The taxpayer’s Social Security number is correct.
- The correct 2025 tax year form is being used.
- The taxpayer meets the applicable New York State residency requirements.
- At least one qualifying child meets the eligibility requirements.
Part 1: Credit Calculation
- Line 1 contains the correct number of children under age four.
- Line 2 correctly multiplies Line 1 by $1,000.
- Line 3 contains the correct number of children aged four through sixteen.
- Line 4 correctly multiplies Line 3 by $330.
- Line 5 correctly adds Lines 2 and 4.
- Line 6 contains federal adjusted gross income from Form IT-201, Line 19.
- Line 6 is rounded down to the nearest $1,000.
- Line 7 uses the correct filing-status income threshold.
- Line 7 is zero when income is below the applicable threshold.
- Line 8 correctly multiplies Line 7 by 1.65%.
- Line 9 correctly subtracts Line 8 from Line 5.
- Line 9 is positive before submitting the form.
Part 2: Qualifying Child Information
- Every qualifying child included in Lines 1 and 3 is listed.
- Each child’s first name is entered correctly.
- Each applicable middle initial is provided.
- Each child’s last name is correct.
- Applicable suffixes are included.
- Every child’s SSN or ITIN is correct.
- Every child’s date of birth is entered in MMDDYYYY format.
- The age categories agree with the children’s dates of birth.
- Form IT-213-ATT is included if additional children must be reported.
Final Submission
- The amount from Line 9 is transferred to Form IT-201, Line 63.
- Form IT-213 is submitted with Form IT-201.
- All required child identification information is complete.
- All calculations have been reviewed.
- A copy of the completed form is retained for personal tax records.
Final Reminder: New York Form IT-213 is used to claim the refundable Empire State Child Credit for eligible full-year residents with qualifying children. For the 2025 tax year, the credit provides $1,000 per qualifying child under age four and $330 per qualifying child aged four through sixteen, subject to an income-based reduction. Complete both parts, verify every child’s identifying information, calculate the final credit on Line 9, and transfer the amount to Form IT-201, Line 63.