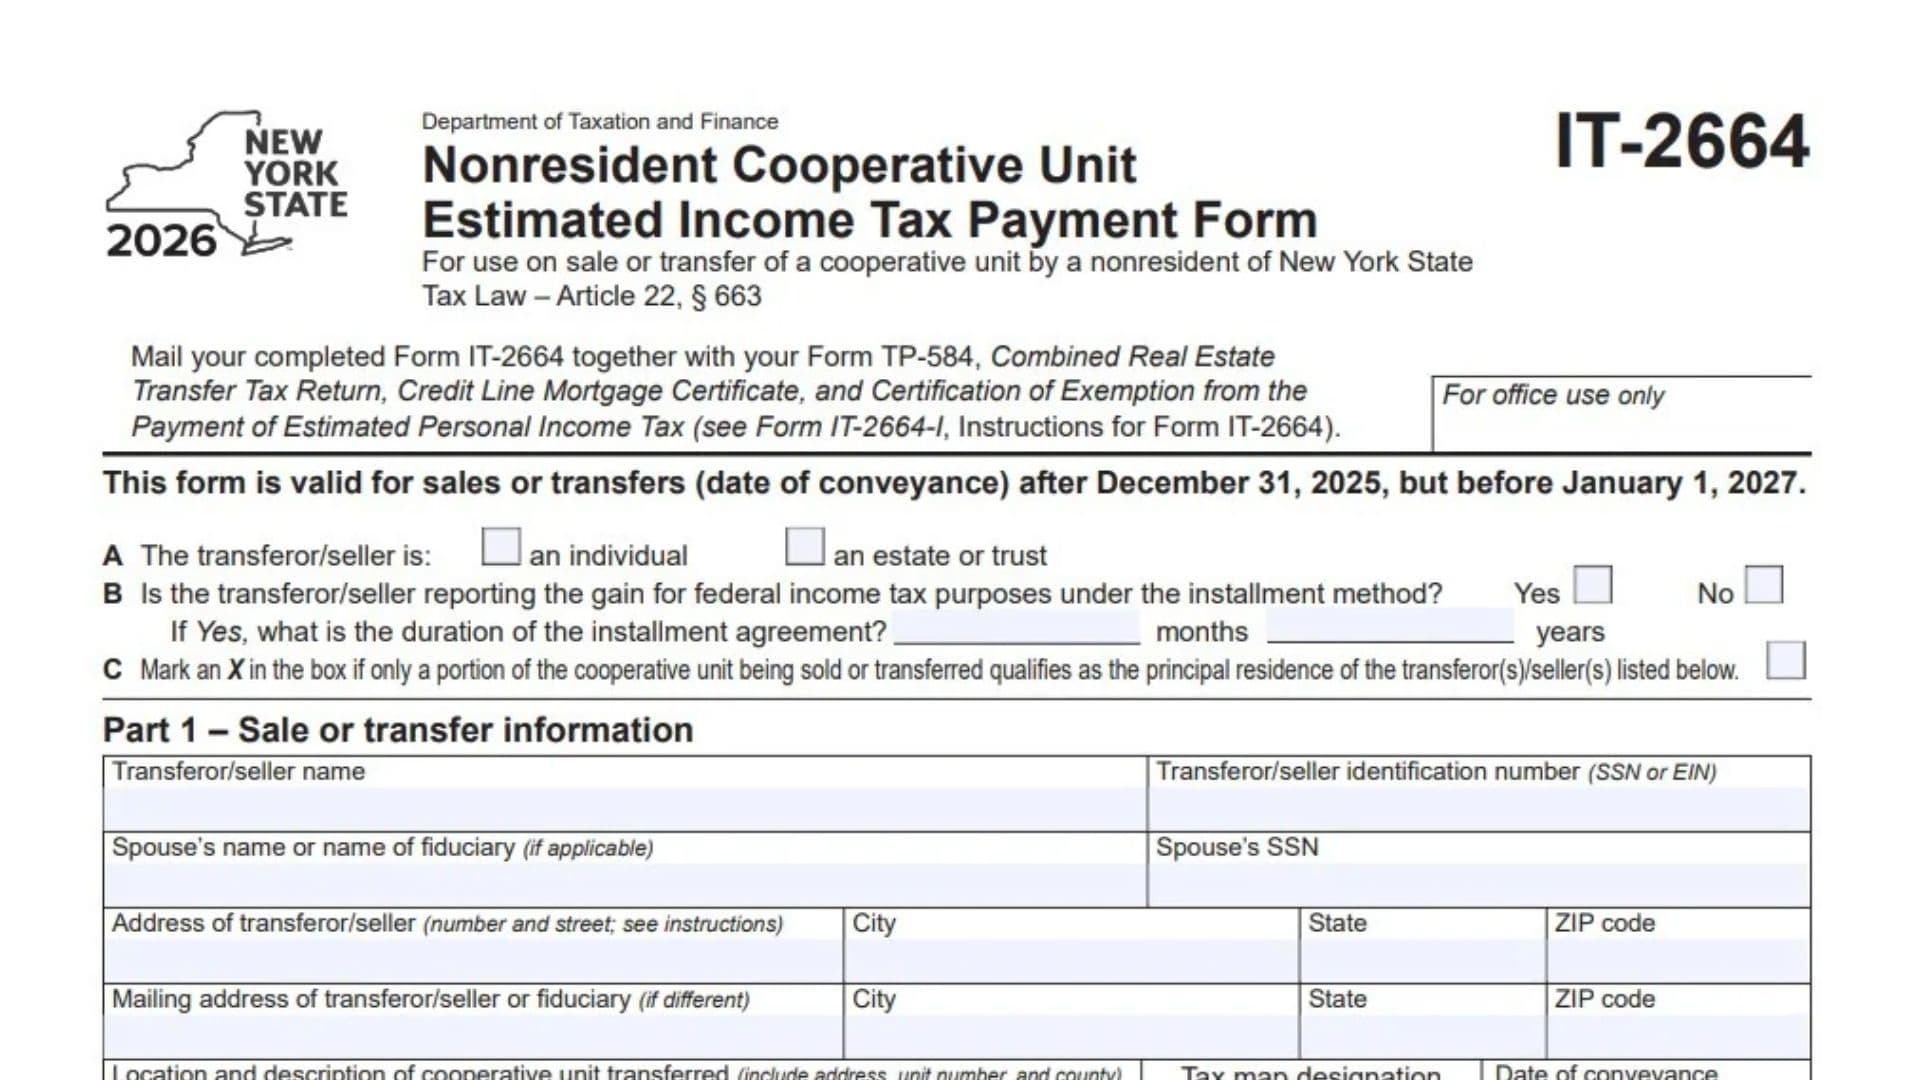
New York Form IT-2664, officially titled Nonresident Cooperative Unit Estimated Income Tax Payment Form, is a tax document issued by the New York State Department of Taxation and Finance. It is used when a nonresident of New York State sells or transfers an ownership interest in a cooperative housing unit. The form helps determine whether the seller must pay estimated New York State income tax on the gain from the transaction. It is designed to collect information about the seller, the cooperative unit, the purchase price, improvements, closing costs, selling expenses, adjusted basis, and the gain or loss resulting from the transfer. It also calculates the estimated income tax payment required under New York Tax Law Article 22, Section 663. Form IT-2664 contains four main parts, a worksheet, and a separate payment voucher. Part 1 collects the seller’s identification, residency-related transaction information, and details about the cooperative unit being transferred. Part 2 reports the sale price, total gain, and estimated tax due. Part 3 allows the seller to certify that estimated tax payment is not required under certain circumstances, such as when the transaction results in a loss or when the gain or loss does not have to be recognized under applicable provisions of the Internal Revenue Code, excluding Section 121. Part 4 contains the seller’s and spouse’s signatures. The worksheet on page 2 calculates the cost or adjusted basis of the cooperative unit, determines the gain or loss, and calculates the estimated tax using the applicable New York State tax rate. Page 3 contains Form IT-2664-V, the payment voucher used when submitting the estimated income tax payment. The form is valid for sales or transfers with a date of conveyance after December 31, 2025, but before January 1, 2027. It must be completed and submitted with Form TP-584, Combined Real Estate Transfer Tax Return, and the other applicable transaction documents. The completed paperwork must be mailed within 15 days after delivery of the instrument effecting the disposition. Completing Form IT-2664 accurately is important because the estimated tax calculation depends on the correct purchase price, adjustments to basis, selling expenses, gain allocation, and applicable tax rate. Sellers must also complete the payment voucher even when no estimated personal income tax payment is due.
Who Must Use Form IT-2664?
Form IT-2664 is intended for nonresidents of New York State who sell or transfer a cooperative unit.
The form is used to calculate the estimated New York State income tax payment associated with the gain from the transaction.
It also provides a way for eligible sellers to certify that estimated tax payment is not required under the circumstances described in Part 3.
Important Validity Period
The 2026 version of Form IT-2664 applies to transactions with a date of conveyance:
- After December 31, 2025.
- Before January 1, 2027.
Make sure the form version matches the date of the cooperative unit’s sale or transfer.
How To File Form IT-2664
Form IT-2664 must be submitted with the applicable real estate transfer documents.
The form instructions identify the following documents:
- Form IT-2664: Nonresident Cooperative Unit Estimated Income Tax Payment Form.
- Form TP-584: Combined Real Estate Transfer Tax Return.
- Credit Line Mortgage Certificate.
- Certification of Exemption from the Payment of Estimated Personal Income Tax, when applicable.
Information To Prepare Before Completing the Form
Gather the following information before starting:
- Seller’s full legal name.
- Seller’s Social Security number or Employer Identification Number (EIN).
- Spouse’s name and Social Security number, if applicable.
- Name of the estate or trust, if applicable.
- Name of the fiduciary, when applicable.
- Seller’s residential and mailing addresses.
- Cooperative unit address and unit number.
- County where the cooperative unit is located.
- Tax map designation, including section, block, and lot.
- Date of conveyance.
- Original purchase price of the cooperative stock shares.
- Cost of improvements.
- Eligible closing costs.
- Other adjustments that increase the property’s basis.
- Depreciation and other basis reductions.
- Sale price and selling expenses.
- Information about any installment sale arrangement.
- Information about the portion of the unit qualifying as the seller’s principal residence, if applicable.
- Information about other transferors or sellers, if applicable.
You should also prepare the relevant records needed to calculate the gain or loss using the same general method used for federal income tax purposes.
Where To Mail Form IT-2664
Mail the completed Form IT-2664 and the required transaction documents to:
NYS Tax Department
RETT Processing Unit
90 Cohoes Ave
Green Island, NY 12183-1515
The form instructions require submission within 15 days after delivery of the instrument effecting the disposition.
Payment Requirements
If estimated income tax is due, submit the full amount shown on Form IT-2664, Part 2, line 3.
Payment must be made by a separate check or money order in U.S. funds payable to NYS Income Tax.
Do not combine this payment with another tax or fee payment.
The real estate transfer tax shown on Form TP-584 must be paid separately using another check or money order.
How To Complete Form IT-2664
The form contains four main parts:
- Part 1: Sale or transfer information.
- Part 2: Estimated tax information.
- Part 3: Nonpayment of estimated tax by a nonresident.
- Part 4: Signature.
Before completing Part 2, you must calculate the gain or loss using the Worksheet for Part 2 on page 2.
Preliminary Questions
The first section contains three questions about the seller, the installment method, and the principal residence status of the cooperative unit.
Question A: Type of Transferor or Seller
Indicate whether the person or entity transferring the cooperative unit is:
- An individual.
- An estate or trust.
Mark an X in the appropriate box.
Select the classification that applies to the transferor or seller named in Part 1.
Question B: Installment Method
Indicate whether the transferor or seller is reporting the gain for federal income tax purposes under the installment method.
Select Yes if the gain will be reported using the installment method.
Select No if the installment method does not apply.
If you select Yes, enter the duration of the installment agreement in the spaces provided.
You can report the duration in:
- Months.
- Years.
Enter the applicable number and identify the correct time unit.
Question C: Partial Principal Residence
Mark an X in this checkbox only if a portion of the cooperative unit being sold or transferred qualifies as the principal residence of the transferor or sellers identified on the form.
If the entire unit does not qualify as the seller’s principal residence, identify the applicable situation by marking this box.
This information is important when determining how much of the gain is subject to the estimated tax calculation.
Part 1: Sale or Transfer Information
Part 1 collects the identifying information of the seller and details about the cooperative unit being transferred.
Complete every applicable field.
Transferor/Seller Name
Enter the full legal name of the person or entity transferring the cooperative unit.
Use the name associated with the applicable Social Security number or EIN.
Transferor/Seller Identification Number
Enter the seller’s identifying number.
Depending on the seller’s classification, this will be:
- Social Security Number (SSN) for an individual.
- Employer Identification Number (EIN) for an estate or trust.
Check the number carefully before proceeding.
Spouse’s Name or Name of Fiduciary
If applicable, enter the spouse’s full name.
For an estate or trust, enter the name of the fiduciary responsible for the transaction.
Leave this field blank if it does not apply.
Spouse’s SSN
Enter the spouse’s Social Security number when applicable.
Make sure the number is correct and matches the spouse’s identifying information.
Address of Transferor/Seller
Enter the seller’s complete residential or principal address.
Provide:
- Street number and street name.
- City.
- State.
- ZIP Code.
Use the address applicable to the seller’s information.
Mailing Address of Transferor/Seller or Fiduciary
Complete this field if the mailing address is different from the address entered above.
Enter the complete mailing address, including:
- Street number and street name.
- City.
- State.
- ZIP Code.
If the mailing address is the same as the address already provided, follow the form instructions for this field.
Location and Description of Cooperative Unit Transferred
Enter the complete location and description of the cooperative unit being sold or transferred.
Include:
- Property street address.
- Cooperative unit or apartment number.
- County.
Make sure the information identifies the specific cooperative unit involved in the transaction.
Tax Map Designation: Section, Block, and Lot
Enter the tax map designation associated with the cooperative unit.
The form provides three separate spaces:
- Section.
- Block.
- Lot.
Use the applicable property tax map records to obtain the correct designation.
Date of Conveyance
Enter the date the cooperative unit is conveyed or transferred.
The form provides a date field for 2026.
Use the actual date of conveyance rather than the date the agreement was initially signed, unless both dates are the same.
Part 2: Estimated Tax Information
Part 2 summarizes the sale price, total gain, and estimated income tax due.
Before completing this section, finish the Worksheet for Part 2 on page 2.
Transfer the calculated amounts from the corresponding worksheet lines.
Line 1: Sale Price
Enter the sale price less selling expenses from Worksheet for Part 2, line 15.
This amount represents the net sale proceeds used in calculating the gain or loss.
Transfer the exact amount from line 15 of the worksheet.
Line 2: Total Gain
Enter the total gain calculated on Worksheet for Part 2, line 17.
If the transaction results in a loss or the gain is zero, enter zero instead.
Do not enter a negative amount on this line.
Line 3: Estimated Tax Due
Enter the estimated tax due calculated on Worksheet for Part 2, line 20.
This amount represents the estimated New York State income tax payment resulting from the transaction.
If no estimated tax is due, enter zero as applicable.
You must still complete Form IT-2664-V on page 3, even when the estimated payment is zero.
Part 3: Nonpayment of Estimated Tax by a Nonresident Upon the Sale or Transfer of a Cooperative Unit
Part 3 allows the seller to certify that estimated tax payment is not required under one of the specific circumstances listed on the form.
It contains one certification question with two possible reasons.
Review both options carefully before selecting the applicable checkbox.
Line 4: Certification of Nonpayment of Estimated Tax
The seller certifies that they are a nonresident of New York State and are not required to pay estimated tax under Tax Law Section 663 because one of the following conditions applies.
Option A: Sale or Transfer Results in a Loss
Mark this checkbox if the sale or transfer of the cooperative unit results in a loss or zero gain for federal income tax purposes.
The form defines this condition as a result that is less than or equal to zero.
You must complete the Worksheet for Part 2 on page 2 to calculate the transaction’s gain or loss.
Use the worksheet calculation to establish that the sale resulted in a loss or no gain.
Option B: No Gain or Loss Recognition Under the Internal Revenue Code
Mark this checkbox if the seller is not required to recognize any gain or loss from the sale or transfer under provisions of the Internal Revenue Code, except Section 121.
This option applies when a specific Internal Revenue Code provision allows the transaction to take place without recognizing the gain or loss for federal income tax purposes.
You must complete the summary section below the checkbox.
Brief Summary of the Transfer
Provide a short but clear explanation supporting the nonrecognition of gain or loss.
Include:
- The applicable Internal Revenue Code section or sections.
- The relevant facts of the transaction.
- An explanation of why the gain or loss does not have to be recognized.
Make sure the explanation clearly supports the reason for selecting Option B.
Do not leave this section incomplete when relying on the nonrecognition provision.
Part 4: Signature
Part 4 contains the certification and signature fields.
By signing, the transferor or seller confirms that the information provided on the form, including certifications and attachments, is true, correct, and complete to the best of their knowledge and belief.
Signature of Transferor/Seller
The transferor or seller must sign the form.
For an estate or trust, the appropriate fiduciary should provide the signature.
Date
Enter the date the transferor or seller signs the form.
Signature of Spouse
If applicable, the spouse must sign in the designated space.
Spouse’s Date
Enter the date the spouse signs the form.
Make sure all required signatures and dates are included before submission.
Worksheet for Part 2: Calculating Gain or Loss
The Worksheet for Part 2 appears on page 2.
It is used to calculate the gain or loss on the sale or transfer of the cooperative unit.
The calculation follows the same general method used for federal income tax purposes.
The form refers taxpayers to the following IRS publications for additional information:
- Publication 523, Selling Your Home.
- Publication 544, Sales and Other Dispositions of Assets.
- Publication 551, Basis of Assets.
The worksheet contains three main calculation stages:
- Computation of cost or other basis.
- Calculation of gain or loss.
- Calculation of estimated tax due.
Computation of Cost or Other Basis
This section determines the adjusted basis of the cooperative stock shares.
Line 5: Purchase Price of Stock Shares
Enter the original purchase price of the stock shares associated with the cooperative unit.
The purchase price generally represents the cost of the stock in the cooperative housing corporation.
It may also include the seller’s properly allocable share of a mortgage on the cooperative building, provided that amount was required as a condition of retaining the stock interest.
Calculate the purchase price using the same general method used for federal income tax purposes.
Line 6: Improvements
Enter the cost of qualifying improvements made to the cooperative unit.
These amounts increase the property’s basis.
Use the applicable improvement costs when determining the adjusted basis.
Line 7: Closing Costs
Enter the applicable closing costs associated with the purchase of the cooperative unit.
Include the costs that qualify as basis adjustments under the applicable federal income tax rules.
Line 8: Other Basis Increases
Enter any other applicable amounts that increase the basis of the cooperative stock shares.
Provide a brief explanation in the space provided.
Line 9: Total Basis Increases
Add the amounts reported on lines 6, 7, and 8.
The calculation is:
Line 6 + Line 7 + Line 8 = Line 9
Enter the total basis increases.
Line 10: Total Cost or Other Basis Before Decreases
Add the original purchase price on line 5 to the basis increases on line 9.
The calculation is:
Line 5 + Line 9 = Line 10
This amount represents the cost or other basis before accounting for applicable reductions.
Decreases to Basis
The next section identifies amounts that reduce the cooperative unit’s basis.
Line 11: Depreciation
Enter any applicable depreciation associated with the cooperative unit.
Use the depreciation amount determined under the applicable federal income tax rules.
If depreciation does not apply, enter zero where required.
Line 12: Other Basis Reductions
Enter any other applicable amounts that reduce the basis of the cooperative stock shares.
Provide an explanation in the space provided.
Line 13: Total Basis Decreases
Add the amounts reported on lines 11 and 12.
The calculation is:
Line 11 + Line 12 = Line 13
Enter the combined amount.
Line 14: Adjusted Basis of Stock Shares
Subtract line 13 from line 10.
The calculation is:
Line 10 − Line 13 = Line 14
Enter the resulting adjusted basis.
This amount is used to determine the gain or loss from the sale or transfer.
Gain or Loss
This section compares the net sale proceeds with the adjusted basis.
Line 15: Sale Price Less Selling Expenses
Enter the sale price after subtracting applicable selling expenses.
The calculation is:
Sale Price − Selling Expenses = Line 15
Enter the resulting amount.
You must also transfer this amount to Part 2, line 1, on the front page.
Line 16: Cost or Adjusted Basis
Enter the adjusted basis calculated on line 14.
Transfer the amount directly from line 14.
Line 17: Total Gain or Loss
Subtract line 16 from line 15.
The calculation is:
Line 15 − Line 16 = Line 17
If the result is greater than zero, enter the gain on line 17 and transfer it to Part 2, line 2, on the front page. Then continue to line 18.
If the result is less than or equal to zero, enter zero on line 20 and on Part 2, line 2, on the front page.
When the transaction results in a loss or zero gain, complete Part 2, Part 3, and Form IT-2664-V on page 3 as directed.
Estimated Tax Due
This section calculates the estimated New York State income tax associated with the gain.
Line 18: Gain Subject to Estimated Tax
Enter the gain from line 17 that will be reported on your 2026 federal income tax return.
If only part of the gain is subject to tax, enter the applicable portion rather than automatically using the entire amount.
The form provides additional rules for installment sales, partial principal residences, multiple transferors, and estates or trusts.
Special Situation: Partial Principal Residence
If only a portion of the cooperative unit qualifies as your principal residence, enter the gain allocated to the portion that does not qualify as your principal residence and that will be reported on your 2026 federal income tax return.
Attach a statement to Form IT-2664 explaining how you calculated the allocation.
Special Situation: Multiple Transferors or Sellers
If two or more people sell or transfer the cooperative unit, allocate the total gain among the sellers in the same manner used for federal income tax purposes.
Attach a statement showing:
- Each transferor’s or seller’s name.
- Social Security number or EIN.
- Address.
- Share of the gain.
Special Situation: Installment Sale
If the gain is being reported under the installment method, enter the amount of gain that you and your spouse, if applicable, will report on your 2026 federal income tax return.
Do not automatically enter the entire gain from the transaction if only a portion will be reported during 2026.
Special Situation: Estate or Trust
A nonresident estate or trust must enter the amount of gain from line 17 without regard to distributions.
Line 19: New York State Tax Rate
The applicable New York State tax rate for 2026 is 10.90%.
The form provides the rate in decimal format:
0.1090
Use the rate shown on the worksheet.
Line 20: Estimated Tax Due
Multiply the gain entered on line 18 by the tax rate on line 19.
The calculation is:
Line 18 × 0.1090 = Line 20
Round the result to the nearest whole dollar.
Enter the calculated amount on line 20 and transfer it to Part 2, line 3, on the front page.
You must also complete Form IT-2664-V on page 3, even if no estimated personal income tax payment is due.
Form IT-2664-V: Nonresident Cooperative Unit Estimated Income Tax Payment Voucher
Form IT-2664-V appears at the bottom of page 3.
It is the payment voucher used when submitting the estimated personal income tax associated with the cooperative unit transfer.
The form instructions specifically require you to complete this voucher even if there is no estimated income tax payment due.
How To Complete the Payment Voucher
Date of Fiscal Year End
Enter the applicable fiscal year-end date in the designated field.
Use the date that applies to the estate or trust, when relevant.
Date of Conveyance
Enter the date the cooperative unit was conveyed or transferred.
This date should match the date reported on the main Form IT-2664.
Identification Number (SSN or EIN)
Enter the taxpayer’s identifying number.
Use the Social Security number for an individual or the EIN for an estate or trust.
Individual or Estate/Trust Checkbox
Mark an X in the appropriate box:
- Individual.
- Estate/trust.
Select the same taxpayer classification used on the main form.
Individual Taxpayer’s Full Name or Name of Estate or Trust
Enter the individual’s full legal name or the full name of the estate or trust.
Use the name that corresponds to the identification number entered above.
Spouse’s Name or Name and Title of Fiduciary
Enter the spouse’s name when applicable.
For an estate or trust, enter the fiduciary’s name and title.
Spouse’s SSN
Enter the spouse’s Social Security number when applicable.
Individual Taxpayer’s Street Address or Address of Fiduciary or Representative
Enter the complete street address associated with the taxpayer, fiduciary, or representative.
Include the street number and street name.
City, Village, or Post Office
Enter the applicable city, village, or post office.
State
Enter the state abbreviation associated with the mailing address.
ZIP Code
Enter the correct ZIP Code.
Total Payment
Enter the total estimated income tax payment shown on Form IT-2664, Part 2, line 3.
Use the same amount reported on the main form.
If no estimated personal income tax is due, follow the voucher instructions and complete the voucher accordingly.
Payment Instructions
If payment is required, attach a separate check or money order to Form IT-2664-V.
Follow these requirements:
- Make the payment in U.S. funds.
- Make the check or money order payable to NYS Income Tax.
- Pay the full amount shown on Form IT-2664, line 3.
- Do not reduce the payment for prior tax credits or estimated tax payments for the tax year.
- Do not combine the payment with any other tax or fee.
- Print your name on the payment.
- Print the last four digits of your SSN or EIN on the payment.
- Write 2026 IT-2664-V on the payment.
Do not detach the payment voucher from the rest of the form.
Mailing and Private Delivery Service Instructions
The completed Form IT-2664, payment voucher, applicable payment, and Form TP-584 must be submitted according to the mailing instructions.
Submission Deadline
Mail the completed documents within 15 days after delivery of the instrument effecting the disposition.
Make sure the paperwork and any required payments are prepared before the deadline.
Using a Private Delivery Service
You may use a private delivery service instead of the U.S. Postal Service.
However, the date recorded by a private delivery service cannot automatically be used to establish the filing or payment date.
To establish the date, the delivery service must be designated by the U.S. Secretary of the Treasury or the Commissioner of Taxation and Finance.
The current list of designated private delivery services is provided in New York Publication 55, Designated Private Delivery Services.
If you use an approved designated service and need proof of the delivery date, contact the delivery service for instructions on obtaining written confirmation.
Important Filing and Calculation Considerations
Calculate the Gain Using Federal Income Tax Methods
The worksheet calculates gain or loss using the same general method used for federal income tax purposes.
Review the purchase price, basis adjustments, depreciation, selling expenses, and other applicable amounts carefully.
Do not enter an estimated sale price or adjusted basis without supporting transaction records.
Principal Residence Treatment Can Affect the Taxable Gain
If only a portion of the cooperative unit qualifies as the seller’s principal residence, the gain attributable to the remaining portion may need to be reported separately.
Use the allocation instructions for line 18 and attach a statement explaining the calculation.
Multiple Sellers Must Allocate the Gain
When multiple people transfer or sell the cooperative unit, the total gain must be allocated in the same manner used for federal income tax purposes.
The required supporting statement must identify each seller and their share of the gain.
Complete the Payment Voucher Even When No Tax Is Due
The form explicitly requires completion of Form IT-2664-V even when there is no estimated personal income tax payment due.
Do not assume that a zero tax calculation eliminates the voucher requirement.
Keep Transaction Records
Retain records supporting the purchase price, improvements, closing costs, depreciation, selling expenses, and gain allocation.
These documents help substantiate the calculations reported on the form.
Final Review Before Filing
Before submitting New York Form IT-2664, review the following checklist to ensure that all information, calculations, certifications, and payment details are complete.
Preliminary Questions
- Identify whether the transferor or seller is an individual or an estate/trust.
- Answer the installment method question.
- Enter the installment agreement duration when applicable.
- Mark the partial principal residence checkbox when applicable.
Part 1: Sale or Transfer Information
- Enter the transferor’s or seller’s full name.
- Enter the correct SSN or EIN.
- Provide the spouse’s name or fiduciary’s name when applicable.
- Enter the spouse’s Social Security number when applicable.
- Complete the seller’s residential address.
- Enter the mailing address if different.
- Provide the cooperative unit’s complete address.
- Include the unit number and county.
- Enter the tax map section, block, and lot.
- Enter the correct date of conveyance.
Part 2: Estimated Tax Information
- Complete the Worksheet for Part 2 before filling in this section.
- Transfer the sale price from worksheet line 15 to line 1.
- Transfer the total gain from worksheet line 17 to line 2.
- Enter zero on line 2 if the transaction results in a loss or zero gain.
- Transfer the estimated tax due from worksheet line 20 to line 3.
Part 3: Nonpayment Certification
- Determine whether the transaction resulted in a loss or zero gain.
- If applicable, mark Option A.
- If relying on nonrecognition under the Internal Revenue Code, mark Option B.
- Include the applicable IRC section or sections.
- Explain the relevant facts supporting the nonrecognition claim.
Part 4: Signature
- Obtain the transferor’s or seller’s signature.
- Enter the signature date.
- Obtain the spouse’s signature when applicable.
- Enter the spouse’s signature date.
Worksheet for Part 2
- Enter the purchase price of stock shares on line 5.
- Enter improvements on line 6.
- Enter closing costs on line 7.
- Explain other basis increases on line 8.
- Add lines 6 through 8 on line 9.
- Add lines 5 and 9 on line 10.
- Enter depreciation on line 11 when applicable.
- Explain other basis reductions on line 12.
- Add lines 11 and 12 on line 13.
- Calculate adjusted basis on line 14.
- Enter the sale price less selling expenses on line 15.
- Transfer the adjusted basis to line 16.
- Calculate the gain or loss on line 17.
- Enter the applicable gain on line 18.
- Use the 10.90% tax rate on line 19.
- Calculate estimated tax due on line 20.
- Round the estimated tax to the nearest whole dollar.
- Attach supporting gain allocation statements when applicable.
Form IT-2664-V: Payment Voucher
- Enter the applicable fiscal year-end date.
- Enter the date of conveyance.
- Enter the correct SSN or EIN.
- Mark the Individual or Estate/Trust checkbox.
- Enter the taxpayer’s or estate’s name.
- Provide the spouse’s name or fiduciary information when applicable.
- Enter the spouse’s SSN when applicable.
- Complete the street address.
- Enter the city, state, and ZIP Code.
- Enter the total payment from Form IT-2664, line 3.
- Complete the voucher even when no payment is due.
Final Submission Requirements
- Include Form IT-2664.
- Include Form TP-584.
- Include the Credit Line Mortgage Certificate.
- Include the applicable Certification of Exemption from Payment of Estimated Personal Income Tax.
- Attach a separate check or money order for the estimated income tax when payment is due.
- Make the payment payable to NYS Income Tax.
- Keep the real estate transfer tax payment separate.
- Do not detach Form IT-2664-V.
- Mail the completed documents within 15 days after delivery of the instrument effecting the disposition.
- Use the correct NYS Tax Department mailing address.
- Keep copies of the completed forms, payment records, and supporting documents.
Correctly completing New York Form IT-2664 helps nonresident sellers calculate and report estimated income tax associated with the sale or transfer of a cooperative unit. Carefully review the purchase price, adjusted basis, selling expenses, applicable gain allocation, and estimated tax calculation. Complete all four parts, the worksheet, and the payment voucher before submitting the required documents to the New York State Department of Taxation and Finance.