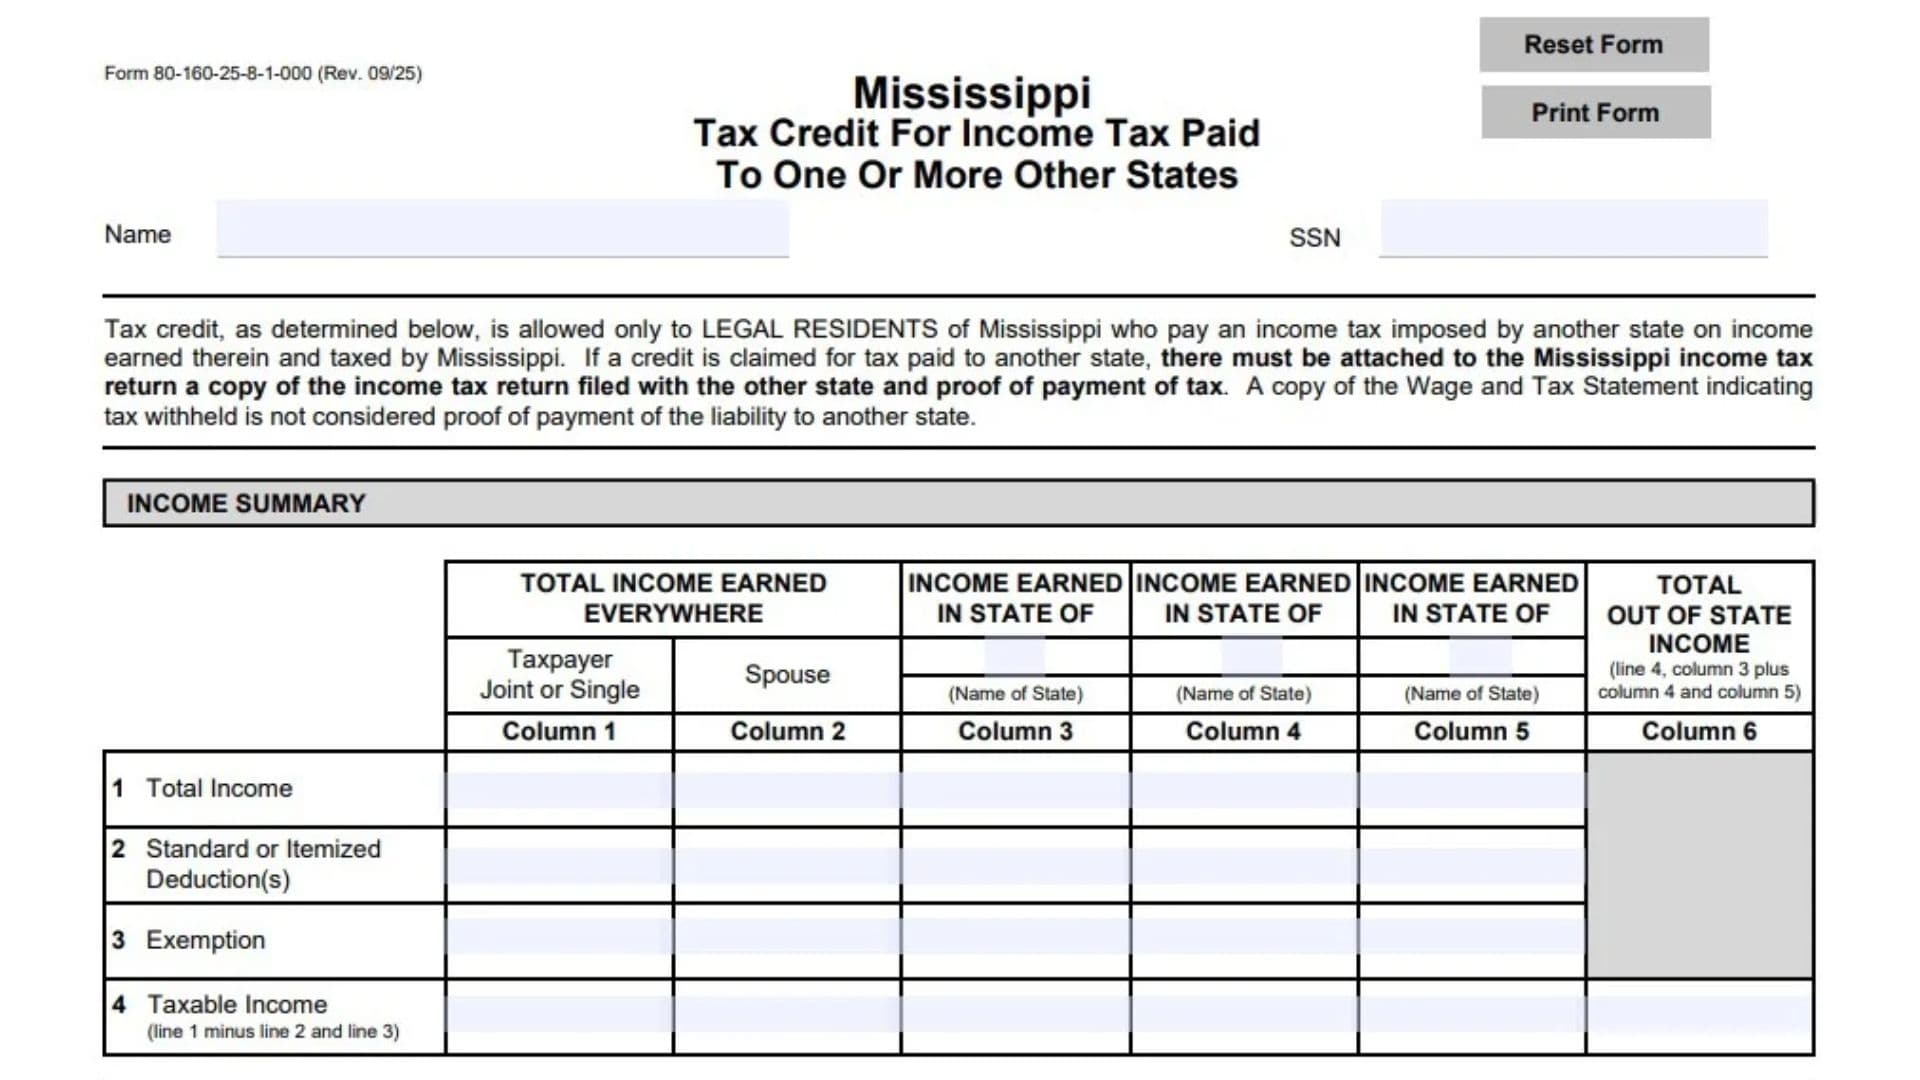
Mississippi Form 80-160, officially titled Tax Credit for Income Tax Paid to One or More Other States, is a tax form used by legal residents of Mississippi who earn income in another state and pay income tax to that state on income that is also taxed by Mississippi. The form allows eligible taxpayers to claim a credit against their Mississippi income tax liability for qualifying income taxes paid to one or more other states. Its purpose is to help prevent the same income from being subjected to income tax by both Mississippi and another state without allowing the taxpayer to receive a credit greater than the applicable tax limitations. Form 80-160 collects information about the taxpayer’s total income, spouse’s income when filing jointly, income earned in other states, deductions, exemptions, and taxable income. It also calculates the percentage of out-of-state taxable income attributable to each state and determines the maximum credit available under Mississippi tax rates. The calculation considers the actual income tax due to other states, the Mississippi tax attributable to the out-of-state income, and the taxpayer’s total Mississippi income tax liability. Only legal residents of Mississippi who satisfy the applicable requirements can claim this credit. Taxpayers must also file an income tax return with each other state where the qualifying income was earned and attach copies of those returns and proof that the tax was paid. Wage and Tax Statements showing withholding are not sufficient proof of payment. Completing Form 80-160 correctly is important because Mississippi limits the credit to the lowest applicable amount under its tax credit rules. The final allowable credit is transferred to the appropriate line of the taxpayer’s Mississippi income tax return, Form 80-105 or Form 81-110, depending on the return being filed.
Who Qualifies for Form 80-160?
Form 80-160 is intended for individuals who meet the following requirements:
- You must be a legal resident of Mississippi.
- You must have earned income in one or more other states.
- The income earned in those states must also be subject to Mississippi income tax.
- You must have paid income tax imposed by the other state or states on that income.
- You must file an income tax return with each other state for which you are claiming the credit.
- You must provide copies of the other states’ income tax returns and proof of tax payment with your Mississippi return.
Simply having income tax withheld from your wages in another state does not automatically qualify you for the credit.
Important Credit Limitations
Mississippi Code Section 27-7-77 establishes three limitations on the credit.
First Limitation: Mississippi Income Tax Liability
The credit cannot exceed the amount of income tax owed to Mississippi, as reported on line 17 of the applicable Mississippi return.
Second Limitation: Actual Tax Paid to Another State
The credit cannot exceed the actual income tax paid to the other state.
Income tax withholding shown on a W-2 is not sufficient proof that the tax liability was paid.
Third Limitation: Mississippi Tax Rate Calculation
The credit cannot exceed the amount calculated by applying the highest applicable Mississippi income tax rates to the net taxable income reported to the other state.
The form uses a calculation based on the applicable Mississippi rates to establish this limitation.
All three limitations must be considered when determining the final allowable credit.
How To File Form 80-160
Form 80-160 must be attached to your Mississippi income tax return when claiming a credit for income taxes paid to another state.
The form identifies two Mississippi returns to which the calculated credit may be transferred:
- Form 80-105: Enter the allowable credit on page 1, line 18.
- Form 81-110: Enter the allowable credit on page 1, line 3.
Use the return that applies to your filing situation.
Required Supporting Documents
Before submitting Form 80-160, prepare the following documents:
- Your completed Mississippi income tax return.
- A completed Form 80-160.
- A copy of the income tax return filed with each other state.
- Proof of payment of the income tax owed to each other state.
- Income records showing the amounts earned in each state.
- Documentation supporting the deductions and exemptions claimed on the respective state returns.
Important: A Wage and Tax Statement showing state income tax withholding is not considered proof that the tax liability was paid to another state. You must provide appropriate proof of payment.
Preparing the Form
The form is divided into two major sections:
- Income Summary: Calculates total income, deductions, exemptions, and taxable income for the taxpayer, spouse, and each other state.
- Computation of Tax Credit: Determines the credit attributable to each state and calculates the final allowable credit against Mississippi income tax.
Complete the income summary first because its figures are used throughout the credit calculation.
How To Complete Form 80-160
Taxpayer Identification Information
Name
Enter your name as it appears on your Mississippi income tax return.
If filing jointly, use the taxpayer information associated with the joint return.
SSN
Enter your Social Security number in the designated field.
Verify that the number matches your Mississippi income tax return.
Income Summary
The Income Summary section contains six columns. Columns 1 and 2 identify income belonging to the taxpayer and spouse, while columns 3, 4, and 5 identify income earned in individual states outside Mississippi. Column 6 calculates the total out-of-state taxable income.
If you earned income in more than three other states, the displayed columns may not provide enough space to identify every state. Follow the applicable filing instructions for additional state information.
Column 1: Taxpayer
Enter the taxpayer’s income information for the applicable lines.
This column represents the taxpayer’s income earned everywhere, together with the corresponding deductions, exemptions, and taxable income.
Column 2: Spouse
Enter the spouse’s corresponding income information when filing jointly.
Use the spouse’s income, deductions, exemptions, and taxable income as reported for the applicable returns.
Column 3: Income Earned in State 1
Enter the income and related tax information associated with the first other state.
Write the name of that state above the column.
Column 4: Income Earned in State 2
Enter the income and related tax information associated with the second other state.
Identify the state by writing its name above the column.
Column 5: Income Earned in State 3
Enter the income and related tax information associated with the third other state.
Write the corresponding state name above the column.
Column 6: Total Out-of-State Income
This column is used to calculate the combined taxable income earned in the other states.
For line 4, add the amounts from columns 3, 4, and 5.
Do not enter separate taxpayer or spouse amounts in this total column.
Income Summary Lines
Line 1: Total Income
Enter the total income earned everywhere in column 1 for the taxpayer.
If filing jointly, enter the spouse’s total income in column 2.
Enter the income earned in each other state separately in columns 3, 4, and 5.
Write the corresponding state names above these columns.
Use the income information from your Mississippi and other state income tax returns to complete this line.
Line 2: Standard or Itemized Deductions
Enter the standard or itemized deductions claimed on your Mississippi income tax return in column 1 and column 2, if applicable.
For columns 3, 4, and 5, enter the standard or itemized deductions claimed on the corresponding other state income tax returns.
Make sure the deductions reported for each state match the applicable tax return.
Line 3: Exemption
Enter the exemption amount claimed on your Mississippi income tax return in column 1 and column 2, if applicable.
Enter the exemption amounts claimed on the other state income tax returns in columns 3, 4, and 5.
Allocate deductions and exemptions between the taxpayer and spouse in the same manner used on the respective state income tax returns.
Line 4: Taxable Income
Calculate taxable income by subtracting the deductions and exemptions reported on lines 2 and 3 from the total income reported on line 1.
The calculation is:
Line 1 − Line 2 − Line 3 = Line 4
Complete this calculation separately for columns 1 through 5.
For column 6, add the taxable income amounts reported in columns 3, 4, and 5.
The calculation is:
Column 3 + Column 4 + Column 5 = Column 6
Column 6 represents the total taxable income earned outside Mississippi and is used in the subsequent tax credit calculations.
Computation of Tax Credit
This section determines how much of the Mississippi income tax credit can be attributed to income earned in each other state.
It uses the taxable income calculated in the Income Summary section, the applicable Mississippi tax rate, and the actual tax paid to the other states.
Line 5: Income Allocation Ratio
Line 5: Ratio
Calculate the ratio for each other state by dividing the taxable income reported in that state’s column on line 4 by the total out-of-state taxable income reported in column 6.
The calculations are:
- Column 3 ratio = Line 4, Column 3 ÷ Line 4, Column 6.
- Column 4 ratio = Line 4, Column 4 ÷ Line 4, Column 6.
- Column 5 ratio = Line 4, Column 5 ÷ Line 4, Column 6.
Enter each result as a percentage in its corresponding column.
These percentages represent the proportion of total out-of-state taxable income earned in each state.
The ratios are used to allocate the Mississippi tax calculation among the different states.
Lines 6 and 7: Mississippi Tax Rate Calculation
These lines calculate the Mississippi tax attributable to the total taxable income earned outside the state.
The calculation uses two income brackets:
- The first $10,000 of taxable income, or any portion of it.
- The remaining taxable income above $10,000.
Line 6: First $10,000 or Part
Enter the first $10,000 of taxable income, or the applicable smaller amount, from line 4, column 6, in column A.
The form applies a 0% rate to this amount.
Multiply column A by 0% and enter the result in column B.
The result is zero.
Enter zero in columns 3, 4, and 5 as well.
For example, if your total out-of-state taxable income is $8,000, enter $8,000 in column A and zero as the calculated tax amount.
If your total out-of-state taxable income is $10,000 or more, enter $10,000 in column A.
Line 7: Remaining Balance
Enter the remaining taxable income above $10,000 from line 4, column 6, in column A.
This represents the portion of out-of-state taxable income exceeding the first $10,000.
Multiply this amount by 4.4% to calculate the total income tax in column B.
The calculation is:
Remaining Taxable Income × 4.4% = Column B
Next, allocate the calculated tax among the other states.
Multiply the amount in column B by each percentage reported on line 5.
The calculations are:
- Column 3 = Line 7, Column B × Line 5, Column 3.
- Column 4 = Line 7, Column B × Line 5, Column 4.
- Column 5 = Line 7, Column B × Line 5, Column 5.
Enter the resulting amounts in the corresponding state columns.
These amounts represent the Mississippi tax attributable to the taxable income earned in each other state under the calculation provided by the form.
Line 8: Tax Credit Computed
Add the amounts reported on lines 6 and 7 in columns 3, 4, and 5.
The calculation is:
Line 6 + Line 7 = Line 8
Enter the resulting credit amount separately for each state.
Because line 6 uses a 0% rate, the calculated amount generally comes from the state-specific allocations on line 7.
This line establishes the maximum credit attributable to each other state under the Mississippi tax rate calculation.
Lines 9 and 10: Actual Tax Paid and Allowable State Credit
Line 9: Income Tax Due to Other States
Enter the income tax due to each other state using the corresponding other state income tax return.
Use columns 3, 4, and 5 to report the applicable amounts for each state.
You must attach copies of the other state income tax returns.
You must also provide proof of payment of the tax liability.
Do not use the amount of income tax withheld from your W-2 as a substitute for proof of payment.
Line 10: Allowable Credit by State
For each state, compare the amounts reported on line 8 and line 9.
Enter the smaller amount in the corresponding state column.
The calculation is:
Smaller of Line 8 or Line 9 = Line 10
Complete the calculation separately for columns 3, 4, and 5.
In column 6, add the amounts from columns 3, 4, and 5.
The calculation is:
Column 3 + Column 4 + Column 5 = Column 6
This total represents the credit available under the state-specific tax calculations before applying the final Mississippi income tax limitation.
Lines 11 and 12: Final Mississippi Tax Credit
Line 11: Mississippi Income Tax Due
Enter the amount of Mississippi income tax due from the applicable Mississippi income tax return.
The form identifies two possible sources:
- Form 80-105, page 1, line 17.
- Form 81-110, page 1, line 2.
Use the amount from the return that applies to your filing situation.
Line 12: Allowable Tax Credit for Tax Paid to Other States
Determine the final allowable credit by comparing line 10, column 6, with line 11.
Enter the smaller amount.
The calculation is:
Smaller of Line 10, Column 6 or Line 11 = Line 12
This is the final credit that can be claimed for income taxes paid to other states.
Transfer the amount reported on line 12 to the appropriate Mississippi income tax return:
- Form 80-105: Enter the credit on page 1, line 18.
- Form 81-110: Enter the credit on page 1, line 3.
Do not claim more than the amount calculated on line 12.
Understanding the Tax Credit Calculation
The credit calculation involves three separate limitations.
First, Mississippi determines the tax attributable to the income earned in other states using the taxable income allocation ratios and the applicable Mississippi rates.
Second, the credit for each state cannot exceed the actual income tax paid to that state.
Third, the combined credit cannot exceed the Mississippi income tax liability reported on the applicable return.
For example, if the calculated credit under line 10 is greater than the Mississippi income tax due on line 11, the allowable credit is limited to the amount on line 11.
Similarly, if the actual income tax paid to another state is lower than the calculated Mississippi tax attributable to that income, the credit for that state is limited to the actual tax amount.
These comparisons ensure that the credit does not exceed the limitations established under Mississippi law.
Important Filing Requirements
Attach Copies of Other State Income Tax Returns
You must attach a copy of each other state’s income tax return for which you are claiming a credit.
The return should support the income and tax amounts entered on Form 80-160.
Provide Proof of Tax Payment
A W-2 or other Wage and Tax Statement showing state income tax withholding is not sufficient proof that the tax liability was paid.
Provide appropriate payment documentation to establish that the tax was actually paid to the other state.
Use the Correct Mississippi Income Tax Return
The final credit from line 12 must be transferred to the correct Mississippi return.
Use Form 80-105, page 1, line 18, or Form 81-110, page 1, line 3, as applicable.
Form Presentation Requirements
The form specifically states that duplex printing and photocopies are not acceptable.
Follow this requirement when preparing the form for submission.
Final Review Before Filing
Before submitting Form 80-160 with your Mississippi income tax return, review the following checklist to ensure that every calculation and supporting document is complete.
Taxpayer Information
- Enter your correct name.
- Verify your Social Security number.
- Confirm that you are a legal resident of Mississippi.
- Confirm that the income earned in other states is also taxed by Mississippi.
Income Summary
- Enter the taxpayer’s total income earned everywhere in column 1.
- Enter the spouse’s total income in column 2, if filing jointly.
- Identify each other state above columns 3, 4, and 5.
- Report income earned in each other state separately.
- Enter the applicable standard or itemized deductions on line 2.
- Enter the applicable exemptions on line 3.
- Allocate deductions and exemptions between the taxpayer and spouse consistently with the respective state returns.
- Calculate taxable income on line 4.
- Add columns 3, 4, and 5 to calculate total out-of-state taxable income in column 6.
Computation of Tax Credit
- Calculate the income allocation ratios on line 5.
- Enter the first $10,000 or applicable portion of taxable income on line 6.
- Apply the 0% rate on line 6.
- Calculate the remaining taxable income on line 7.
- Apply the 4.4% rate to the remaining balance.
- Allocate the calculated tax among the other states using the line 5 ratios.
- Calculate the tax credit on line 8.
- Enter the income tax due to each other state on line 9.
- Enter the smaller amount from lines 8 and 9 for each state on line 10.
- Calculate the total credit in column 6 of line 10.
- Enter the applicable Mississippi income tax due on line 11.
- Calculate the final allowable credit on line 12.
- Transfer the credit to the correct line of Form 80-105 or Form 81-110.
Supporting Documents And Submission
- Attach a copy of each other state’s income tax return.
- Attach proof of actual tax payment to each other state.
- Do not rely only on W-2 withholding statements as proof of payment.
- Verify that all income and deduction amounts match the applicable state returns.
- Check the calculations and percentages for accuracy.
- Confirm that the credit does not exceed any of the three applicable limitations.
- Attach Form 80-160 to the Mississippi income tax return.
- Follow the form’s requirement regarding duplex printing and photocopies.
Correctly completing Mississippi Form 80-160 helps eligible residents claim the appropriate credit for income taxes paid to other states. Carefully report your income, deductions, exemptions, and actual tax payments, apply all three credit limitations, and attach the required supporting documents before submitting your Mississippi income tax return.