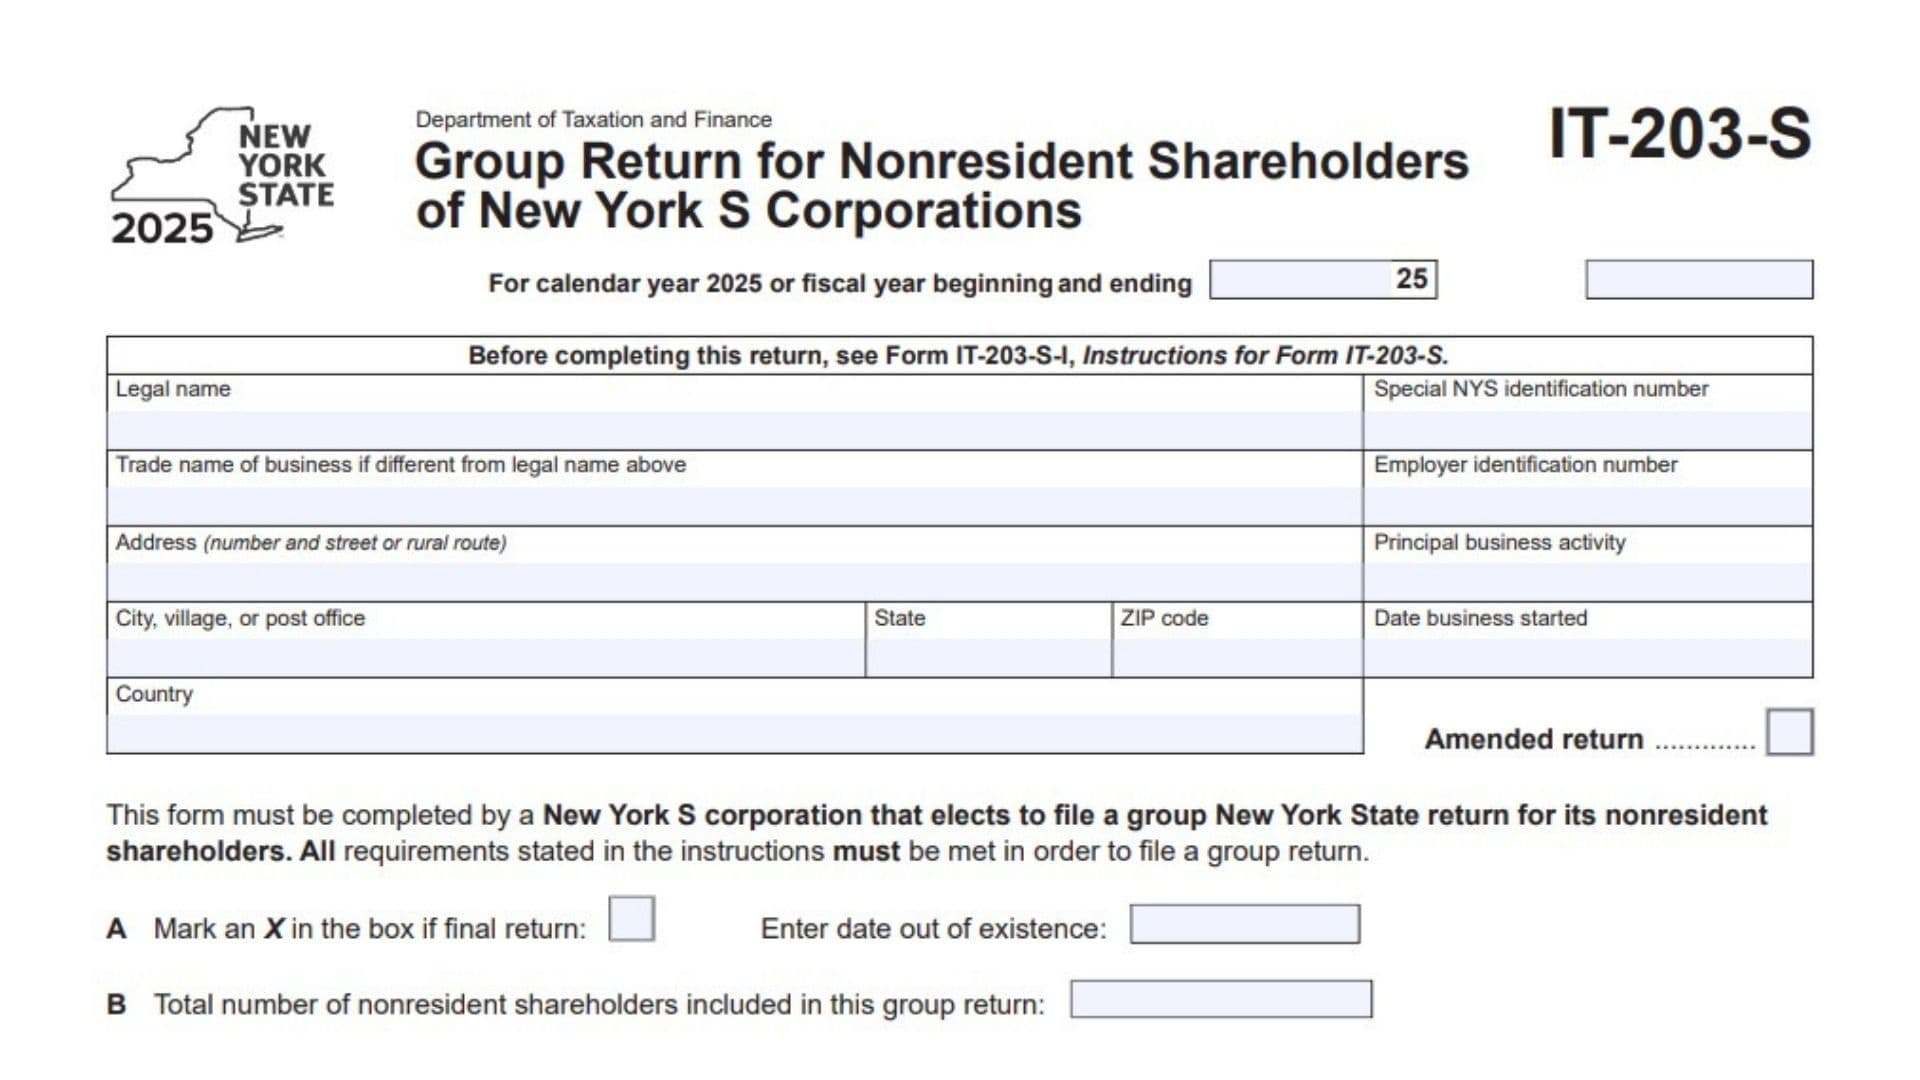
New York Form IT-203-S, officially titled Group Return for Nonresident Shareholders of New York S Corporations, is a tax form used by eligible New York S corporations that elect to file a group New York State income tax return on behalf of their nonresident shareholders. Instead of requiring each eligible nonresident shareholder to report the relevant income separately through an individual New York return, the S corporation can use this group filing arrangement when all applicable requirements are satisfied.
The form is administered by the New York State Department of Taxation and Finance. Its primary purpose is to report the combined New York taxable income attributable to the nonresident shareholders included in the group return, calculate the corresponding New York State tax, account for estimated income tax payments and extension payments, and determine whether the group has an outstanding balance or an overpayment.
Form IT-203-S collects information about the S corporation, including its legal name, trade name, special New York State identification number, Employer Identification Number (EIN), business address, principal business activity, and business commencement date. It also identifies the number of nonresident shareholders included in the group filing and provides a checkbox for indicating whether the return is final or amended.
An important feature of this form is that it relies on Form IT-203-S-ATT, which contains the individual shareholder-level calculations and supporting information. The corporation must complete the attachment before entering amounts on lines 1 through 5 of Form IT-203-S. The attachment provides the underlying information used to calculate group taxable income, tax, payments, balance due, and overpayment.
Form IT-203-S is relevant specifically to New York S corporations electing to file a group return for their nonresident shareholders. The corporation must satisfy all requirements explained in the applicable instructions before using this filing method. Merely having nonresident shareholders does not automatically establish eligibility to file a group return.
Completing the form correctly is important because the totals reported on its main lines must agree with the corresponding column totals on Form IT-203-S-ATT. Any differences in taxable income, tax calculations, payments, or shareholder allocations can result in an incorrect group tax liability. The corporation must also ensure that the return is properly completed and signed by the group agent and that the paid preparer information is provided when applicable.
How To File Form IT-203-S
New York Form IT-203-S is submitted to the New York State Department of Taxation and Finance as a group income tax return for nonresident shareholders of an eligible New York S corporation.
The form specifically requires the corporation to complete and submit Form IT-203-S-ATT with the group return.
Forms To Prepare Before Filing
The following documents and information should be available before completing Form IT-203-S:
- The corporation’s legal name and trade name.
- Special New York State identification number.
- Federal Employer Identification Number (EIN).
- Principal business activity.
- Complete business mailing address.
- Date the business started.
- Applicable calendar or fiscal tax year.
- Number of nonresident shareholders included in the group return.
- Completed Form IT-203-S-ATT.
- New York State taxable income calculations for each included shareholder.
- New York State tax calculations.
- Estimated income tax payment records.
- Extension payment information, including payments made with Form IT-370.
- Paid preparer’s identification and registration information, where applicable.
- Group agent’s name, title, contact information, and signature.
Important Filing Considerations
Form IT-203-S-ATT Must Be Completed First
The form explicitly instructs taxpayers to complete Form IT-203-S-ATT before entering information on lines 1 through 5 of the main group return.
The attachment provides the shareholder-level calculations that determine the totals transferred to the main form.
Submit The Attachment With The Group Return
Form IT-203-S-ATT must accompany Form IT-203-S. The corporation should ensure that the attachment is complete and that all corresponding totals agree with the main return.
Calendar-Year And Fiscal-Year Filers
The form accommodates calendar-year 2025 filers and corporations using a fiscal tax year beginning and ending during the applicable reporting period.
Fiscal-year corporations must enter their actual beginning and ending dates.
Amended Returns
If the corporation is correcting a previously submitted group return, it should select the Amended Return checkbox and follow the applicable amended-return instructions.
Final Returns
If the corporation is filing its final group return, it must identify the return as final and provide the date the business ceased to exist, where applicable.
The form itself refers taxpayers to Form IT-203-S-I, Instructions for Form IT-203-S, for additional filing requirements and guidance.
How To Complete New York Form IT-203-S
Form IT-203-S contains corporation identification fields, filing status information, shareholder count information, five numbered tax calculation lines, and separate signature sections for the paid preparer and group agent.
The most important requirement is to complete Form IT-203-S-ATT first because the amounts reported on the main return are transferred from the attachment.
Tax Year And Corporation Identification
Tax Year
Enter the applicable calendar or fiscal tax year.
For calendar-year filers, the form identifies 2025 as the reporting year.
For fiscal-year filers, enter the beginning and ending dates of the corporation’s fiscal tax period in the spaces provided.
Legal Name
Enter the corporation’s complete legal name as registered with the relevant tax authorities.
Use the legal name associated with the New York S corporation filing the group return.
Special NYS Identification Number
Enter the special New York State identification number assigned to the corporation for the group return filing.
Use the identification number associated with the corporation’s New York group filing account.
Trade Name Of Business If Different From Legal Name Above
If the corporation operates under a business or trade name that differs from its legal name, enter that trade name here.
If the corporation does not use a separate trade name, follow the applicable form instructions.
Employer Identification Number
Enter the corporation’s federal Employer Identification Number (EIN).
Verify that the number corresponds to the corporation identified in the legal name section.
Address (Number And Street Or Rural Route)
Enter the corporation’s complete business mailing address, including the street number, street name, or rural route information.
Principal Business Activity
Describe the corporation’s primary business activity.
The description should identify the main type of business conducted by the S corporation.
City, Village, Or Post Office
Enter the city, village, or post office associated with the corporation’s business address.
State
Enter the state abbreviation corresponding to the business address.
ZIP Code
Provide the ZIP code for the corporation’s business address.
Date Business Started
Enter the date the corporation began conducting business.
Use the actual commencement date supported by the corporation’s records.
Country
Enter the country associated with the corporation’s business address.
Amended Return
Select this checkbox if the corporation is filing an amended Form IT-203-S to correct or revise a previously submitted group return.
Review the applicable amended-return instructions before making corrections to previously reported income, tax, or payment amounts.
Group Return Information
This section establishes the corporation’s filing status and identifies the nonresident shareholders included in the group return.
The form uses two lettered entries, A and B.
Section A: Final Return
Mark an X in the checkbox if the corporation is filing its final group return.
A final return generally indicates that the corporation will not continue filing this particular group return after the applicable reporting period.
Date Out Of Existence
If the return is marked as final, enter the date the corporation ceased to exist.
Use the applicable date supported by the corporation’s official business records.
Section B: Total Number Of Nonresident Shareholders Included In This Group Return
Enter the total number of nonresident shareholders included in the group filing.
Count the shareholders included in the group return and report the total in the designated field.
This figure should agree with the shareholder information provided in the accompanying Form IT-203-S-ATT.
Form IT-203-S-ATT: Required Supporting Attachment
Before completing lines 1 through 5 of Form IT-203-S, the corporation must complete Form IT-203-S-ATT.
This attachment provides the detailed calculations for the nonresident shareholders included in the group return.
The main return relies on the totals calculated in specific columns of the attachment.
The form identifies the following transfers:
- Column H total: New York State taxable income.
- Column I total: New York State tax.
- Column J total: Estimated income tax paid and amount paid with Form IT-370.
- Column K total: Balance due.
- Column L total: Overpayment.
The corporation must ensure that the corresponding amounts on the attachment agree with the entries made on the main group return.
How To Complete Lines 1 Through 5
Lines 1 through 5 summarize the group’s taxable income, tax liability, payments, outstanding balance, and overpayment.
These calculations should only be completed after Form IT-203-S-ATT has been prepared.
New York State Taxable Income
Line 1: New York State Taxable Income
Enter the total New York State taxable income from Form IT-203-S-ATT, column H.
This amount represents the combined taxable income reported for the nonresident shareholders included in the group return.
Before entering the amount, verify that all applicable shareholder calculations have been completed in the attachment.
The amount reported on line 1 must agree with the total of column H on Form IT-203-S-ATT.
New York State Income Tax
Line 2: New York State Tax
Enter the total New York State tax calculated on Form IT-203-S-ATT, column I.
This amount represents the combined New York State tax liability associated with the nonresident shareholders included in the group return.
The figure should agree exactly with the total reported in column I of the attachment.
Estimated Tax Payments And Extension Payments
Line 3: New York State Estimated Income Tax Paid/Amount Paid With Form IT-370
Enter the total New York State estimated income tax payments and applicable amounts paid with Form IT-370.
Transfer the amount from Form IT-203-S-ATT, column J.
This line accounts for payments already made toward the group’s New York State income tax liability.
Check the payment records and ensure that the amount agrees with the attachment.
Balance Due
Line 4: Balance Due
Line 4 determines whether the group owes additional New York State income tax after accounting for payments already made.
If line 2 is greater than line 3, subtract line 3 from line 2.
The calculation is:
\[ \text{Line 4}=\text{Line 2}-\text{Line 3} \]
For example, if the group’s New York State tax is $12,000 and its applicable payments total $9,000, the remaining balance is $3,000.
The amount reported on line 4 must agree with the total in column K of Form IT-203-S-ATT.
Payment Instructions For Balance Due
The form provides specific payment instructions:
- Do not send cash.
- Make the payment by check or money order.
- The payment must be in U.S. funds.
- Make the check or money order payable to NY State Income Tax.
- Write the corporation’s special New York State identification number on the payment.
- Include the designation 2025 IT-203-S on the payment.
These details help identify the payment with the correct group return.
Overpayment
Line 5: Overpayment
Line 5 calculates the amount by which the group’s payments exceed its New York State tax liability.
If line 3 is greater than line 2, subtract line 2 from line 3.
The calculation is:
\[ \text{Line 5}=\text{Line 3}-\text{Line 2} \]
For example, if the group’s total tax is $8,000 and its payments total $10,000, the overpayment is $2,000.
The amount reported on line 5 must agree with the total in column L of Form IT-203-S-ATT.
Application Of Overpayment To 2026 Estimated Income Tax
The form states that the overpaid amount will be applied to the corporation’s 2026 estimated income tax.
Therefore, the amount reported on line 5 represents an overpayment allocated toward the following tax year’s estimated tax liability.
Paid Preparer Information
The paid preparer section must be completed by the tax professional responsible for preparing the group return, where applicable.
It collects the preparer’s signature, professional identification details, business information, and contact information.
Preparer’s Signature
The paid preparer must sign the return in the designated field.
The signature identifies the professional responsible for preparing the return.
Date
Enter the date associated with the preparer’s signature.
Firm’s Name (Or Yours, If Self-Employed)
Enter the name of the tax preparation firm.
If the preparer is self-employed and does not operate under a separate firm name, enter the preparer’s own name as appropriate.
Preparer’s NYTPRIN
Enter the New York Tax Preparer Registration Identification Number (NYTPRIN), when applicable.
Use the registration number associated with the paid preparer.
Preparer’s PTIN Or SSN
Enter the preparer’s federal Preparer Tax Identification Number (PTIN) or Social Security Number (SSN), as applicable.
Address
Enter the preparer’s complete business address.
Include the street address and other required address details.
Employer Identification Number
Enter the Employer Identification Number of the tax preparation firm, where applicable.
NYTPRIN Exclusion Code
Complete the NYTPRIN exclusion code field when the applicable preparer registration rules require it.
Enter the paid preparer’s email address for tax-related communication.
Group Agent Information And Signature
The group agent section must be completed and signed by the individual designated to act as the group agent for the New York S corporation group return.
This section identifies the person responsible for the group filing and provides the necessary signature and contact details.
Print Name Of Group Agent
Enter the full name of the designated group agent.
The name should be clearly printed in the appropriate field.
Title Of Group Agent
Enter the group agent’s official title or position within the corporation or organization.
Signature Of Group Agent
The designated group agent must sign the return.
This signature confirms the group agent’s responsibility for the submitted group return.
Date
Enter the date the group agent signs the return.
Daytime Phone Number
Provide a telephone number where the group agent can be contacted during normal business hours.
Include the appropriate area code.
Enter the group agent’s email address for correspondence regarding the group return.
Final Review Before Filing
Before submitting New York Form IT-203-S, review the corporation’s identification details, shareholder information, tax calculations, payments, and required signatures.
Use the following checklist to verify that the return is complete.
Corporation Information
- Confirm the correct 2025 calendar or fiscal tax year.
- Verify the corporation’s legal name.
- Check the special New York State identification number.
- Confirm the trade name, if applicable.
- Verify the federal EIN.
- Check the business address.
- Confirm the principal business activity.
- Verify the date the business started.
- Enter the correct country.
- Select the Amended Return checkbox if applicable.
Group Return Information
- Confirm whether the return is final.
- Enter the date out of existence when applicable.
- Verify the total number of nonresident shareholders included in the group return.
- Confirm that the corporation satisfies the applicable group filing requirements.
Form IT-203-S-ATT
- Complete Form IT-203-S-ATT before entering lines 1 through 5.
- Verify the taxable income total in column H.
- Confirm the New York State tax total in column I.
- Check estimated tax and extension payments in column J.
- Verify the balance due in column K.
- Confirm the overpayment in column L.
- Ensure the completed attachment accompanies the main return.
Main Tax Calculations
- Confirm line 1 agrees with column H total.
- Verify line 2 agrees with column I total.
- Check line 3 against column J total.
- Recalculate the balance due on line 4, where applicable.
- Verify line 4 agrees with column K total.
- Recalculate the overpayment on line 5, where applicable.
- Verify line 5 agrees with column L total.
- Confirm that any overpayment is correctly applied toward 2026 estimated income tax.
Paid Preparer Information
- Obtain the preparer’s signature, where applicable.
- Enter the preparer’s signature date.
- Verify the firm name.
- Confirm the NYTPRIN.
- Enter the PTIN or SSN, as applicable.
- Complete the preparer’s address.
- Verify the firm’s EIN, where applicable.
- Complete the NYTPRIN exclusion code if required.
- Provide the preparer’s email address.
Group Agent Information
- Enter the group agent’s printed name.
- Provide the group agent’s title.
- Obtain the group agent’s signature.
- Enter the signature date.
- Verify the daytime telephone number.
- Provide the group agent’s email address.
Final Filing Checks
- Ensure all applicable sections have been completed.
- Reconcile all amounts with Form IT-203-S-ATT.
- Confirm the number of shareholders agrees with the supporting attachment.
- Verify that all tax payments are accurately reported.
- Check the payment instructions if a balance is due.
- Confirm that the required attachment is submitted with the group return.
- Retain copies of the completed return and supporting records.
Important Filing Reminder
New York Form IT-203-S is specifically designed for New York S corporations electing to file a group New York State income tax return for their nonresident shareholders. The corporation must satisfy the applicable requirements explained in Form IT-203-S-I before filing under this arrangement.
The most important preparation requirement is completing Form IT-203-S-ATT before entering the main return’s tax calculation lines. The totals reported on lines 1 through 5 must agree with the corresponding column totals on the attachment.
Accurate shareholder reporting, correct tax calculations, proper payment reconciliation, and a completed group agent signature section are essential for preparing a complete New York Form IT-203-S for the 2025 tax year.