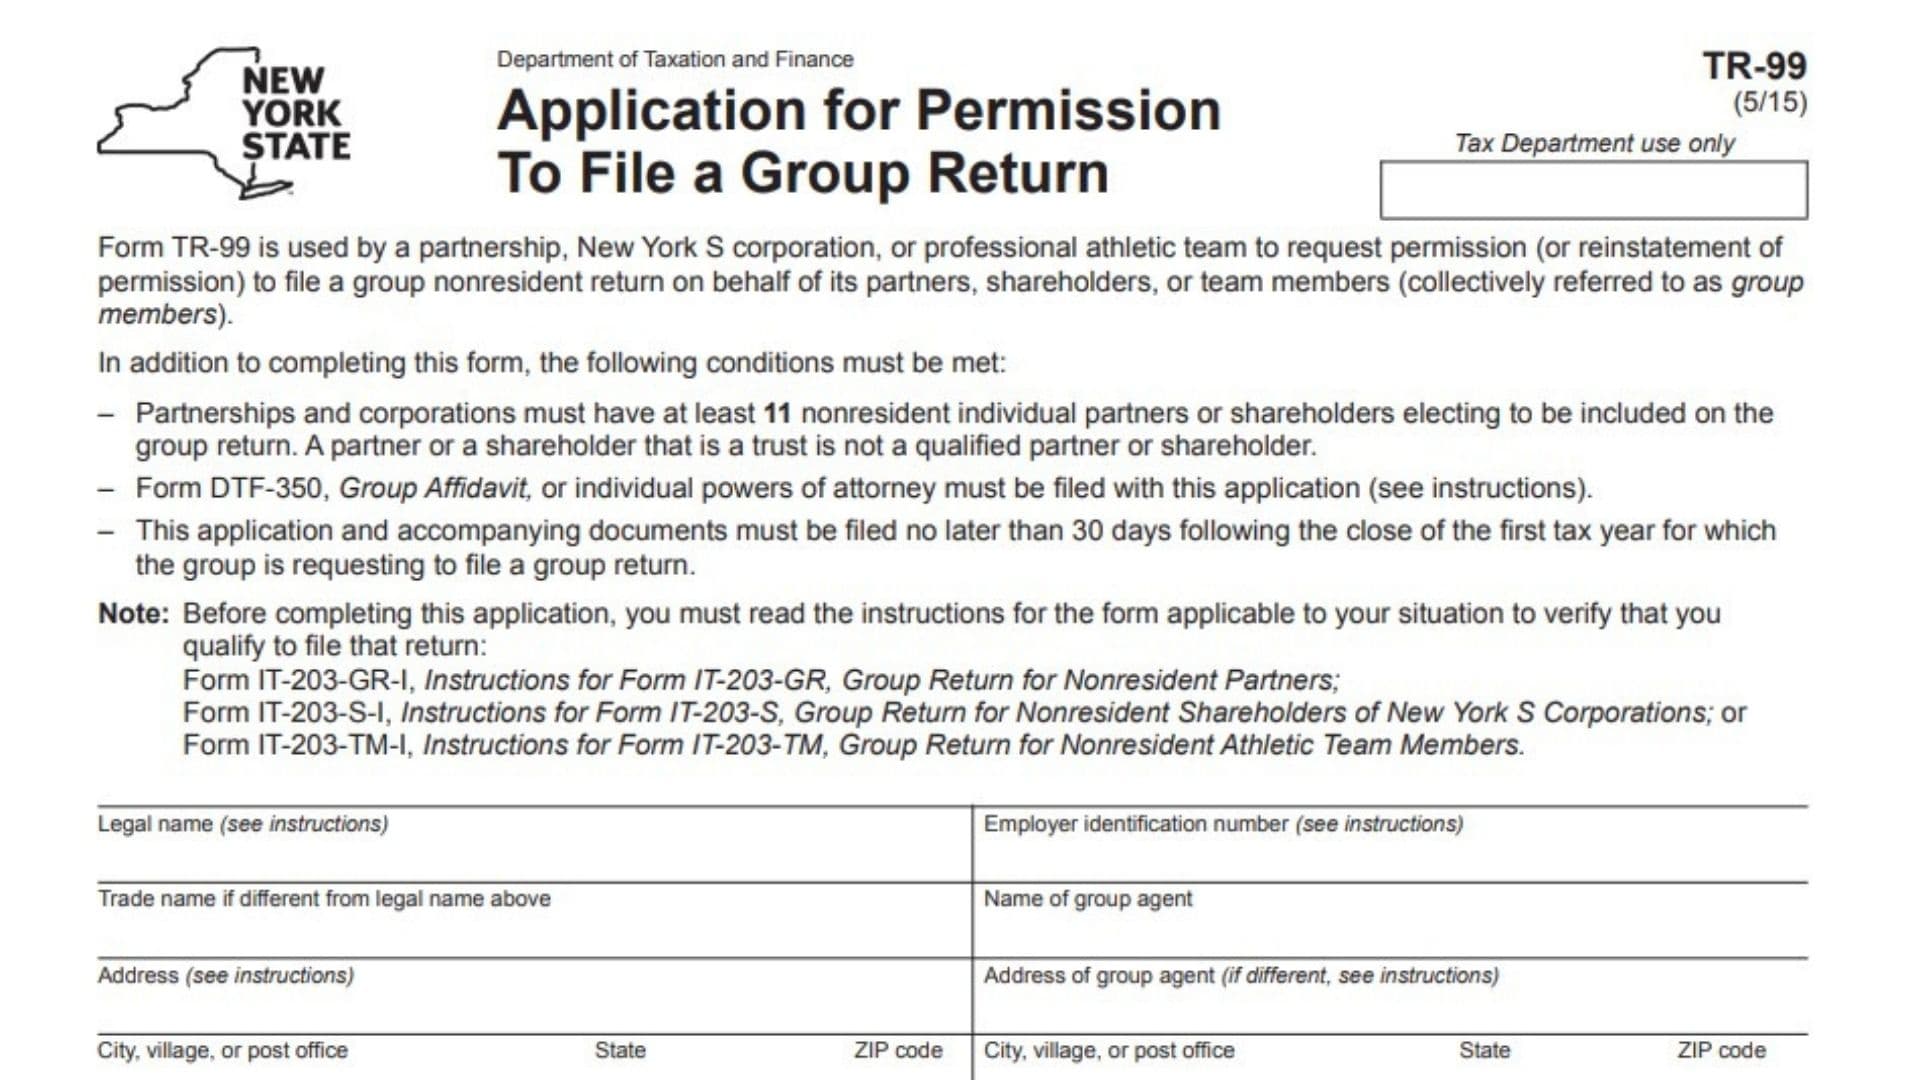
New York Form TR-99, Application for Permission to File a Group Return, is an application used by partnerships, New York S corporations, and professional athletic teams to request authorization from the New York State Department of Taxation and Finance to file a group nonresident income tax return on behalf of eligible partners, shareholders, or athletic team members. It can also be used by groups that previously received approval but want to reinstate their permission after one or more years without filing a group return. Instead of requiring each eligible nonresident member to file a separate New York State nonresident income tax return, an approved group can report the participating members through a single group return under the applicable filing requirements. The application collects the business’s legal name, federal employer identification number, mailing address, group agent information, type of participating nonresident members, first tax year covered by the group return, and the number of individuals electing to participate. It also asks whether participating members made individual estimated tax payments during the first tax year. The group must provide the required authorization documents, either individual powers of attorney for participating members or Form DTF-350, Group Affidavit. The group agent must certify that they understand the group return requirements, agree to act as the group’s representative, have the necessary legal authority, and have obtained the required member authorizations. Approval is not automatic. The New York State Department of Taxation and Finance reviews the application and accompanying documents to determine whether the group qualifies. If approved, the department assigns a special New York identification number that must be used when filing the group’s nonresident return and making group estimated tax payments. Completing Form TR-99 accurately and submitting it within the required timeframe is important because the group cannot rely on the requested filing arrangement until the department approves the application.
Who Can Apply for Permission to File a Group Return?
Form TR-99 is designed for three types of applicants:
- Partnerships requesting permission to file a group return for eligible nonresident partners.
- New York S corporations requesting permission to file a group return for eligible nonresident shareholders.
- Professional athletic teams requesting permission to file a group return for eligible nonresident team members.
The application must satisfy the applicable eligibility and documentation requirements.
Minimum Number of Participating Members
Partnerships and corporations must have at least 11 nonresident individual partners or shareholders who elect to participate in the group return.
A partner or shareholder that is a trust does not count as a qualified partner or shareholder for this minimum-member requirement.
Professional athletic teams are also covered by Form TR-99, but the 11-member requirement stated for partnerships and corporations should not automatically be applied to athletic teams. Consult the applicable athletic team group-return instructions for their specific eligibility requirements.
Required Authorization Documents
Every application must include one of the following authorization options:
- Individual powers of attorney for each qualified nonresident group member who will participate.
- Form DTF-350, Group Affidavit, covering the entire group.
These documents establish the group agent’s authority to represent the participating members in filing the group return.
Application Deadline
The application and all accompanying documents must be filed no later than 30 days after the close of the first tax year for which the group is requesting permission to file a group return.
Make sure the application and required authorization documents are submitted within this period.
How To File Form TR-99
Form TR-99 must be submitted to the New York State Department of Taxation and Finance, Individual Account Resolution.
The application must be accompanied by the required powers of attorney or Form DTF-350.
Before completing the form, applicants should review the instructions for the specific group nonresident return they intend to file.
Which Instructions Should You Read?
The appropriate instructions depend on the type of group applying.
Form IT-203-GR-I
Read these instructions if a partnership is requesting permission to file Form IT-203-GR, Group Return for Nonresident Partners.
Form IT-203-S-I
Read these instructions if a New York S corporation is requesting permission to file Form IT-203-S, Group Return for Nonresident Shareholders of New York S Corporations.
Form IT-203-TM-I
Read these instructions if a professional athletic team is requesting permission to file Form IT-203-TM, Group Return for Nonresident Athletic Team Members.
Review the instructions that apply to your organization before submitting Form TR-99 to verify that the group meets the relevant filing requirements.
Documents to Prepare Before Completing Form TR-99
Gather the following information before starting the application:
- Partnership, corporation, or athletic team’s legal name.
- Trade name or DBA, if applicable.
- Employer Identification Number (EIN).
- Complete business mailing address.
- Group agent’s full name.
- Group agent’s address, if different from the business address.
- Type of nonresident group members participating.
- First tax year for which the group return will be filed.
- Number of nonresident members electing to participate.
- Information about individual estimated tax payments made by participating members.
- Individual powers of attorney or Form DTF-350.
- Group agent’s signature, title, telephone number, and date.
For reinstatement applications, also prepare the special New York identification number previously assigned to the group, if known.
How To Complete Form TR-99
Form TR-99 contains business identification fields, four application items, a certification section, and instructions for submitting the required authorization documents.
Complete each section using accurate information about the organization and its participating nonresident members.
Business Identification Information
Legal Name
Enter the complete legal name of the partnership, New York S corporation, or professional athletic team applying for permission to file a group return.
The legal name refers to the name under which the business owns property or acquires debt.
Use the organization’s official legal name rather than a trade name.
Employer Identification Number (EIN)
Enter the federal Employer Identification Number assigned to the partnership, New York S corporation, or athletic team.
Make sure the number belongs to the organization submitting the application.
Trade Name
Enter the organization’s trade name if it operates under a name different from its legal business name.
For example, if a partnership’s legal name differs from the name it uses publicly, enter the publicly used trade name in this field.
If there is no separate trade name, leave this field blank.
Name of Group Agent
Enter the full name of the individual who will act as the group’s representative for purposes of filing the group nonresident return.
The group agent is responsible for representing the participating members and handling the group return filing process.
Make sure the individual named here is the person who will sign the certification section.
Business Address
Enter the complete address of the partnership, corporation, or athletic team.
Provide the appropriate street address or mailing address used by the organization.
Address of Group Agent
Enter the group agent’s address if it is different from the business address.
If the group agent uses the same address as the organization, a separate address does not need to be provided.
Business City, Village, or Post Office
Enter the city, village, or post office associated with the organization’s address.
Business State
Enter the two-letter postal abbreviation for the state where the organization’s address is located.
Business ZIP Code
Enter the ZIP code associated with the business address.
Group Agent City, Village, or Post Office
If the group agent has a different address, enter the city, village, or post office associated with that address.
Group Agent State
Enter the two-letter postal abbreviation for the state associated with the group agent’s separate address.
Group Agent ZIP Code
Enter the ZIP code for the group agent’s address if it differs from the organization’s address.
Item A: Type of Application
Item A identifies whether the organization is requesting permission for the first time or applying to restore previously granted permission.
Select the appropriate application type.
New Application
Select this option if the organization has never previously requested permission to file a group nonresident return.
A new application requires you to identify the type of nonresident group members who will participate.
The form provides three classifications:
- Nonresident Partners: Select this option if the group consists of eligible nonresident partners of a partnership.
- Nonresident Shareholders: Select this option if the group consists of eligible nonresident shareholders of a New York S corporation.
- Nonresident Team Members: Select this option if the application relates to eligible nonresident members of a professional athletic team.
Select the classification that corresponds to the organization and the group return being requested.
Application for Reinstatement
Select this option if the organization previously received approval to file a group return but subsequently did not file a group return for one or more years and now wants to resume filing under the group arrangement.
This option is not intended for an organization requesting permission for the first time.
Special New York Identification Number Previously Issued to the Group
If you are applying for reinstatement, enter the special New York identification number previously assigned to the group.
Use the number issued by the New York State Department of Taxation and Finance when the original application was approved.
If the number is known, enter it accurately in the designated space.
Item B: First Tax Year for the Group Return
First Tax Year for Which the Group Return Will Be Filed
Enter the first tax year for which the organization intends to file a group nonresident return.
This identifies the tax year covered by the permission request.
Make sure the year corresponds to the organization’s intended group return filing period.
The application deadline is calculated from the close of this first tax year. The completed application and accompanying documents must be submitted no later than 30 days after that tax year ends.
Item C: Number of Electing Nonresident Group Members
Number of Nonresident Group Members Electing to Participate
Enter the total number of nonresident individuals who have elected to participate in the group return.
Count the individuals the group agent knows have elected to participate as of the date Form TR-99 is submitted.
Do not include individuals who have not elected to participate.
For partnerships and corporations, at least 11 nonresident individual partners or shareholders must elect to participate.
A partner or shareholder that is a trust does not qualify toward this minimum requirement.
Use the number of participating individuals supported by the applicable authorization documents.
Item D: Individual Estimated Tax Payments
Were Individual Estimated Tax Payments Made by Electing Group Members?
This question asks whether any participating group members made individual estimated tax payments for the first tax year covered by the group return.
Select Yes if one or more electing group members made individual estimated tax payments for that first tax year.
Select No if none of the participating members made individual estimated tax payments for that year.
Answer based on the estimated tax payment information available when preparing the application.
This question specifically concerns individual estimated payments made by the electing group members, not simply payments made by the organization.
Certification: Group Agent Declaration
The certification section must be completed by the person designated as the group agent.
By signing, the group agent confirms three important matters:
- They have read and understand the rules governing group return filing and agree to serve as the group’s agent.
- To the best of their knowledge, the participating members agree to follow and satisfy the conditions required for group return participation when the application is submitted.
- They have the legal authority to act on behalf of the group and are submitting the required powers of attorney when applicable.
Complete the following fields.
Signature of Group Agent
The individual identified as the group agent must sign the application.
The signature confirms agreement to act as the group’s representative and certifies the statements included in the application.
Title
Enter the group agent’s official title or position within the organization.
Examples may include Partner, President, Managing Member, or another appropriate position.
Telephone
Enter the group agent’s contact telephone number, including the area code.
Provide a working number where the New York State Department of Taxation and Finance can reach the representative.
Date
Enter the date the group agent signs the application.
Use the appropriate date format and ensure the date is accurate.
Powers of Attorney and Form DTF-350 Requirements
The application must include either individual powers of attorney or Form DTF-350, Group Affidavit.
These documents establish the authority of the group agent to represent the nonresident members participating in the group return.
Individual Powers of Attorney Option
If the organization chooses individual powers of attorney, it must submit a separate power of attorney for each qualified nonresident group member whom the group agent knows will participate when the application is submitted.
Each document must authorize the group agent to represent that particular member in filing the group nonresident return.
The powers of attorney should cover every participating member identified in the application.
Additional Requirement for Reinstatement Applications
If the organization is applying for reinstatement, new powers of attorney must be submitted for all electing group members.
This requirement applies even if the organization previously submitted powers of attorney for some or all of those members with its original application.
Do not assume that previously submitted authorization documents automatically remain sufficient for reinstatement.
Form DTF-350: Group Affidavit Option
Instead of submitting separate individual powers of attorney, the organization may submit Form DTF-350, Group Affidavit, for the entire group.
This document serves as the alternative authorization option identified in the Form TR-99 instructions.
Choose either the individual powers of attorney option or the group affidavit option and include the required documentation with the application.
Organizing Individual Powers of Attorney
When submitting individual powers of attorney, arrange the documents in one of the following orders:
- Alphabetical order.
- Social Security number order.
Organizing the documents properly helps the department review the participating members’ authorization information.
Where to Mail Form TR-99
After completing the application and preparing the required supporting documents, send the entire package to the following address:
New York State Tax Department
Individual Account Resolution
W A Harriman Campus
Albany, NY 12227-0822
Include:
- Completed Form TR-99.
- Individual powers of attorney arranged alphabetically or by Social Security number, if using that option; or
- Form DTF-350, Group Affidavit, if using the group affidavit option.
Make sure all required documents accompany the application.
What Happens After You Submit Form TR-99?
Submitting Form TR-99 does not automatically authorize the organization to file a group nonresident return.
The New York State Department of Taxation and Finance reviews the application and supporting documents to determine whether the group qualifies.
The department will notify the applicant of its decision.
Special New York Identification Number
If the application is approved, the department assigns a special New York identification number to the group.
This number must be used for:
- Filing the group’s nonresident return.
- Making group estimated tax payments.
Keep the assigned identification number available for future group return filings and related tax payments.
Important Rules to Remember When Filing Form TR-99
Before submitting the application, review these important requirements.
At Least 11 Qualified Members for Partnerships and Corporations
Partnerships and corporations must have at least 11 nonresident individual partners or shareholders electing to participate.
Trusts that are partners or shareholders do not count toward this minimum.
The Group Agent Must Have Legal Authority
The individual signing the application must have the authority to represent the participating group members.
The required powers of attorney or Group Affidavit must accompany the application.
Reinstatement Requires New Authorization Documents
Organizations applying for reinstatement must submit new powers of attorney for all electing members, even if authorization documents were provided previously.
The Application Deadline Is Strictly Connected to the First Tax Year
The application and supporting documents must be filed no later than 30 days after the close of the first tax year for which the group return is requested.
Approval Must Be Received Before Using the Group Identification Number
The department reviews the application and notifies the organization of its decision. If approved, it issues a special New York identification number for group returns and group estimated tax payments.
Final Review Before Filing
Before mailing Form TR-99, review the application and supporting documents using the following checklist.
Organization Information
- The correct legal business name is entered.
- The organization’s EIN is accurate.
- The trade name is provided when applicable.
- The group agent’s full name is entered.
- The business address is complete.
- The group agent’s separate address is provided when applicable.
- The city, state, and ZIP code information is correct.
Application Details
- The correct application type is selected.
- The appropriate nonresident group member classification is identified for a new application.
- The reinstatement box is selected when applicable.
- The previously issued special New York identification number is entered for reinstatement when known.
- The first tax year for the group return is entered correctly.
- The number of electing nonresident group members is accurate.
- Partnerships and corporations meet the minimum requirement of 11 qualified nonresident individual members.
- Trusts are not counted as qualified partners or shareholders toward the minimum.
- Item D correctly indicates whether participating members made individual estimated tax payments.
Authorization Documents
- Individual powers of attorney or Form DTF-350 are included.
- Each individual power of attorney authorizes the group agent to represent the participating member.
- All participating members known at the time of application are covered.
- New powers of attorney are included for every electing member if applying for reinstatement.
- Individual powers of attorney are arranged alphabetically or by Social Security number when applicable.
- Form DTF-350 is completed when using the group affidavit option.
Certification and Submission
- The group agent has reviewed the certification.
- The group agent’s signature is provided.
- The group agent’s title is entered.
- The telephone number is correct.
- The signature date is provided.
- The completed application and supporting documents will be submitted within 30 days after the close of the first tax year.
- The application is addressed to the Individual Account Resolution unit at the W A Harriman Campus in Albany, New York.
After submission, wait for the New York State Tax Department’s approval notice. If approved, retain the special New York identification number and use it when filing the group’s nonresident return and making group estimated tax payments.
Form TR-99 is an important application for partnerships, New York S corporations, and professional athletic teams seeking permission to file group nonresident returns. By completing the organization information, identifying participating members, providing the correct authorization documents, and obtaining approval from the New York State Department of Taxation and Finance, the group can establish the required filing arrangement for its eligible nonresident members.