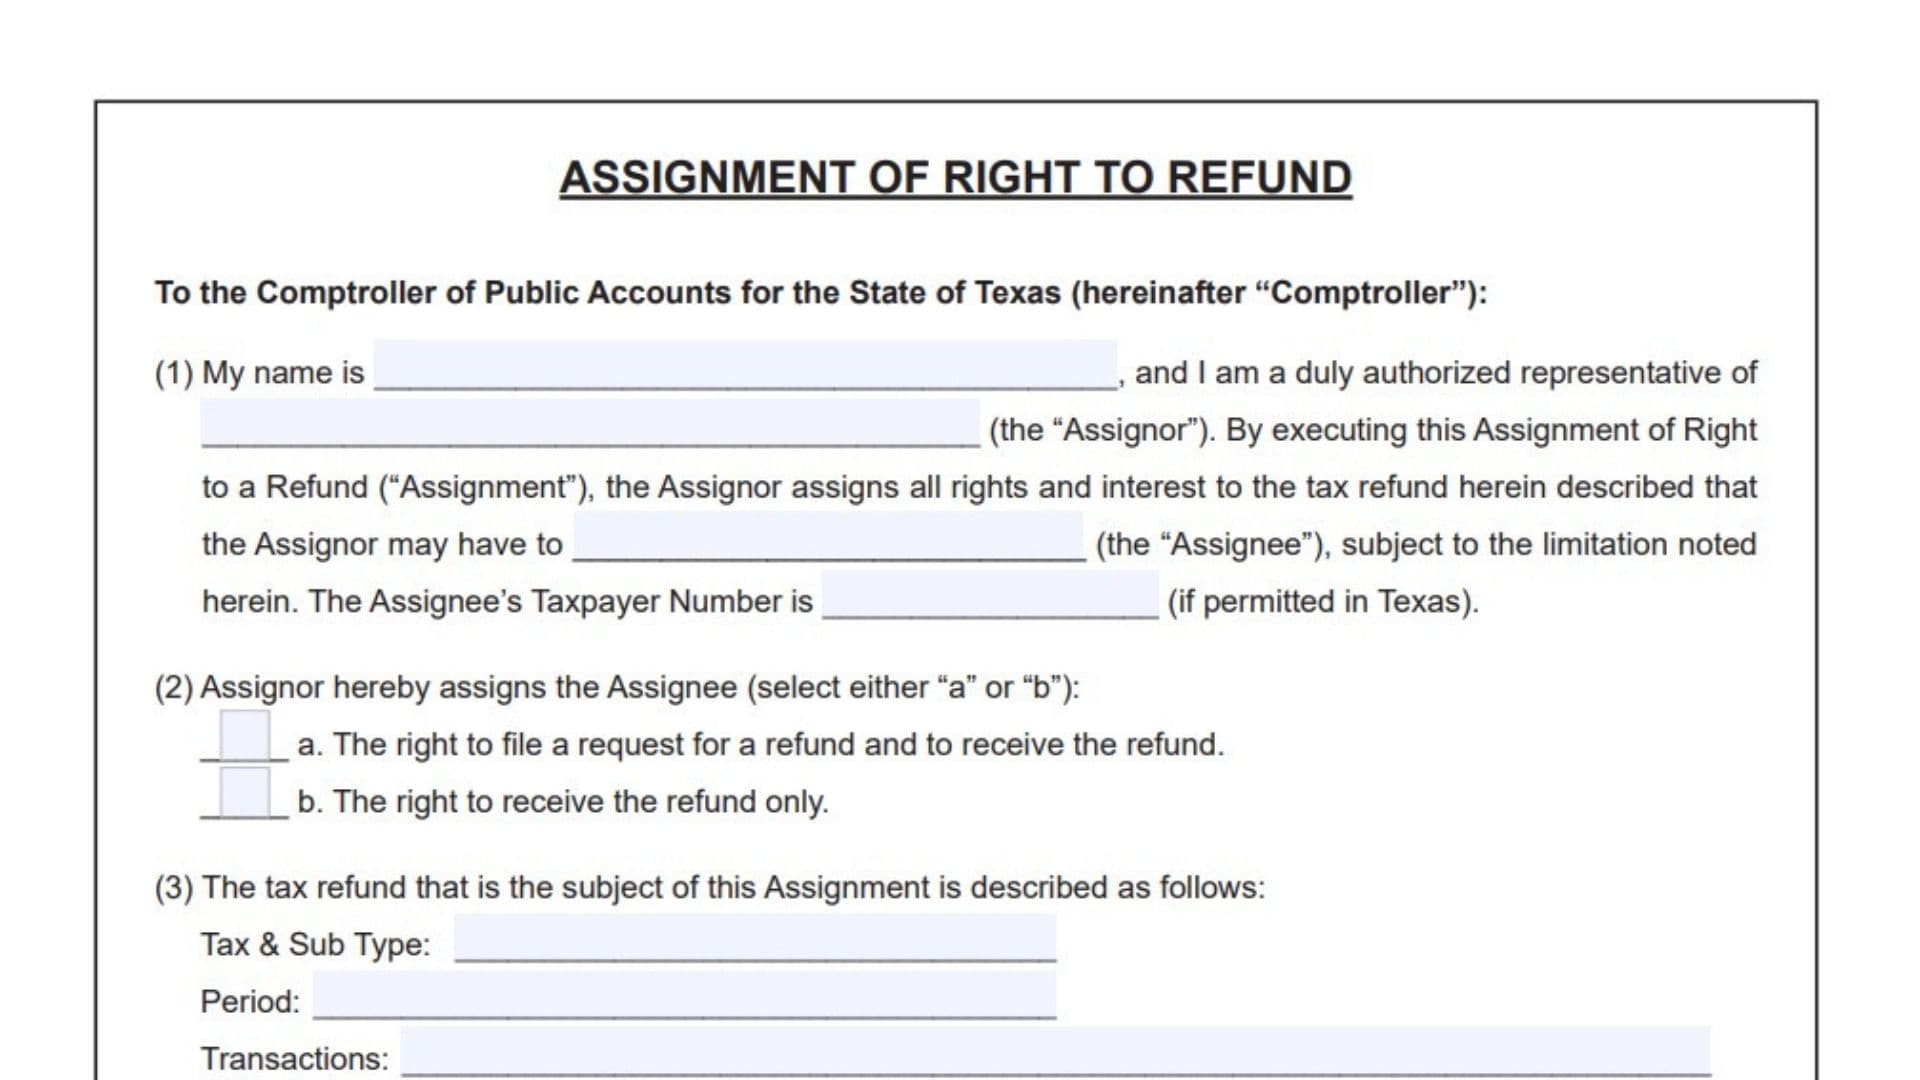
Texas Form 00-985 is a legal transfer agreement used to reassign tax refund rights from a permitted seller or taxpayer to another party, typically a purchaser who paid sales tax in error. Under Texas tax administrative rules, when a non-permitted buyer pays sales tax on exempt purchases, statutory policy generally directs the buyer to seek reimbursement from the vendor who collected the tax. Alternatively, the vendor may formally assign its legal refund rights to the purchaser, enabling the buyer to file a claim directly with the Texas Comptroller of Public Accounts. Form 00-985 establishes this transfer of interest, prevents double recovery by binding the assignor from claiming credits on future returns, and gives state auditors the legal authority to pay refund warrants directly to the designated assignee.
How To File Form 00-985
Taxpayers and claimants submit this completed assignment instrument alongside their primary refund application, such as Form 00-957, directly to the Comptroller. Because this assignment must be active and valid upon receipt, it must be submitted before the expiration of the four-year statute of limitations applicable to the underlying tax payments. Once a refund claim has been forwarded to an audit field office for verification, the state will not accept supplemental or amended assignment forms; any late additions require a completely separate standalone refund petition subject to its own statutory postmark deadline.
Assemble the following items before completing the document:
- The legal entity names and contact details for both the assignor and assignee.
- The eleven-digit Texas Taxpayer Number for the permitted seller.
- The assignee’s Texas Taxpayer Number, if the assignee holds an active state tax permit.
- A complete list of all invoice numbers or production leases included in the claim.
- An itemized transaction schedule to attach to the document if transactions exceed available blank lines.
- Power of attorney documentation if an outside representative manages the claim.
The purchaser or designated claimant submits the signed assignment along with the master refund petition and itemized supporting invoices either by email to the Comptroller’s refund processing division or by mail directly to:
Comptroller of Public Accounts
Revenue Accounting Division
Sales & Motor Vehicle Tax Refunds
111 E. 17th Street
Austin, TX 78774-0100
How To Complete Form 00-985
Form 00-985 contains legal party recitals, assignment authority elections, transaction specifications, binding compliance affirmations, and authorized corporate execution blocks. The printed text of this document cannot be altered, amended, or struck through in any manner.
Party Identification
Field: Authorized Representative Name
Type or print the full legal name of the individual executing the document on behalf of the assigning entity. This individual must be an authorized officer, partner, or tax manager directly responsible for the entity’s state tax reporting.
Field: Assignor Entity Name
Enter the formal legal business name of the assigning entity exactly as registered in Comptroller tax records. This entry must correspond identically with the entity name recorded in the signature section.
Field: Assignee Legal Name
Provide the complete legal name of the individual or company receiving the right to the refund. This name must match the claimant name appearing on the accompanying refund petition.
Field: Assignee’s Taxpayer Number
Input the assignee’s official eleven-digit Texas Taxpayer Number if the assignee maintains an active permit in Texas; leave this field blank if the assignee is an unpermitted retail consumer or non-permitted business entity. For Crude Oil or Natural Gas Production Tax refund claims, this line cannot be left blank, as the assignee must hold an active production tax permit across all requested periods.
Scope of Assignment
Elect the precise legal authority transferred to the assignee by marking only one of the two available checkboxes:
Checkbox a: Right to File and Receive Refund
Select this option if the assignee is authorized both to prepare and submit the formal refund claim to the state and to receive the resulting state refund warrant directly.
Checkbox b: Right to Receive Refund Only
Mark this choice if the assignor retains the sole duty to file the refund petition with the state while directing the Comptroller to issue the payment warrant exclusively to the assignee.
Refund Description and Restrictions
Field: Tax & Sub Type
Identify the specific tax category and applicable sub-classification involved in the overpayment, such as Sales and Use Tax or Crude Oil Production Tax.
Field: Period
Record the exact beginning and ending calendar date range covering all assigned transactions. While the assigned date span may be broader than the actual refund petition, state auditors will only review transactions that fall within both the requested range and the four-year statutory limitations window.
Field: Transactions
List the specific commercial transactions covered by the assignment, identifying them by exact seller invoice numbers. For Crude Oil or Natural Gas Production Tax claims, enter the official names and state identification numbers of the specific leases. If there is insufficient space to write all invoice numbers or lease references, compile a separate itemized schedule and write a notation referencing the attached exhibit. The referenced schedule must be physically attached to this document when the assignor signs it and remain attached upon delivery to the state, or the assignment will be rendered completely void.
Field: Other Specific Limitations
State any explicit restrictions imposed by the assignor, such as excluding specific invoices from an otherwise continuous date range, capping the total dollar amount assigned, or limiting claims to specific statutory exemptions or marketing cost allowances. Leave this line blank if the assignment encompasses the full value of the designated transactions without reservations.
Legal Affirmations and Undertakings
Paragraphs 4 and 5 establish binding statutory commitments governing the transfer:
- Paragraph 4 confirms that the assignor acknowledges both parties may be required by state examiners to produce additional commercial documentation, books, and records to verify the validity of the overpayment.
- Paragraph 5 affirms under penalty of law that the assignor has not previously received a refund or claimed a tax credit for the identified transactions on any historical tax return, and explicitly forfeits the right to ever claim a future refund or credit for those same transactions.
Assignor Corporate Execution
This execution panel must be completed by an authorized employee of the assignor whose primary employment duties involve managing state tax administration, such as a corporate director, officer, partner, managing member, company controller, or tax manager. Comptroller personnel routinely conduct third-party verification to confirm the signer holds proper operational authority.
Field: Assignor Entity Name
Print the exact legal corporate name of the assigning company, matching the name entered in the opening paragraph.
Field: Assignor Taxpayer Number
Provide the assignor’s eleven-digit Texas state taxpayer identification number under which the original transactions and taxes were remitted. Do not enter a nine-digit federal employer identification number.
Field: Print or Type Name of Person Authorizing Assignment
Type or clearly print the full personal name of the corporate officer or authorized tax representative signing the form.
Field: Relationship to Entity
Specify the signer’s formal corporate or administrative title, explicitly indicating their role as Officer, Director, Partner, Managing Member, Controller, or Tax Manager.
Field: Signature of Person Authorizing Assignment
The authorized corporate representative must sign by hand or via an authenticated electronic signature to finalize the legal transfer.
Field: Date
Enter the calendar date on which the authorized representative executes the assignment.
Field: Area Code/Daytime Phone Number
Provide an active daytime telephone number where state tax auditors can contact the authorized signer directly to verify signing authority.
Final Review Before Filing
- Confirm that none of the standard preprinted statutory text on the form has been edited, erased, or crossed out.
- Ensure the assignor entity name and representative name match identically in both the opening body text and the execution block.
- Verify that only one assignment option checkbox is marked.
- Check that the assignor’s eleven-digit Texas Taxpayer Number is provided instead of a federal identification number.
- Ensure that all individual invoice numbers are itemized or listed on an attached exhibit physically affixed to the form prior to signing.
- Confirm the form is signed by a qualified corporate officer, partner, or tax controller possessing documented tax administrative authority.
- Verify that the assignee’s legal name matches the master refund petition.
- Submit the executed document to the Comptroller before the four-year statute of limitations expires.