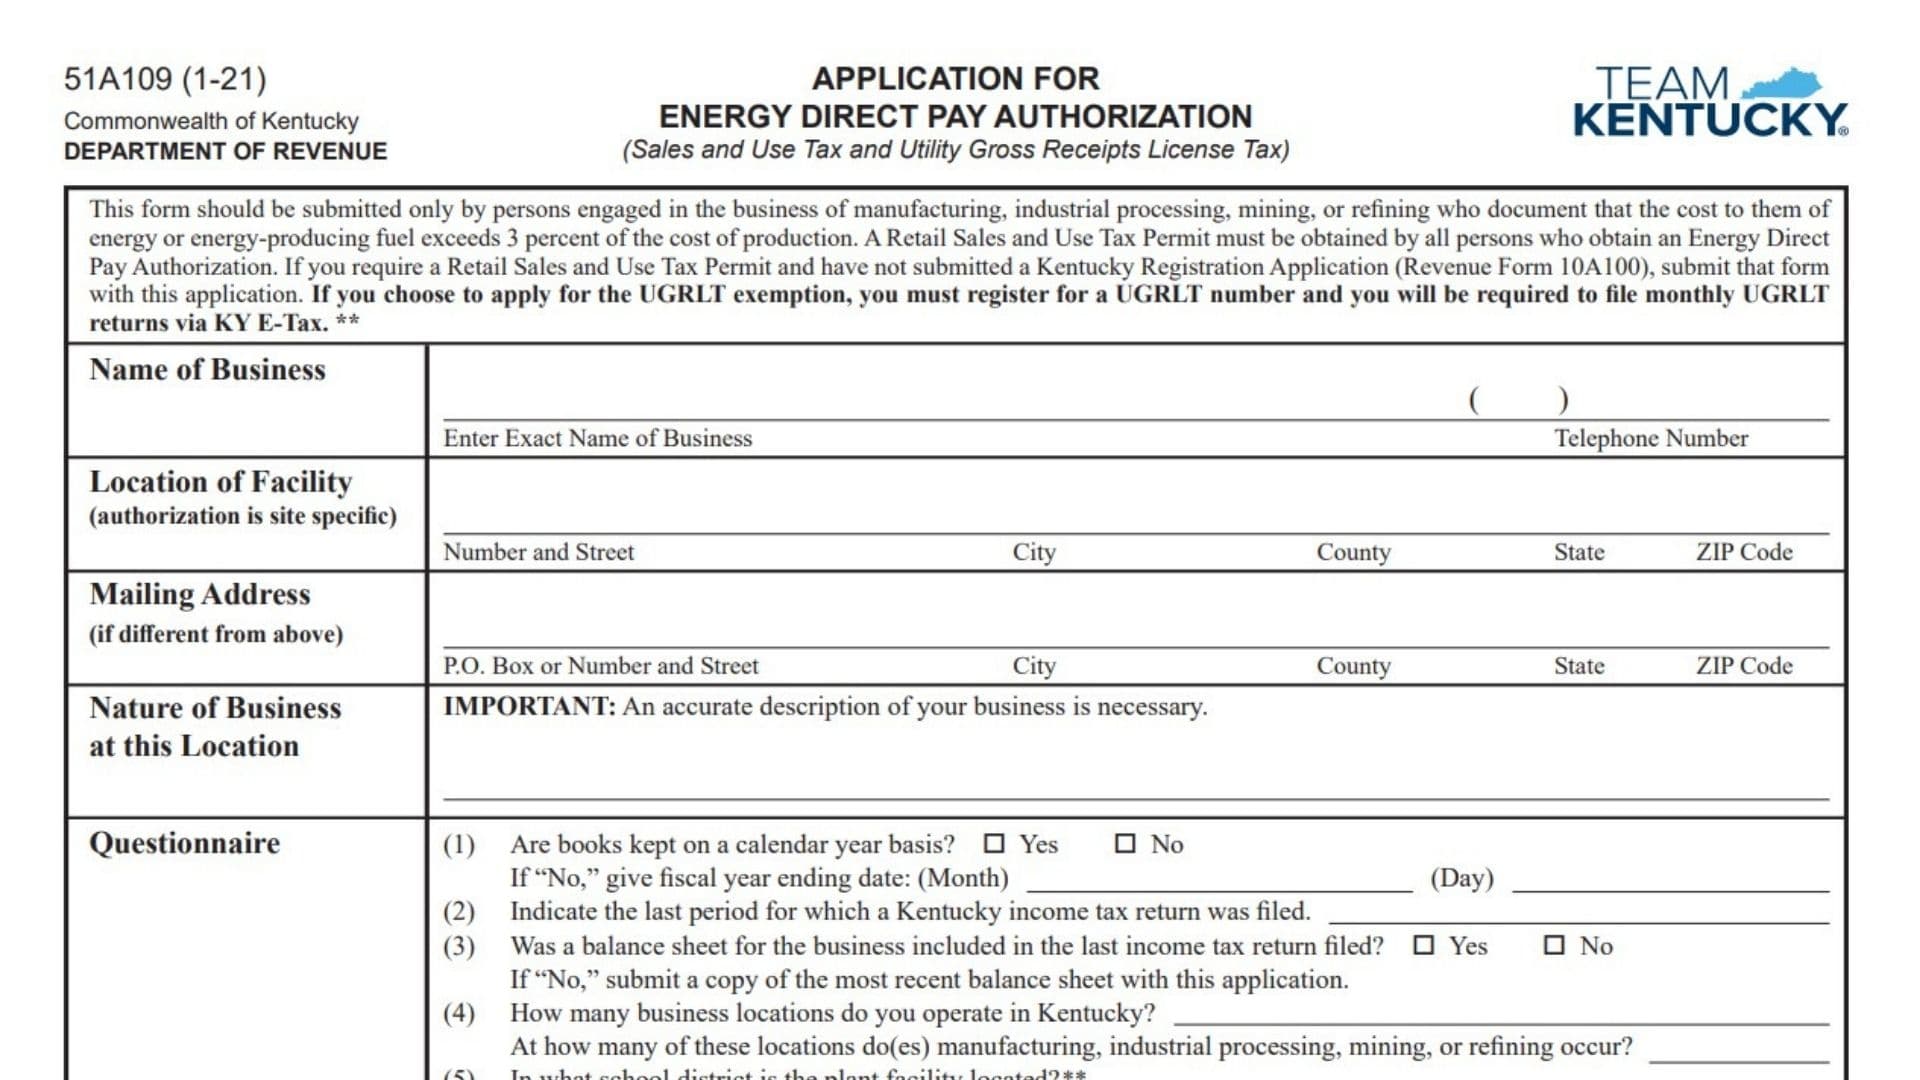
Kentucky Form 51A109 is the Application for Energy Direct Pay Authorization for Sales and Use Tax and Utility Gross Receipts License Tax. This form is used by qualifying businesses that purchase energy or energy-producing fuel and can demonstrate that the cost of energy exceeds the required percentage of production costs.
The application is intended for businesses engaged in manufacturing, industrial processing, mining, or refining activities. Applicants must document that the cost of energy or energy-producing fuel is greater than 3% of the cost of production.
An approved Energy Direct Pay Authorization allows the qualified business to purchase eligible energy or energy-producing fuel without paying sales or use tax at the time of purchase. The business must then directly report and pay the applicable tax amount to the Kentucky Department of Revenue on the portion of energy costs subject to tax.
The authorization applies to a specific facility location. If a business operates multiple facilities, a separate application must be completed for each location requesting Energy Direct Pay Authorization.
How To File Form 51A109
Complete all required sections of the application and attach the required supporting documents before submitting the form.
Mail the completed application to:
Kentucky Department of Revenue
Division of Sales and Use Tax
PO Box 1303
Frankfort, KY 40602-1303
Before filing, prepare:
- Energy purchase invoices from the last completed fiscal or calendar year
- Cost of production schedule excluding energy costs
- Supplier information
- Facility details
- Tax account numbers
- Business ownership and contact information
Applicants must include copies of invoices for all energy purchases made during the last completed fiscal or calendar year. A detailed schedule showing production cost classifications and amounts must also be attached.
How To Complete Form 51A109
Business Information
This section collects information about the business applying for Energy Direct Pay Authorization.
Name Of Business
Enter the exact legal name of the business applying for authorization.
Telephone Number
Enter the business telephone number, including area code.
Location Of Facility
Provide the physical location of the facility requesting authorization.
The authorization is site-specific, meaning the approval applies only to the facility location listed on the application.
Include:
- Street address
- City
- County
- State
- ZIP code
Mailing Address
Enter the mailing address if it is different from the facility location.
Include:
- PO Box or street address
- City
- County
- State
- ZIP code
Nature Of Business At This Location
Provide an accurate description of the business activities performed at the facility.
A detailed business description is required because eligibility depends on the type of operation conducted at the location.
Questionnaire
Business Accounting Information
Are Books Kept On A Calendar Year Basis?
Select Yes if the business maintains accounting records using a calendar year.
Select No if the business uses a fiscal year.
Fiscal Year Ending Date
If the business does not use a calendar year, enter the month and day when the fiscal year ends.
Last Period Kentucky Income Tax Return Was Filed
Enter the most recent tax period for which the business filed a Kentucky income tax return.
Was A Balance Sheet Included With The Last Income Tax Return Filed?
Select Yes if a balance sheet was included with the most recent Kentucky income tax return.
Select No if it was not included.
If No is selected, attach the most recent balance sheet with the application.
Number Of Business Locations Operated In Kentucky
Enter the total number of business locations operated by the company in Kentucky.
Number Of Locations Where Manufacturing, Industrial Processing, Mining, Or Refining Occurs
Enter how many Kentucky locations perform qualifying activities such as manufacturing, industrial processing, mining, or refining.
School District Of Plant Facility
Enter the school district where the plant facility is located.
Identification Numbers
Provide applicable tax identification numbers.
Utility Gross Receipts License Tax (UGRLT) Number
Enter the UGRLT number if one has already been issued.
Sales And Use Tax Permit Account Number
Enter the Kentucky Sales and Use Tax Permit Account Number.
Kentucky Corporation Income Tax Number
Enter the Kentucky corporation income tax identification number.
Supplier And Amount Of Energy Or Energy-Producing Fuel
This section identifies energy suppliers and the amount of energy purchased.
Name Of Supplier
Enter the name of each energy supplier.
Address Of Supplier
Provide the supplier’s address.
Type Of Energy Or Energy-Producing Fuel Purchased
Describe the type of energy or fuel purchased.
Cost Of Energy Or Energy-Producing Fuel Purchased In Previous Year
Enter the amount spent on energy or energy-producing fuel during the previous year.
Total Amount
Enter the combined total cost of all listed energy purchases.
Applicants must submit copies of vendor invoices supporting the listed purchases.
Sales And Use Tax Energy Direct Pay Computation
This section calculates the amount of energy cost eligible for direct pay treatment.
Line 1: Cost Of Production In Previous Year Excluding Cost Of Energy Or Energy-Producing Fuel
Enter the previous year’s production cost excluding energy and energy-producing fuel expenses.
Attach a separate schedule explaining the production cost calculation.
The cost of production must be calculated based on plant facilities.
Line 2: 3% Of Cost Of Production Excluding Energy Or Energy-Producing Fuel
Multiply Line 1 by 3%.
This determines the maximum energy cost amount considered within the production cost threshold.
Line 3: Estimated Monthly Cost Of Energy Or Energy-Producing Fuel Subject To Sales Tax
Divide Line 2 by 12.
Enter the estimated monthly energy cost subject to sales tax.
UGRLT Energy Direct Pay Computation
This section applies only if the applicant requests the Utility Gross Receipts License Tax exemption.
Applying For UGRLT Exemption
Do You Wish To Apply For The UGRLT Exemption At This Time?
Select Yes if applying for UGRLT exemption.
Select No if applying only for sales and use tax Energy Direct Pay Authorization.
If applying for UGRLT exemption, additional questions must be completed.
Businesses applying for UGRLT exemption must register for a UGRLT number and file monthly UGRLT returns electronically through KY E-Tax.
Line 4: Total Cost Of Energy Purchased In Previous Year
Enter the total cost of energy purchased during the previous year.
Line 5: Less Energy Not Subject To UGRLT
Subtract energy costs that are not subject to UGRLT.
Refer to the applicable instructions when determining excluded energy costs.
Line 6: Balance Of Energy Subject To UGRLT
Subtract Line 5 from Line 4.
Calculation:
Line 4 − Line 5 = Line 6
Line 7: Cost Of Production For UGRLT Computation
Add Line 1 and Line 5.
Calculation:
Line 1 + Line 5 = Line 7
Line 8: 3% Of Cost Of Production For UGRLT
Multiply Line 7 by 3%.
Line 9: Estimated Monthly Cost Of Energy Subject To UGRLT
Divide Line 8 by 12.
Enter the estimated monthly energy cost subject to UGRLT.
Certification And Signature
The applicant must certify that all information provided is correct and that the signer has authority to submit the application.
Signature
The authorized person must sign the application.
Title
Enter the signer’s official position.
Print Name
Enter the signer’s printed name.
Date
Enter the date the application is signed.
Email Address
Provide an email address for communication.
Cost Of Production Supporting Schedule
Applicants must attach a schedule showing production costs excluding energy or energy-producing fuel.
The calculation should include applicable categories such as:
- Direct materials
- Direct labor
- Plant equipment depreciation
- Plant equipment insurance
- Plant equipment taxes
- Plant building rent or depreciation
- Heat, lights, and water
- Compensation insurance
- Indirect materials
- Indirect labor
- Miscellaneous factory expenses
- Administrative expenses allocated to production
- Office expenses allocated to production
For coal mines and quarries, additional costs must be included:
- Rents
- Royalties
- Cost depletion
- Reclamation
- Severance tax
Important Information After Approval
If approved, the business may purchase qualifying energy or energy-producing fuel without paying sales or use tax and, when applicable, UGRLT at the time of purchase. The business must estimate taxable energy costs and remit applicable tax monthly.
The Department of Revenue will issue an authorization letter for each approved exemption. The business must provide copies of these letters to energy suppliers, and suppliers must maintain them as proof that purchases qualify for tax exemption.
Approved businesses must report estimated monthly taxable energy costs on the required tax returns and reconcile actual taxable energy costs through annual returns filed after the end of the fiscal or calendar year.
Final Review Before Filing
Before submitting Form 51A109, verify the following:
- Confirm the facility qualifies for Energy Direct Pay Authorization.
- Ensure the application is completed for each qualifying facility location.
- Provide accurate business and facility information.
- Include supplier details and energy purchase invoices.
- Attach the required production cost schedule.
- Confirm production costs exclude energy expenses.
- Complete the Sales and Use Tax computation.
- Complete UGRLT sections if requesting UGRLT exemption.
- Provide required tax identification numbers.
- Sign and date the application.
- Keep copies of all submitted documents for your records.
- Mail the completed application and supporting documents to the Kentucky Department of Revenue.