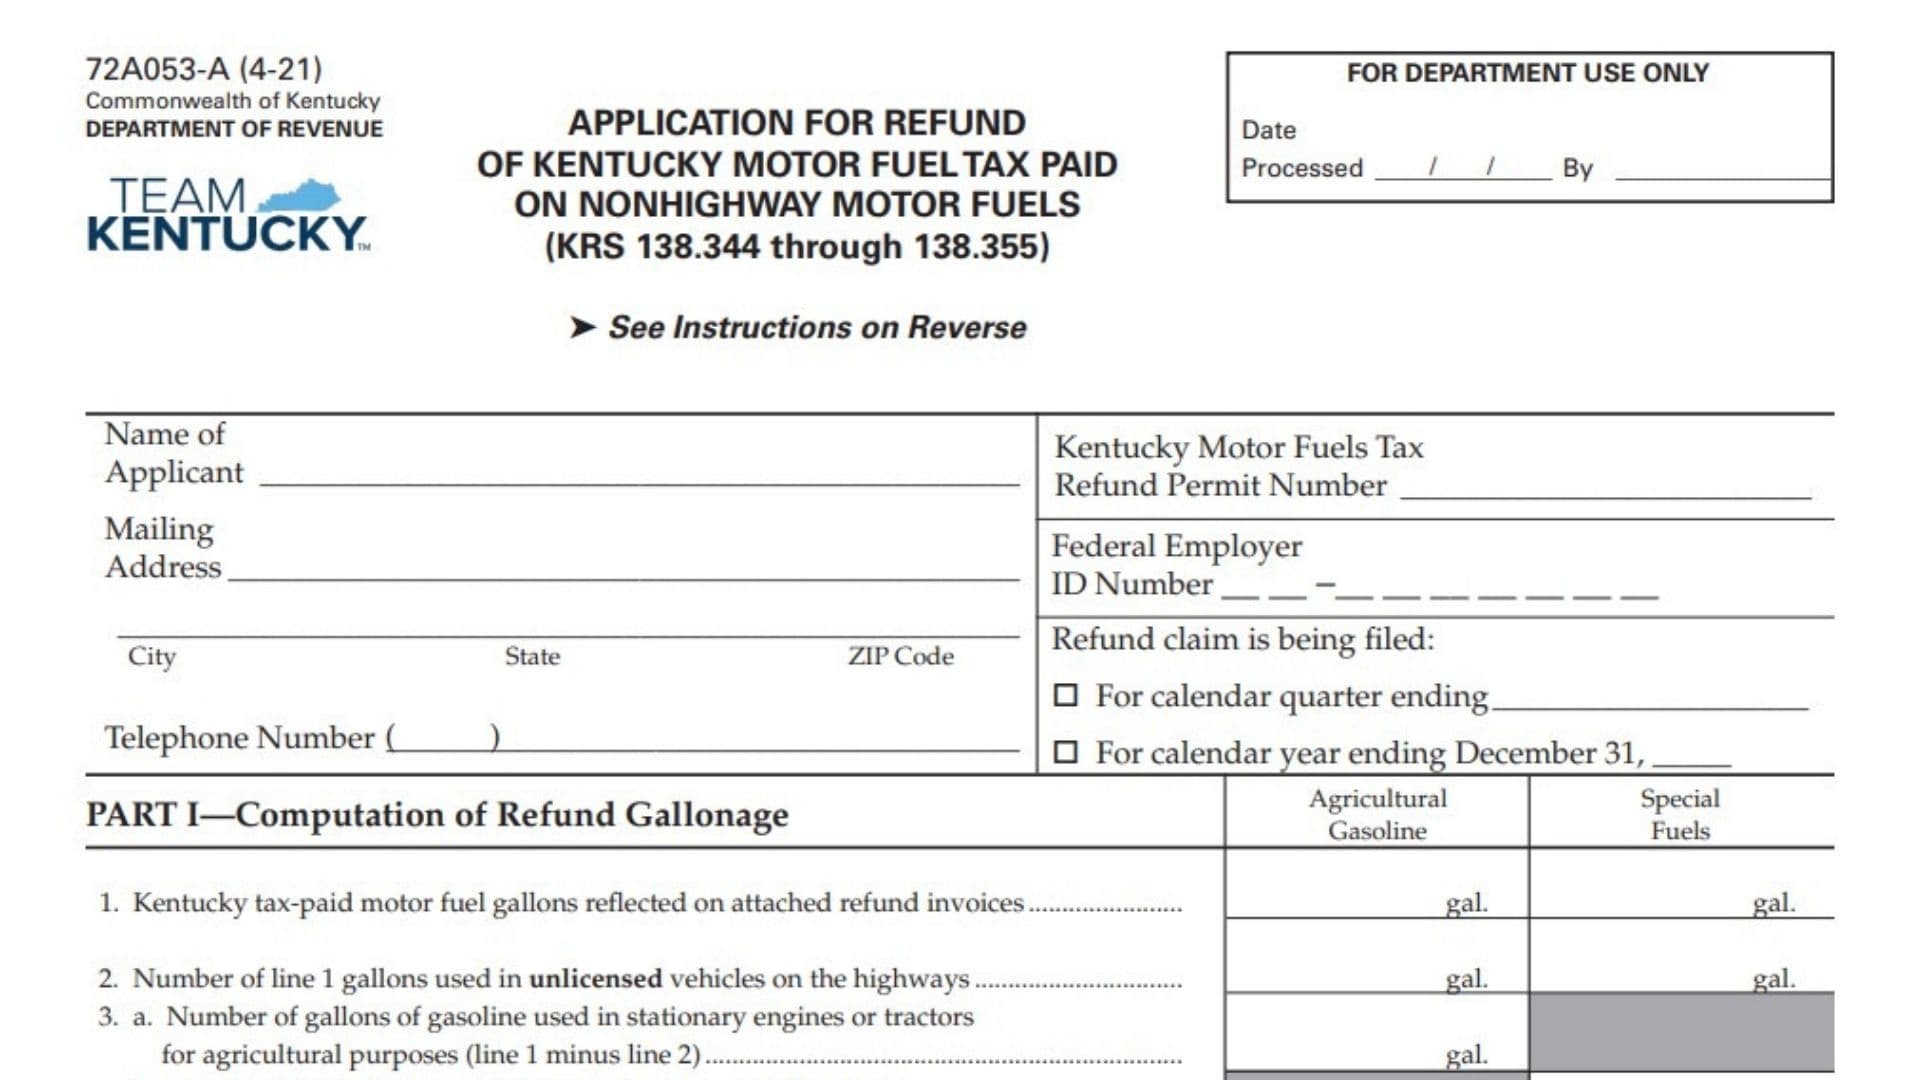
Kentucky Form 72A053-A, Application for Refund of Kentucky Motor Fuel Tax Paid on Nonhighway Motor Fuels, is used by Kentucky motor fuels tax refund permit holders to request refunds associated with qualifying nonhighway motor fuel use under KRS 138.344 through 138.355. The application covers qualifying agricultural gasoline and special fuels and is used to calculate both the Kentucky motor fuels tax refund and the Petroleum Environmental Assurance Fee refund. Applicants report Kentucky tax-paid gallons supported by refund invoices, remove gallons that do not qualify, calculate any Kentucky sales tax that must be deducted from the special fuels refund, and then determine the net motor fuels tax refund. The form also calculates a separate Petroleum Environmental Assurance Fee refund, for which a separate check is issued. Accurate completion is important because refund claims must be supported by original, unaltered invoices from licensed motor fuel dealers, and only qualifying purchases made after the refund permit became effective may be included.
Who Should Use Kentucky Form 72A053-A?
This application is intended for a holder of a Kentucky Motor Fuels Tax Refund Permit who is claiming a refund for qualifying nonhighway fuel use.
The form provides separate reporting columns for:
- Agricultural gasoline
- Special fuels
The qualifying gallonage is determined in Part I, after which the form calculates applicable sales tax, motor fuel tax refunds, and Petroleum Environmental Assurance Fee refunds.
The instructions require refund claims to be filed on either a calendar quarter or calendar year basis.
How To File Kentucky Form 72A053-A
Mail the completed application to:
Kentucky Department of Revenue
Motor Fuels Tax Compliance Section
P.O. Box 1303, Station 63
Frankfort, KY 40602-1303
For forms, information, or assistance, the form provides the Motor Fuels Tax Compliance Section telephone number:
(502) 564-3853
Documents To Prepare Before Completing the Form
Before starting the application, gather:
- Your Kentucky Motor Fuels Tax Refund Permit Number.
- Your Federal Employer ID Number.
- Your Kentucky Sales Tax Permit Number, when applicable.
- Original refund invoices from licensed gasoline or special fuels dealers.
- Total Kentucky tax-paid gallons shown on those invoices.
- Purchase prices, including taxes paid, for qualifying special fuels.
- Itemized Kentucky motor fuels tax shown by your records.
- Itemized Petroleum Environmental Assurance Fees.
- Information showing how the fuel was actually used.
- The appropriate filing-period ending date.
The original invoices attached to the application must show the itemized taxes and fees charged.
Purchases That Do Not Qualify
Do not include purchases made before the effective date of your Kentucky motor fuels tax refund permit.
The instructions also state that purchases made from retail filling stations do not qualify for a refund.
How To Complete Kentucky Form 72A053-A
Begin with the applicant, permit, and filing-period information at the top of the application. Then complete Parts I through IV in order.
Applicant Information
Name of Applicant
Enter the full name of the person, business, or organization holding the Kentucky motor fuels tax refund permit and making the refund claim.
Use the same applicant name associated with your permit and supporting refund records.
Mailing Address
Enter the applicant’s complete mailing address.
The form provides space for the street or mailing address followed by the city, state, and ZIP code.
City
Enter the city associated with the applicant’s mailing address.
State
Enter the state.
ZIP Code
Enter the correct ZIP code for the mailing address.
Telephone Number
Enter a current telephone number where the applicant or an authorized representative can be reached.
Include the area code.
Tax and Permit Identification
Kentucky Motor Fuels Tax Refund Permit Number
Enter the refund permit number assigned to the applicant.
Make sure the permit was effective before the fuel purchases included in the claim. Purchases made before the permit’s effective date are not refundable.
Federal Employer ID Number
Enter the applicant’s Federal Employer Identification Number in the format provided.
Review every digit carefully before filing.
Refund Filing Period
The application gives you two filing-period options.
Select the box that applies to your claim.
For Calendar Quarter Ending
Check this box when the refund application covers a calendar quarter.
Enter the ending date of the quarter in the space provided.
For Calendar Year Ending December 31
Check this box when filing the refund claim for an entire calendar year.
Enter the applicable year after December 31.
Use the filing period that corresponds with the purchases and invoices included in the application.
Part I: Computation of Refund Gallonage
Part I determines how many gallons qualify for the Kentucky motor fuels tax refund.
The table contains separate columns for Agricultural Gasoline and Special Fuels. Keep the gallon totals for these fuel categories separate.
Line 1: Kentucky Tax-Paid Motor Fuel Gallons
Enter the total Kentucky tax-paid motor fuel gallons shown on the refund invoices attached to the application.
Enter agricultural gasoline gallons in the Agricultural Gasoline column.
Enter special fuel gallons in the Special Fuels column.
Only include gallons supported by qualifying refund invoices.
Line 2: Gallons Used in Unlicensed Vehicles on the Highways
From the gallons entered on line 1, enter the number of gallons used in unlicensed vehicles on the highways.
Report the applicable gallons separately for agricultural gasoline and special fuels.
These gallons are deducted when determining the qualifying gallonage on line 3.
Line 3a: Agricultural Gasoline Used in Stationary Engines or Tractors
Complete this line for agricultural gasoline.
Enter the number of gallons of gasoline used in stationary engines or tractors for agricultural purposes.
Calculate the amount as:
Line 1 Agricultural Gasoline − Line 2 Agricultural Gasoline = Line 3a
The Special Fuels field for line 3a is not intended for an entry.
Line 3b: Special Fuels Used for Nonhighway Purposes
Complete this line for special fuels.
Enter the number of gallons of special fuels used in unlicensed vehicles or equipment for nonhighway purposes.
Calculate:
Line 1 Special Fuels − Line 2 Special Fuels = Line 3b
The Agricultural Gasoline field for line 3b is not intended for an entry.
Part II: Computation of Kentucky Sales Tax To Be Deducted From Special Fuels Tax Refund
Part II applies to the sales tax associated with the special fuels refund.
Before calculating lines 4 through 8, enter your Kentucky Sales Tax Permit Number and determine whether the special fuel qualifies for one of the sales tax exemptions listed on the application.
Kentucky Sales Tax Permit Number
Enter your Kentucky Sales Tax Permit Number in the space provided, when applicable.
Special Fuel Sales Tax Exemption
If you claim that the special fuel reported on line 3 is exempt from the 6% Kentucky sales tax, identify the applicable reason.
If you claim an exemption, the form instructs you not to complete the remainder of Part II. Instead, proceed directly to Part III.
Energy Direct Pay Authorization Checkbox
Check this box if you hold an Energy Direct Pay Authorization and are using that as the reason for the sales tax treatment.
Fuel Used for Agricultural Purposes Checkbox
Check this box when claiming the listed exemption for fuel used for agricultural purposes pursuant to KRS 139.480.
Other Checkbox
Check Other when your claimed exemption is based on another reason.
Other – Description
If you select Other, describe the reason for claiming the sales tax exemption in the space provided.
Do not continue with lines 4 through 8 if you are claiming one of the listed exemptions. Proceed to Part III as instructed on the form.
If you are not claiming an exemption, complete lines 4 through 8.
Line 4: Total Purchase Price of Refund Special Fuels
Enter the total purchase price of all refund special fuels shown on the attached refund invoices.
Include all taxes paid in this amount.
This is the starting amount for calculating the Kentucky sales tax that will be deducted from the special fuels tax refund.
Line 5a: Purchase Price of Gallons Reported on Line 2
Enter the purchase price, including all taxes you paid, for the special fuel gallons reported on line 2.
These are gallons that are being removed from the qualifying calculation.
Line 5b: Kentucky Special Fuels Tax Paid
Calculate the Kentucky special fuels tax paid on the applicable gallons reported on line 3.
Enter the applicable Kentucky tax rate in the rate space shown as:
(.____)
Then calculate:
Kentucky Special Fuels Tax Rate × Applicable Line 3 Gallons = Line 5b
Use the appropriate rate supported by the records applicable to the refund claim rather than guessing a rate.
Line 5c: Kentucky Petroleum Environmental Assurance Fee
Calculate the Petroleum Environmental Assurance Fee paid on the gallons reported on line 3.
The form provides a rate of:
0.014
Calculate:
Line 3 Gallons × 0.014 = Line 5c
Enter the result.
Line 5d: Total Deduction
Add lines 5a, 5b, and 5c.
The calculation is:
Line 5a + Line 5b + Line 5c = Line 5d
Enter the combined deduction amount.
Line 6: Amount Subject to Kentucky Sales Tax
Subtract line 5d from line 4.
Calculate:
Line 4 − Line 5d = Line 6
This produces the amount subject to Kentucky sales tax.
Line 7: Kentucky Sales Tax Rate
The Kentucky sales tax rate shown on the form is:
0.06, or 6%
The rate is already provided on the application.
Line 8: Total Kentucky Sales Tax Due
Multiply line 6 by line 7.
Calculate:
Line 6 × 0.06 = Line 8
Enter the result.
This sales tax amount will later be deducted from the special fuels motor fuel tax refund.
Part III: Motor Fuels Refund Computation
Part III calculates the motor fuels tax refund.
The form again separates Agricultural Gasoline and Special Fuels, so complete the applicable amounts in their respective columns.
Line 9: Total Gallons Subject to Kentucky Motor Fuels Tax Refund
Carry the qualifying gallon amounts from line 3 to line 9.
For agricultural gasoline, use the qualifying gasoline gallons determined on line 3a.
For special fuels, use the qualifying special fuel gallons determined on line 3b.
The line 9 figures should therefore agree with the applicable line 3 figures.
Line 10: Gross Motor Fuels Tax Refund Claimed
Multiply the line 9 qualifying gallons by the applicable motor fuels tax rate.
Calculate separately for each applicable fuel category:
Line 9 Gallons × Tax Rate = Line 10 Gross Refund
Enter the agricultural gasoline gross refund in the Agricultural Gasoline column.
Enter the special fuels gross refund in the Special Fuels column.
The application does not print a fixed tax rate beside line 10, so use the applicable tax rate for the fuel and filing period supported by your refund records.
Line 11: Sales Tax Liability
For special fuels, enter the same Kentucky sales tax liability calculated on line 8.
The form places this amount in parentheses because it is being deducted from the special fuels refund.
Line 11 does not provide a corresponding entry for agricultural gasoline.
If you properly claimed a special-fuel sales tax exemption in Part II and were instructed to skip the Part II calculation, follow the exemption treatment applicable to your claim rather than creating a line 8 amount that was not calculated.
Line 12: Net Motor Fuels Tax Refund Claimed
Determine the net refund.
For special fuels, calculate:
Line 10 − Line 11 = Line 12
Enter the resulting net special fuels refund.
For agricultural gasoline, the form does not show a sales tax liability entry on line 11, so the agricultural gasoline net refund carries the applicable gross refund through to line 12.
This line represents the motor fuels tax refund being claimed after the applicable sales tax deduction.
Part IV: Petroleum Environmental Assurance Fee Refund Computation
Part IV calculates the refund of the Petroleum Environmental Assurance Fee.
The reverse-side instructions state that this application is used for both the motor fuels tax refund and the Petroleum Environmental Assurance Fee refund, and that a separate check will be issued for the fee refund.
Line 13: Total Gallons Subject to Petroleum Environmental Assurance Fee
Enter the same qualifying gallons reported on line 9.
Carry the applicable agricultural gasoline gallons to the Agricultural Gasoline column.
Carry the applicable special fuel gallons to the Special Fuels column.
Do not recalculate the gallonage differently from line 9.
Line 14: Fee Refund Claimed
Multiply the gallons on line 13 by 0.014.
Calculate separately for each applicable fuel category:
Line 13 Gallons × 0.014 = Line 14
Enter the resulting Petroleum Environmental Assurance Fee refund in the appropriate column.
Certification and Signature
The certification at the bottom of the application is an important part of the refund claim.
By signing, the refund permit holder or authorized representative certifies that:
- The motor fuel tax refund is supported by correct and unaltered refund invoices.
- The invoices were issued by a licensed motor fuels dealer.
- The fuel for which the refund is claimed was placed in a tank marked “Refund Motor Fuel.”
- The information provided on the application is true to the best of the signer’s knowledge and belief.
- None of the fuel for which the refund is claimed was or will be used in licensed vehicles on public highways.
Review your invoices, gallon calculations, and fuel-use records carefully before signing this certification.
Signature of Refund Permit Holder or Authorized Representative
The refund permit holder or an authorized representative should sign the application.
The signer should review the entire application before signing because the signature certifies the accuracy of the claim and the qualifying use of the fuel.
Date
Enter the date the application is signed.
Complete the month and day as appropriate and enter the applicable year after the preprinted “20” portion.
Original Invoice Requirements
Original invoices from the licensed gasoline or special fuels dealer must be attached to the refund application.
The instructions require these invoices to show the itemized tax and fees charged.
Do not substitute unsupported gallon totals for the required invoice documentation.
The gallon amounts used in Part I should be traceable to the attached qualifying invoices.
Petroleum Environmental Assurance Fee Refund
This application is also used to claim a refund of the Petroleum Environmental Assurance Fee.
The fee refund is calculated separately in Part IV.
A separate check is issued for this fee refund rather than combining it into the same refund payment described for the motor fuels tax.
Important Fuel Purchase Restrictions
Two purchase restrictions appear in the form instructions.
Purchases Before Permit Effective Date
Fuel purchased before the effective date of the Kentucky Motor Fuels Tax Refund Permit is not refundable.
When reviewing your invoices, compare each purchase date with the effective date of your permit and exclude purchases made too early.
Purchases From Retail Filling Stations
Purchases from retail filling stations do not qualify for the refund.
Do not include those purchases in line 1 or any later refund calculation.
Department Use Only
The upper portion of the application contains a box marked FOR DEPARTMENT USE ONLY.
Applicants should not complete this area.
Date Processed
Leave this field blank. It is intended for Department processing.
By
Leave this field blank. It is for the Department representative who processes the application.
Do not enter applicant information, filing dates, or signature information in this box.
Common Kentucky Form 72A053-A Mistakes to Avoid
Do not include fuel purchases made before your refund permit became effective.
Do not include purchases from retail filling stations.
Attach the original qualifying invoices rather than relying only on your own summary of purchases.
Make sure the invoices show itemized taxes and fees.
Do not combine agricultural gasoline and special fuels into one total. The form maintains separate columns for these fuel categories.
On line 3a, report only the qualifying agricultural gasoline calculation.
On line 3b, report only the qualifying special fuels calculation.
If claiming the special fuel sales tax exemption in Part II, select the appropriate exemption reason and follow the instruction to skip the remainder of Part II.
If you are not claiming the exemption, complete every calculation from line 4 through line 8.
Use the 6% sales tax rate printed on line 7 rather than entering a different percentage without an applicable basis.
Make sure line 9 agrees with the qualifying gallonage from line 3.
Do not forget to carry the Part II sales tax liability to line 11 for the special fuels refund when applicable.
Make sure line 13 agrees with line 9 before calculating the Petroleum Environmental Assurance Fee refund.
Finally, do not sign the certification until you have verified that the claimed fuel meets the certification conditions.
Final Review Before Filing
Before submitting Kentucky Form 72A053-A, verify that:
- The applicant’s full name is correct.
- The mailing address is complete.
- The city, state, and ZIP code are accurate.
- The telephone number is correct.
- The Kentucky Motor Fuels Tax Refund Permit Number is entered.
- The FEIN is accurate.
- The correct calendar-quarter or calendar-year filing box is selected.
- The filing-period ending date or year is complete.
- All claimed purchases occurred after the refund permit became effective.
- No purchases from retail filling stations are included.
- Original invoices from licensed dealers are attached.
- The invoices show itemized taxes and fees.
- Line 1 agrees with the qualifying invoices.
- Agricultural gasoline and special fuels are reported separately.
- Line 2 is completed correctly for each applicable fuel category.
- Line 3a equals agricultural gasoline line 1 minus line 2.
- Line 3b equals special fuels line 1 minus line 2.
- The Kentucky Sales Tax Permit Number is entered when applicable.
- Any special fuel sales tax exemption is properly identified.
- The correct exemption checkbox is selected when an exemption is claimed.
- An explanation is provided when Other is selected.
- Lines 4 through 8 are left uncompleted when the form’s exemption instruction applies.
- Line 4 includes the required total purchase price of refund special fuels.
- Lines 5a, 5b, and 5c are calculated correctly.
- Line 5d equals the total of lines 5a, 5b, and 5c.
- Line 6 equals line 4 minus line 5d.
- Line 7 uses the preprinted 0.06 sales tax rate.
- Line 8 equals line 6 multiplied by line 7.
- Line 9 agrees with line 3.
- Line 10 uses line 9 multiplied by the applicable motor fuels tax rate.
- Line 11 carries the applicable special fuels sales tax liability from line 8.
- Line 12 correctly reflects the net motor fuels tax refund.
- Line 13 agrees with line 9.
- Line 14 equals line 13 gallons multiplied by 0.014.
- The fuel being claimed was placed in a tank marked “Refund Motor Fuel.”
- None of the fuel being claimed was or will be used in licensed vehicles on public highways.
- The refund permit holder or authorized representative has signed the application.
- The certification date is entered.
- The Department-use-only section has been left blank.
- The completed application and original supporting invoices are ready to be mailed to the Kentucky Department of Revenue, Motor Fuels Tax Compliance Section.