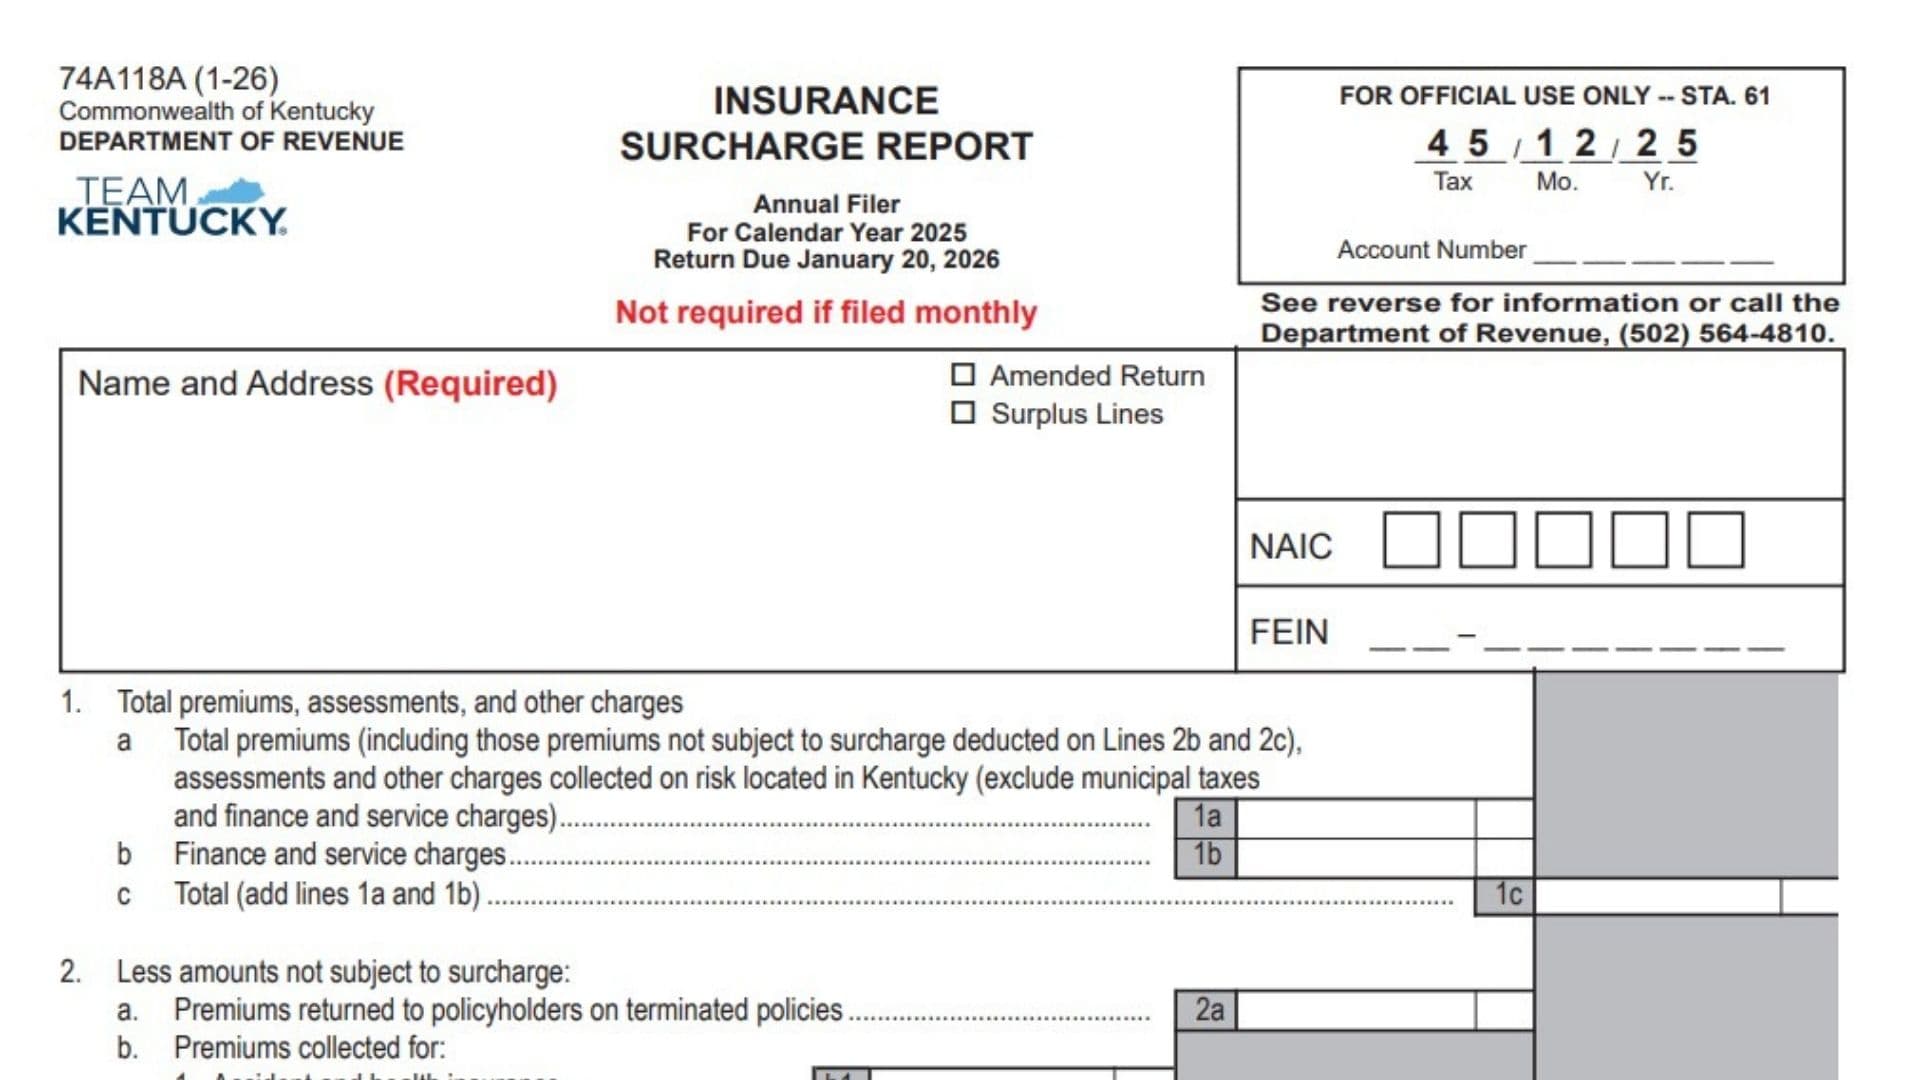
Kentucky Form 74A118A, the Insurance Surcharge Report, is used to report and remit Kentucky’s insurance premium surcharge on premiums, assessments, and certain other charges collected on risks located in Kentucky. The surcharge generally applies to domestic, foreign, and alien insurers, other than life and health insurers, that are subject to or exempt from the Kentucky insurance premium taxes referenced by the form. Insurers collect the surcharge from policyholders when the related insurance premium or other covered charge is collected and then report the amount to the Kentucky Department of Revenue. The form starts with total premiums and related charges, removes premiums and policyholders that are specifically exempt from the surcharge, calculates the taxable amount, applies the current 1.8% surcharge rate, and adds any penalty, interest, or adjustments. Form 74A118A also provides fields for amended returns, surplus-lines filers, online payments, and certification by a principal officer and preparer. Every required filing period must be reported even when no premiums were collected, so accurate and timely completion is important for both surcharge reporting and payment compliance.
Who Must File Form 74A118A?
Kentucky requires covered insurers to report insurance premium surcharge activity for each applicable filing period.
The filing instructions state that every insurer required to report the surcharge must file for each period even when no premiums were collected.
Most filers report and remit the surcharge monthly. The monthly return and payment are generally due by the 20th day of the month following the reporting period.
An insurer may qualify to report annually when its annual surcharge liability was less than $1,000 in each of the previous two calendar years. An eligible annual filer reports the surcharge collected for the calendar year by January 20 of the following year.
This version of Form 74A118A is specifically identified as an annual filing for calendar year 2025, with a return due date of January 20, 2026. The form also states that this annual return is not required when the taxpayer has already filed monthly.
How To File Form 74A118A
If paying by check, make the payment payable to:
Kentucky State Treasurer
Mail the return and payment to:
Kentucky Department of Revenue
P.O. Box 1303
Frankfort, KY 40602-1303
For overnight delivery, use:
Kentucky Department of Revenue
501 High Street
Frankfort, KY 40601-2103
If payment was made online, the completed report and the Payment Schedule Confirmation page should still be sent to one of the addresses above.
Before completing the report, gather:
- The company’s legal name and mailing address.
- Kentucky tax account information.
- NAIC number.
- FEIN.
- Total premiums collected on Kentucky risks.
- Assessments and other covered charges.
- Finance and service charges.
- Premiums returned on terminated policies.
- Premiums from insurance categories exempt from the surcharge.
- Premiums collected from exempt or partially exempt policyholders.
- Any approved adjustments and supporting documentation.
- Penalty and interest information when the filing or payment is late.
- Online payment confirmation information, if applicable.
- Principal officer and preparer information.
How To Complete Form 74A118A
Filing Status And Identification Information
For Official Use Only
Do not complete the section marked for official use. The tax period and Department processing information in this area are reserved for the Kentucky Department of Revenue.
Account Number
Enter the applicable Kentucky tax account number in the taxpayer-identification area when required.
For surplus-lines filings, follow the special account-number rules described below.
Amended Return
Check the Amended Return box if this report is being submitted to correct a Form 74A118A that was previously filed for the same reporting period.
Complete the corrected amounts throughout the return and include supporting information for changes when appropriate.
Surplus Lines
Check the Surplus Lines box when the report is being filed for surplus-lines insurance activity.
Surplus-lines filers should also follow the special identification instructions applicable to agencies and brokers.
NAIC
Enter the insurer’s applicable National Association of Insurance Commissioners identification number.
Use the identifying number associated with the reporting insurer.
FEIN
Enter the filer’s Federal Employer Identification Number.
For surplus-lines filings, the FEIN may also be used as the account identifier as explained in the special surplus-lines instructions.
Name and Address
Enter the complete legal name and mailing address of the company or filer.
This information is required.
Line 1: Total Premiums, Assessments, And Other Charges
Line 1 establishes the total amounts collected before allowable surcharge exclusions are deducted.
Premiums And Other Charges
Line 1a: Total Premiums, Assessments, and Other Charges
Enter the total premiums collected on risks located in Kentucky.
Include premiums that will later be deducted on lines 2b and 2c because they are not subject to the surcharge. Those exclusions are removed later in the calculation rather than being omitted from line 1a.
Also include applicable assessments and other covered charges.
Do not include:
- Municipal taxes.
- Finance charges.
- Service charges.
Finance and service charges are reported separately on line 1b.
The instructions specifically state that line 1a should contain only premiums that have actually been collected.
Line 1b: Finance and Service Charges
Enter the total finance and service charges applicable to the reporting period.
These charges are reported separately from the premiums entered on line 1a.
Line 1c: Total
Add lines 1a and 1b.
Use:
Line 1a + Line 1b = Line 1c
Enter the combined amount on line 1c.
Line 2: Amounts Not Subject to the Surcharge
Line 2 removes premiums and other amounts that are excluded from Kentucky’s insurance premium surcharge.
Returned Premiums
Line 2a: Premiums Returned on Terminated Policies
Enter premiums returned to policyholders when the related policies were terminated.
A deduction is allowed for qualifying returned premiums only when the associated surcharge was also returned to the policyholder.
The instructions make an important distinction: refunds or credits may be taken for premiums returned on terminated policies, but they cannot be claimed simply because the original premium related to an exempt type of insurance, such as workers’ compensation.
Refund requests must be made in writing.
Exempt Types of Insurance
Line 2b1: Accident and Health Insurance
Enter premiums collected for accident and health insurance.
These premiums are excluded from the insurance premium surcharge.
Line 2b2: Federal Insured Crop Insurance
Enter premiums collected for federally insured crop insurance.
These premiums are not subject to the surcharge.
Line 2b3: Federal Insured Flood Insurance
Enter premiums collected for federally insured flood insurance.
Report the applicable exempt amount here.
Line 2b4: Reinsurance
Enter premiums collected for reinsurance.
These premiums are excluded from the surcharge calculation.
Line 2b5: Title Insurance
Enter premiums collected for title insurance.
Report the exempt title-insurance premiums on this line.
Line 2b6: Workers’ Compensation
Enter premiums collected for workers’ compensation insurance.
Workers’ compensation premiums are not subject to the surcharge.
Line 2b: Total Premiums Collected for Exempt Insurance Types
Add lines 2b1 through 2b6.
Use:
2b1 + 2b2 + 2b3 + 2b4 + 2b5 + 2b6 = Line 2b
Enter the resulting total.
Premiums Collected From Exempt or Partially Exempt Policyholders
Line 2c1: Federal Government
Enter premiums collected from the federal government.
These amounts qualify for the exemption identified on the form.
Line 2c2: Resident Nonprofit Educational and Charitable Institutions
Enter qualifying premiums collected from Kentucky resident nonprofit educational or charitable institutions that have Section 501(c)(3) status.
Make sure the policyholder meets the required nonprofit and tax-exempt status before including the premium on this line.
Line 2c3: Resident Nonprofit Religious Institutions
Enter qualifying premiums collected from resident nonprofit religious institutions.
This exemption applies only to coverage of:
- Real property.
- Tangible property.
- Intangible property.
Do not apply this line automatically to every type of insurance purchased by a nonprofit religious institution.
Line 2c4: State and Local Government
Enter qualifying premiums collected from state or local governments for real property coverage only.
The exemption identified by the form is limited to the specified property coverage.
Line 2c: Total Premiums Collected From Exempt Policyholders
Add lines 2c1 through 2c4.
Use:
2c1 + 2c2 + 2c3 + 2c4 = Line 2c
Enter the combined amount.
Total Exclusions
Line 2d: Total Amount Not Subject to Surcharge
Add the qualifying amounts from lines 2a, 2b, and 2c.
Use:
Line 2a + Line 2b + Line 2c = Line 2d
This represents the total amount that can be removed from the surcharge base.
Calculating the Insurance Surcharge
Line 3: Amount Subject to Surcharge
Subtract line 2d from line 1c.
Use:
Line 1c – Line 2d = Line 3
The result represents the amount subject to Kentucky’s insurance premium surcharge.
Review the deductions on line 2 carefully before completing this calculation.
Line 4: Surcharge Due at Current Rate
Multiply line 3 by the surcharge rate shown on the form:
0.018, or 1.8%
Use:
Line 3 × 0.018 = Line 4
Enter the resulting surcharge due.
Penalty, Interest, And Adjustments
Line 5: Penalty
Enter any applicable penalty for late filing or late payment.
Do not add a penalty unless one applies to the filing.
The return instructions provide separate rules for late filing and late payment.
Line 6: Interest
Enter applicable interest when the surcharge liability was not paid by the original due date.
Interest runs from the original due date through the date of payment at the applicable Kentucky tax interest rate.
Line 7: Amount Due
Add lines 4, 5, and 6.
Use:
Line 4 + Line 5 + Line 6 = Line 7
This is the amount due before adjustments.
Line 8: Adjustments
Enter any applicable adjustment to the report.
The adjustment may increase or decrease the final amount depending on the circumstances.
Attach supporting documentation explaining and substantiating the adjustment.
Do not enter an unsupported adjustment.
Line 9: Total Amount Due
Apply the line 8 adjustment to line 7.
Use:
Line 7 + or – Line 8 = Line 9
Enter the final amount due on line 9.
Online Payment Information
Paid Online Checkbox
Check the Paid Online box if the liability reported on the return has been paid electronically.
Confirmation Number
Enter the confirmation number associated with the online payment.
The form requires the filer to attach the Payment Schedule Confirmation page when reporting an online payment.
Even when payment is made online, send the report and confirmation page to the Department using one of the listed mailing addresses.
Principal Officer Certification
A principal officer of the company must certify the report.
By signing, the officer confirms that the report has been examined and, to the best of the officer’s knowledge and belief, is true, correct, and complete.
Principal Officer’s Signature
The responsible principal officer should sign the return.
Title
Enter the principal officer’s official title.
Printed Name
Print the principal officer’s full name.
Date
Enter the date the principal officer signs the report.
Email Address
Provide the principal officer’s or appropriate company contact email address.
Telephone Number
Enter a telephone number where the responsible company representative can be contacted.
Preparer Information
Complete this section when another person prepared the report.
Preparer’s Signature
The person who prepared the return should sign here.
Title
Enter the preparer’s title or position.
Printed Name
Print the preparer’s full name.
Date
Enter the date the preparer signs the return.
Email Address
Enter the preparer’s email address.
Telephone Number
Provide the preparer’s telephone number.
Special Instructions for Surplus Lines
Special identification rules apply to surplus-lines filers.
Multi-Broker Filings
For a multi-broker filing, file under the agency name and its FEIN.
Single-Broker Filings
A single broker should also file under the agency name and FEIN.
If the single-broker agency does not have a FEIN, use the applicable Department of Insurance number instead.
Make sure the Surplus Lines checkbox on the return is selected when these instructions apply.
Monthly Filing Requirements
Insurers that do not qualify for annual reporting generally report and remit the insurance surcharge monthly.
The surcharge collected during each monthly accounting period must be reported and remitted by the 20th day of the following month.
The monthly amount is based on surcharge money collected during the preceding period, reduced by qualifying surcharge amounts returned to policyholders when policies were terminated.
The insurer is responsible for collecting the surcharge from the policyholder at the same time and in the same manner as the related premium or other insurance charge.
An insurer or its agent may not retain any part of the surcharge as a collection fee or commission.
Annual Filing Requirements
Insurers whose annual surcharge liability was less than $1,000 in each of the previous two calendar years may report and remit the surcharge on an annual calendar-year basis.
The annual payment and report are due on or before January 20 of the following year.
For this version of Form 74A118A:
- The reporting period is calendar year 2025.
- The return is due January 20, 2026.
- The annual form is not required when the liability was already reported monthly.
Even when an insurer had no premiums to report, the filing instructions state that a report must still be filed for the required reporting period.
Insurance And Premiums Exempt From the Surcharge
Several categories are specifically excluded from the Kentucky insurance premium surcharge.
These include qualifying premiums for:
- Accident and health insurance.
- Federally insured crop insurance.
- Federally insured flood insurance.
- Reinsurance.
- Title insurance.
- Workers’ compensation insurance.
The instructions also identify premiums received by life and health insurers as exempt for purposes of the surcharge.
Municipal premium taxes are also excluded.
These exclusions should be reflected in the appropriate fields on the return rather than simply omitted from the initial premium totals when the form directs that they first be included on line 1a.
Exempt or Partially Exempt Policyholders
The form identifies several policyholder categories whose qualifying premiums may be excluded.
These include:
- The federal government.
- Resident nonprofit educational and charitable institutions qualifying under Section 501(c)(3).
- Resident nonprofit religious institutions for qualifying real, tangible, and intangible property coverage.
- State government for real property coverage.
- Local governments for real property coverage.
Review both the identity of the policyholder and the type of coverage before claiming an exemption.
Surety and Public Works Bonds
Premiums collected for surety and bonds associated with public works projects remain subject to the surcharge when the contractor is the policyholder.
The fact that a governmental entity is the obligee does not by itself make the premium exempt.
When determining whether a governmental exemption applies, identify who is actually the policyholder rather than relying only on the identity of the obligee.
Returned Premiums And Surcharge Refunds
When a qualifying premium is returned because a policy was terminated, the related surcharge must also be returned to the policyholder before the returned premium is used as a deduction on the report.
Do not treat exempt premiums as returned-premium credits.
For example, a workers’ compensation premium is already exempt from the surcharge and therefore should not be treated as a refundable terminated-policy premium for purposes of line 2a.
Requests for refunds must be made in writing.
Late Filing Penalty
If the Insurance Surcharge Report is not filed by its due date, a late-filing penalty may apply.
The penalty is 2% of the surcharge due for each 30 days or fraction of 30 days that the report remains late.
The maximum late-filing penalty is 20% of the surcharge due.
The minimum penalty is:
$10
Enter an applicable penalty on line 5.
Late Payment Penalty
A separate penalty may apply when the insurance premium surcharge is not paid by its due date.
The late-payment penalty is 2% of the surcharge due for each 30 days or fraction of 30 days that payment remains overdue.
The maximum penalty is 20%.
The minimum penalty is:
$10
Interest
Interest applies to unpaid insurance premium surcharge liabilities after the original due date.
Interest is calculated from the original due date of the report through the date the liability is paid.
Enter applicable interest on line 6.
Final Review Before Filing
- Confirm that the correct annual or monthly reporting requirement applies.
- For this annual version, verify that calendar year 2025 is the correct period.
- Confirm that the return is due January 20, 2026.
- Do not use the annual return if the applicable liability was already filed monthly.
- Verify the company’s legal name and complete address.
- Enter the correct account information.
- Check Amended Return if correcting a previously filed report.
- Check Surplus Lines when applicable.
- Enter the correct NAIC number.
- Enter the correct FEIN.
- For surplus-lines filings, verify whether the agency FEIN or DOI number should be used.
- Include all collected Kentucky premiums required on line 1a.
- Do not include municipal taxes in line 1a.
- Report finance and service charges separately on line 1b.
- Add lines 1a and 1b correctly for line 1c.
- Enter only qualifying returned premiums on line 2a.
- Confirm that the related surcharge was also returned to the policyholder before claiming a terminated-policy deduction.
- Report accident and health premiums on line 2b1.
- Report federally insured crop premiums on line 2b2.
- Report federally insured flood premiums on line 2b3.
- Report reinsurance premiums on line 2b4.
- Report title insurance premiums on line 2b5.
- Report workers’ compensation premiums on line 2b6.
- Add lines 2b1 through 2b6 correctly for line 2b.
- Report qualifying federal government premiums on line 2c1.
- Report qualifying resident 501(c)(3) educational and charitable institution premiums on line 2c2.
- Report qualifying nonprofit religious institution property coverage on line 2c3.
- Report qualifying state and local government real property coverage on line 2c4.
- Add lines 2c1 through 2c4 correctly for line 2c.
- Add lines 2a, 2b, and 2c for line 2d.
- Subtract line 2d from line 1c to determine line 3.
- Multiply line 3 by 0.018 to calculate line 4.
- Enter any applicable penalty on line 5.
- Enter applicable interest on line 6.
- Add lines 4, 5, and 6 for line 7.
- Attach supporting documentation for any adjustment reported on line 8.
- Apply line 8 correctly when calculating line 9.
- If payment was made electronically, check the Paid Online box.
- Enter the online payment confirmation number.
- Attach the Payment Schedule Confirmation page when paying online.
- Have a principal officer sign the report.
- Enter the principal officer’s title and printed name.
- Enter the certification date.
- Provide an email address and telephone number.
- Have the preparer complete and sign the preparer section when applicable.
- Make any check payable to the Kentucky State Treasurer.
- Send the return and payment to the correct Kentucky Department of Revenue address.
- File a required return even when no premiums were collected during the reporting period.